SIF Folio: Evraz tempts me with 9% dividend yield

I don’t have a rigid policy of sector diversification for my systematic SIF Folio, as I think that runs counter to my policy of buying the top-ranked shares highlighted by my SIF buying screen. But I do try to ensure a reasonable spread of sector exposure across the portfolio’s holdings.
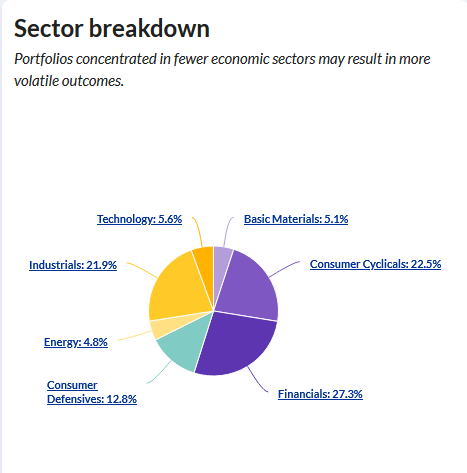
Given that stocks which pass all of my buying rules are still thin on the ground, I’ve decided to take a slightly different approach this week in my hunt for the next SIF stock. I started by taking a look at the current sector allocation profile of the SIF folio, using the Allocation tab in Folios.
To start with, here’s a snapshot of the portfolio’s current holdings by sector:
Next, here’s a second view showing portfolio sector weights versus those of the wider market. This makes it easy to see where your portfolio differs from the market. In this case, we can see that SIF has no exposure to the Telecoms, Healthcare and Utilities sectors. Elsewhere, the portfolio’s weightings are significantly different to the market average:
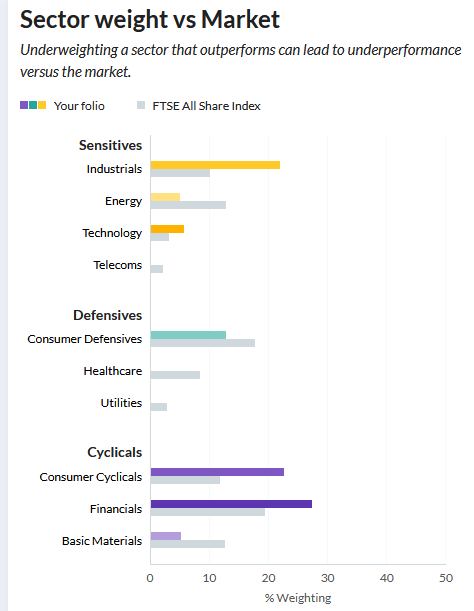
I would like healthcare exposure, but nothing even comes close to passing my screening rules at the moment and I’m not willing to overpay. I’m less worried about telecoms and utilities. I think there are some good options for income investors in these sectors, but I’m less convinced by the case for growth and total return.
I don’t try to match the market’s sector weightings, as I think that some differentiation is needed to have any chance of beating the market. However, I wouldn’t be averse to adding more exposure in Basic Materials or Energy.
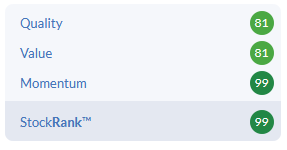
Having reviewed some possible options, the stock which comes closest to satisfying all of my requirements is FTSE 100 coal, iron and steel group Evraz (LON:EVR). Stockopedia’s algorithms have a favourable impression of this stock, awarding it Super Stock status and a high StockRank:
Evraz (LON:EVR)
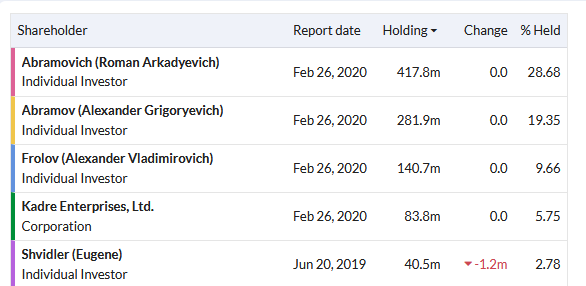
Evraz has Russian origins and concentrated private ownership. I tend to think of such companies as oligarch stocks.
The group’s largest shareholder is Chelsea FC’s billionaire owner, Roman Abramovich:
I’m normally reluctant to invest in Russia-based firms. My perception is they suffer from political risks and a certain lack of transparency. In this case I’m more relaxed, for several reasons:
Evraz is a FTSE 100 company that’s been listed in the UK for nearly a decade
The group has a sizeable steel business in the US and Canada, not just Eastern Europe
Cash generation appears robust and genuine
My perception is that the group’s owners are intent on capital preservation and income generation
Before I look at Evraz’s QVM factor scores, there are a couple of points I think it’s worth touching on.
ESG risk: SIF isn’t an ESG portfolio, but as an investor I’m conscious of the growing negative market sentiment towards serial ESG offenders. A particular risk, as I see it, is that borrowing costs may rise for such firms.
As a coal producer and consumer, I’d guess that Evraz could potentially be affected in this way. However, the situation may soon improve. Evraz is considering demerging its coal assets. Nothing is fixed yet, but the coal operations have already been consolidated into a separate Moscow-listed business with a market cap of $1.5bn.
I wonder whether completing this demerger might accelerate management’s ongoing efforts to cut the group’s borrowing costs, which appear to be fairly high at present.
Does Evraz pass my screening rules? Evraz passes all my screening rules except the dividend growth requirement. In common with many other firms the group cut its payout last year. Payouts have in any case been irregular over the years:
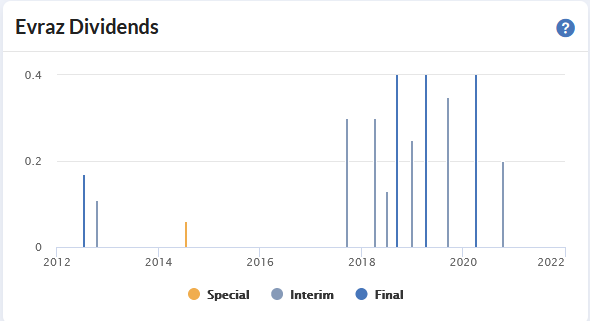
I think this variability reflects the cyclical nature of the group’s profits and its sizable debt burden:
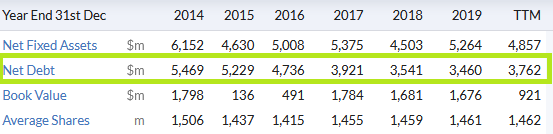
Is this a concern for me? Perhaps. I’ll explain more below as I take a look at each of the stock’s factor scores.
Value: Cheap cash flow?
A ValueRank of 81 suggests a decent level of affordability. I agree with this, with a couple of caveats. Starting with the positives, Evraz looks decent value on most of my preferred value metrics:
TTM price/free cash flow: 8
Earnings yield (EBIT/EV): 9%
TTM dividend yield 8.7%
TTM P/E: 12
I have two concerns about Evraz’s valuation. The first is that steel and iron ore prices are both close to record highs. Coal prices performed well during the second half of 2020 too. Commodity stocks often appear cheap at the top of the market cycle. This is because high commodity prices boost profits, while forward-looking markets start pricing in the risk of a slowdown.
I guess the bull case for commodities is that a post-pandemic infrastructure boom will boost demand. Evraz’s operations in the US would be likely beneficiaries, I’d imagine.
However, I have to consider the bear case, too. A drop in prices would probably be manageable but the group’s $3.7bn net debt could impact its ability to pay generous dividends. The 2020 half-year results specified a net debt/EBITDA multiple of 1.7. Needless to say, EBITDA would fall much faster than net debt in a downturn.
A coal exit might help to reduce the group’s leverage, depending on how it was structured. But $3.7bn of net debt is quite close to my preferred limit of four times forecast net profits. I’m not entirely comfortable with the balance sheet here.
Quality: pretty solid
Evraz has a QualityRank of 81, which suggests few serious concerns. That’s broadly in line with my view. I don’t think quality is outstanding, but it’s good enough.
The stock’s Piotrioski F-Score of 6/9 is within my permitted range. The shares’ five-year average return on capital employed of 15% is also pretty solid.
However, once again I think it’s worth considering the cyclicality evident in this business. Here’s a view of Evraz’s profitability since 2014. Remember, there was a big commodity crash in 2015/16:
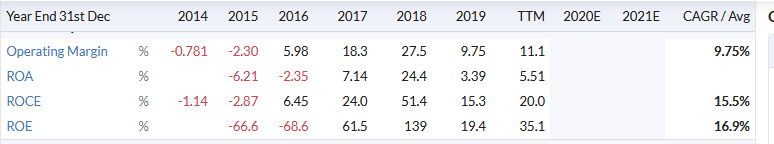
This is a useful reminder that to some extent, Evraz profits are dependent on market conditions rather than company performance.
Momentum: better than I expected
This is the kicker: Evraz has a MomentumRank of 99, with strong price momentum and improving earnings forecasts.
Price momentum: As we can see from the Momentum graphic on the StockReport, Evraz is performing well on most measures of technical momentum:
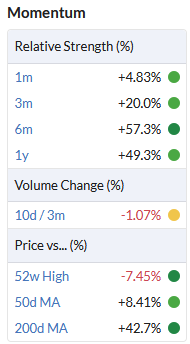
The only point I’d make here is that buying volumes seem to have levelled out. The 10d/3m measure in the graphic above compares trading volumes over the last 10 days with the three-month average. A reading of -1% suggests that dealing volumes are pretty much in line with averages.
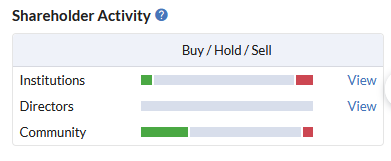
Using the Shareholder Activity tool, we can also see that institutions have been marginal net sellers during the last quarter, while the Stockopedia community have been net buyers:
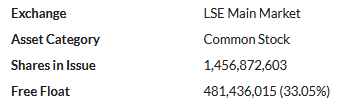
Evraz’s concentrated ownership means that it’s free float is unusually small for a FTSE 100 firm. I suppose this might explain the limited institutional ownership:
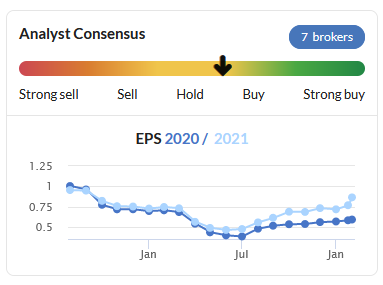
Earnings estimates: Analysts covering the stock have been upgrading their forecasts.I’m particularly pleased to see forecasts for the year ahead (FY21) have recently been upgraded.
Despite my concern about cyclical risk, it’s clear that Evraz scores well on all momentum measures at the moment. It’s hard to find much to fault.
My verdict
I’m torn about this. My gut tells me that this might not be a great time to buy into big commodity stocks. I’m also a little unhappy about the group’s inconsistent dividend history and relatively high debt.
However, I’m not meant to make too many subjective decisions when picking stocks for SIF. My rules require a systematic approach that delivers consistent choices.
The reality is that Evraz shares pass all of my tests except on dividend growth. I think this can be overlooked given events in 2020. The stock also looks cheap, with a 2021 forecast P/E of 8 and a yield of 9.8%.
Management are starting to act on ESG concerns and are already working to refinance debt at lower rates. Meanwhile, broker forecasts suggest performance should improve in 2021.
I feel that the correct decision is to buy Evraz for SIF (and for my own mirror portfolio). So that’s what I’ll do this week, after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
I think most people have missed the boat on this one at least in the very short term. I would like to see it test the £5 mark a couple of times and then assuming it holds there for a while, have another look at the fundamentals.
Well. My getting off @ 544p (missing the 600p) isn't looking stupid or mournful anymore.
EVRAZ (LON:EVR) hit peak around 03/03/2021 of 600p... down curve since. Why?
Now 526p.
It does seem to do this... good bull runs then bear runs.
I consider myself very lucky indeed with the ride and profit I had on this.
Stocko now says within 1% of Broker Target. I guess 500p will be tested. I think it will drop through.
Alas Apax Global Alpha (LON:APAX) too. Bull run fizzled out at 220p and dropped back to 189p.
Ha! I'm definitely not pushing my luck, Wilkonz.
I concur. EVRAZ (LON:EVR) likes the occasional drama and pullback. Its partly Russian!
Sold. It looks like my 18 month investment in EVRAZ (LON:EVR) has yielded a 48% capital gain plus delicious dividend yield. Its a shame about that 6% drop off yesterday's super-high.
I consider this a very good run for my limited skill set.
For all Investors, best of success on Thursday and Dividend day!
Well judged! I bought @ around 350 last August and sold out when they stalled, breaking even. Should have kept the faith! (I can remember selling out at 670 a couple of years ago making a useful profit.) Iron is looking good, so I've moved on to Ferrexpo (LON:FXPO) . I think Evraz (LON:EVR) may have further to go but it has a track record of dramatic pullbacks so it's always smart to quit whilst you're ahead.
Holy smoke. I'm up 54% on EVRAZ (LON:EVR) as I type, with the dreaded Full Year Earnings showing up on Thursday 25th February 2021.
Its been a hell of a ride... I've got a new house to buy... tempted to sell.
Have you looked at Ferrexpo (LON:FXPO) ?
Navalny. Locking up Navalny for 3.5 years pretty much guaratees as least another 3.5 years of sanctions against Russia and those close to Putin.
That is a great shame as those years could see a commodities boom from infrastructure investment that Evraz (LON:EVR) seem well placed to profit from.
Oh! If only Russia and Russian companies were just a little more 'normal' in the Western sense. Tragedy for the Russian people, again and again and again.
M.
Having bought and sold Evraz (LON:EVR) a few times over the last 3 years, it's now a company in which I probably won't invest again. The problem lies in the dividends - my impression is that the directors take on large amounts of debt in order to pay themselves large dividends. The process is unsustainable, and despite some good metrics, I have no confidence in the directors or the long term prospects of the company. My perception is that dividends over 5% should be seen as a red flag and I'd like to see the dividend money used to pay off the debt not the directors.
I kind of agree with this and if you look at the dividend cover this company should not really be paying dividends at all at the moment.
Hi Roland, I looked at buying Evraz last year and this year but two conditions have prevented me from investing in the company.
Firstly, the Net Gearing is 408%. One of my rules is not to buy shares in a company when the Net Gearing is above 50% and to sell shares when the Net Gearing exceeds 100%.
Secondly, the Book Value is $921 million and the Net Debt is $3,762 million. Another one of my rules is to sell shares when the Net Debt is double the Book Value.
I look for businesses with a healthy balance sheet but in my opinion this is something I believe Evraz is lacking. Because of the above reasons I have refrained from buying shares in Evraz.
Hi Roland,
If in doubt ,leave it out would be my suggestion. The share has not gone XD yet and there is no guarantee they will payout a dividend untill they announce that they will pay out.
For it to give 9% it would have to pay out 45.25p a share on the current share price of 502.8p. In any case ,as you have already stated dividend payments have been irregular, so another red flag. Then the debt problem as well.
I am just waiting for my twelth dividend payment in total, for this month's payout due on 5/2 from IBPO. This is over 49p a share on about a 300p share price from last year's, purchase. This is worth a bit over 16%, and worth waiting for. Even if it was 400p a share, that still gives over 12%.
My good friend Max in Australia will not buy shares unless they pay a decent consistant dividend. If the dividends stop coming in , he sells the share. The important thing for him is consistant and they usually increase each year as does the share price.
Its Dividend cover this year is a very low 0.5 but forecast to improve. This would be a worry for me but might be worth the risk.
Afternoon Roland, I'd be interested to know why you think that now is not a good time to buy big commodity stocks, and, perhaps crucially what was the deciding factor that saw you add to SIF portfolio regardless?
Interested in macro thoughts and process.
Hi IncredibleMosesLeroy,
Good question - the short answer is that I invest by the rules for SIF precisely in order to overcome my own subjective judgements. For example, I can see that iron ore prices are at historic highs, so I assume they are heading for a fall. But I might be wrong - or at least, my timing my be wrong.
In theory, I believe following a system should provide more consistent results, as the inputs to the portfolio will be more consistent.
So far this approach worked well enough for me to beat the market since 2016, but many others have done better through a less structured approach.
The deciding factor in adding Evraz (LON:EVR) to SIF was that I don't allow macro views to control portfolio decisions. I focus on specific stock selection criteria, all of which Evraz met (with the exception of dividends, where I'm allowing some flexibility due to the pandemic).
In general I try not to make too many macro calls. Although they are tempting, I don't have much confidence in my ability to time them correctly. I've been expecting house prices to fall for years, but they still haven't!
Regards,
Roland