SIF Folio: Gold miner Centamin gives me little choice

Last week’s decision to sell pawnbroker H&T Group and gold mining services provider Capital means that my SIF folio has no exposure to gold. In a world of zero interest rates and macro uncertainty, that may not be ideal.
I have to fess up to another problem with the portfolio this week, too. The 16 stocks in SIF are concentrated in just four top-level sectors:
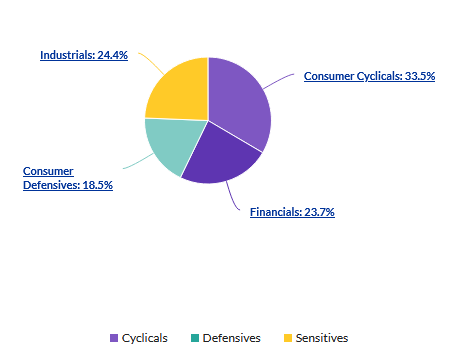
In my defence, this isn’t specifically a breach of my rules. But it’s not necessarily ideal. Adding a gold miner would provide exposure to a commodity that tends to perform well in difficult times. It would also add a fifth sector - Basic Materials - to my portfolio.
Although I’m concerned about the risk that the gold market will peak, I accept that we may not be at that point yet. As far as I can see, there’s not much sign of the froth that has marked the high water level of previous commodity booms. Gold equities don’t look obviously mispriced to me.
In any case, my rules are designed to prevent me taking macro positions and instead focus on selecting companies with attractive characteristics. The SIF screen is not currently identifying many opportunities in the UK market:
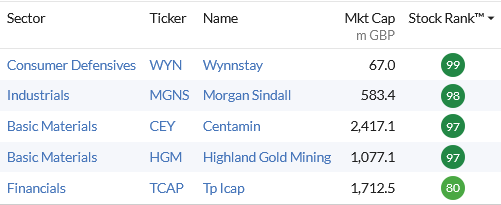
Of these, Wynnstay and Morgan Sindall are already in SIF.
Highland Gold Mining is in a bid situation.
TP ICAP would be a possibility, but I already have several financial stocks. This share also has the lowest StockRank in the screen results.
My rules specify that my screening results should be ranked by StockRank, which means that FTSE 250 gold miner Centamin is the only possible choice this week.
Centamin (LON: CEY)
I’ve followed Centamin’s fortunes for a number of years. On the whole, I think this Egypt-based firm is a good business. It’s profitable and cash-generative, with a strong balance sheet and track record of attractive dividends.
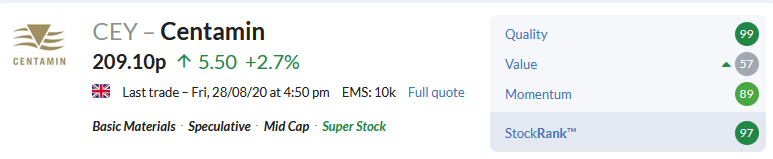
Stockopedia’s algorithms like the shares too:
However, long-term followers of this mid-cap miner will know that it’s not always been a smooth ride. Although the shares have delivered an impressive 2,500% gain since Centamin’s 2001 listing, keeping the faith has been challenging at times:
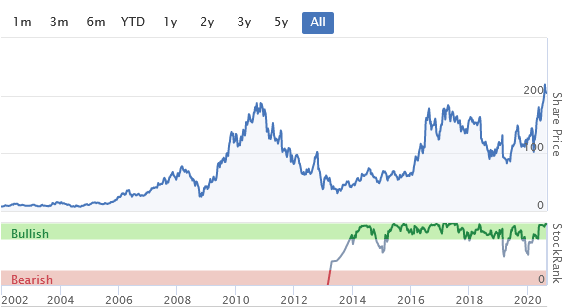
Political risk: Leaving aside the gyrations of the gold price, the other factor that’s had a big impact on the performance of Centamin stock is political risk. During the Arab Spring period in 2011-2013, Centamin’s mining concession was challenged in a court case. The firm was also forced to start paying higher international prices for diesel fuel, rather than the subsidised local rate.
My feeling is that these events were politically driven. Since 2013, they’ve faded into the background, but investors should note that both cases are still ongoing. Management are confident that they will reach a favourable conclusion, but of course there’s no guarantee of this.
Personally, I would argue that the diesel case is not a concern, since Centamin has been paying international rates for diesel since 2012. Clearly the business is still viable.
However, I think the case relating to the firm’s mining concession could still cause problems. If you’re interested, you can find fuller details in footnote 5.1 of the 2019 results.
With that disclosure out of the way, let’s get back to the numbers.
Value: not so great
Centamin’s ValueRank of 57 does not appear to suggest that the shares are a bargain. It’s not too hard to see why. The shares trade on 28 times 2019 earnings and at 2.5 times their book value.
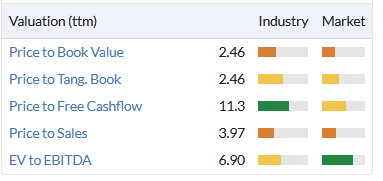
The only numbers which do look cheap are my favourite measures, price/free cash flow and earnings yield (EBIT/EV):
P/FCF: 11.3
Earnings yield: 10.5>#/p###
However, these figures carry a big caveat. The profit and free cash flow they imply isn’t all available to shareholders, thanks to a very material profit-sharing arrangement.
Profit sharing: Centamin’s sole production asset is the Sukari gold mine in Egypt. This is owned in a 50:50 partnership with the Egyptian Mineral Resources Authority (EMRA). Although Centamin’s mining licence appears to give the company full operating control of the mine, this partnership does mean that Centamin is currently paying roughly 50% of its profits to EMRA, in addition to a 3% revenue royalty to the Egyptian government.
In 2019 Centamin paid $19.7m in royalties and a profit share payment of $87.1m to EMRA, from revenue of $658m. Although pre-tax profit was $173m, net profit attributable to shareholders was just $87.5m.
This profit-sharing agreement explains a few apparent quirks in the StockReport data for this share:
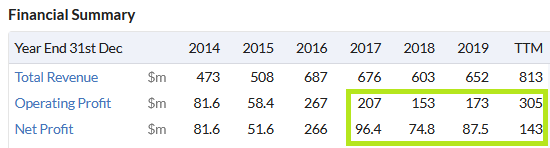
The screenshot above highlights how Centamin’s operating profit has been roughly two times the group’s net profit since the current profit sharing agreement kicked in in 2017.
Fortunately, the firm’s earnings per share reflect the net profit attributable to shareholders. So the P/E ratings shown in the StockReport are accurate, as far as I can see.
However, my sums indicate that the free cash flow per share shown in the StockReport includes the profit share payout. Accounting profits don’t always map directly onto free cash flow, but in this case I think a fair approximation is that c.50% of free cash flow should be available to shareholders.
This suggests that dividends have exceeded the free cash flow available to equity in recent years, with the balance being funded by Centamin’s sizeable net cash balance:
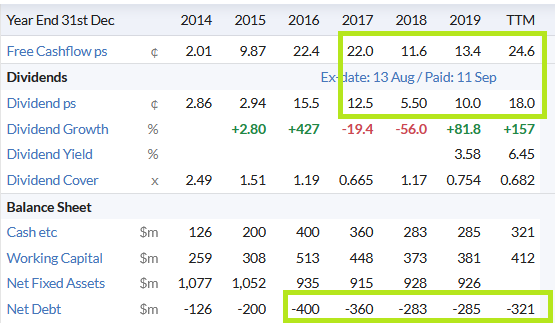
I don’t see this as a problem, given the group’s lack of debt. Indeed, if the gold price remains high this year it seems likely to me that net cash will stabilise.
My view: The structure of Centamin’s mining agreement leaves it somewhat vulnerable to hostile political action. And from a purely financial perspective, the shares don’t seem especially cheap to me. But the numbers all seem to stack up okay. I don’t have any concerns about the company’s accounting or its dividend policy.
Quality: profitability shared
Centamin’s QualityRank of 99 suggests a very strong set of profitability metrics. For the most part, I agree.
In 2019, cash costs of production were $699/oz. The all-in sustaining cost of production (AISC) - a more inclusive measure which includes a mine’s lifecycle costs - was $943/oz. These low costs underpin the group’s strong cash generation. If the gold price stays close to $2,000/oz, 2020 should be a bumper year.
Centamin also scores well on standard financial quality metrics.
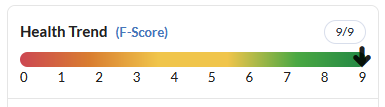
The group’s strong balance sheet, cash generation and improving profitability is reflected in its Piotroski F-Score of 9/9 (Ben published an excellent piece on the predictive power of the F-Score last week - see here).
However, Centamin’s profitability metrics need to be viewed in the context of its profit-sharing arrangement. In the screenshot below, we can see that return on capital employed (ROCE) is roughly twice return on equity (ROE):
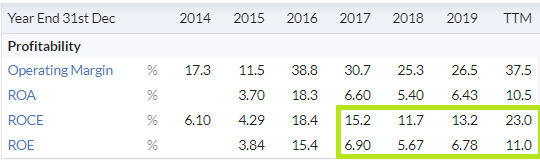
Given Centamin’s lack of debt, I’d normally expect ROCE to be more closely matched to ROE. Capital employed would closely approximate equity, while operating profit (used in ROCE) and net profit (used in ROE) would only be separated by tax payments.
The reason for the larger difference between ROCE and ROE is that Centamin pays roughly half its pre-tax profit to its state partner. This reduces return on equity to fairly average levels, despite impressive returns on capital. The effect is as if Centamin pays 50% tax.
My view: How should we reflect this unusual situation in our analysis of Centamin?
In this case I’m willing to give Centamin a pass, due to its debt-free balance sheet, strong underlying profitability and solid track record of shareholder returns. But if the business didn’t have such strong fundamentals, I’d take a much more cautious view.
Momentum: fingers crossed
No one knows how the gold market will perform over the next 18 months. Centamin also faces a number of company-specific risks. I mentioned some earlier. More immediately, management have also warned that if COVID travel restrictions extend beyond Q3, operations could be disrupted.
The company’s dependence on a single production asset also carries risks. The Sukari mine is currently undergoing a life-of-asset review. In a worst-case scenario, the mine’s remaining reserves could be downgraded. Future ore grades could be lower, increasing costs.
However, these risks apply to most miners, to some degree. I’m not here to make speculative judgements on what might happen.
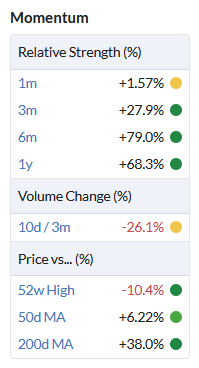
What we do know is that Centamin’s technical momentum metrics are currently strong:
Earnings forecasts have been rising steadily, too. Analysts expect 2020 profits to be sustained in 2021, if not increased:
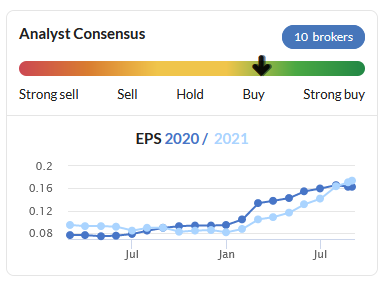
My view: Centamin shares have strong technical and earnings momentum. At the time of writing, the stock trades on 16 times rolling forecast earnings, with a prospective yield of 4.9%.
Overall, I’d say this is an attractive picture. The obvious caveat is that it’s heavily dependent on the future gold price and on mine-specific factors.
My decision
I have little choice here. Centamin passes all my screening rules and would add welcome diversity to the SIF folio. My contrarian nature makes me reluctant to jump on a bandwagon so late in the day. But the whole point of SIF is to prevent this kind of mental bias and follow the factors.
I will add Centamin to the SIF folio and to my own holdings this week, after this article has been published. As always, I’d very much welcome your views on gold and gold miners in the comments.
Disclosure: Roland owns shares of Wynnstay and Morgan Sindall.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Some of the points that Roland has raised concerning Centamin (LON:CEY) also, in my view, apply to many other Gold mining companies. Jurisdiction is often a problem: the company's relationship with the Government is crucial to its survival. A company based on a single mine is generally also risky - too much can go wrong: Technical issues can be difficult and expensive to rectify - generally the deeper the mine, the more intractable the problems. And that's for starters. Throw in local "Community groups" as well as unions and artisanal miners encroaching on projects and it can get messy. Even if the Gold price rises, a Gold stock can fall for the reasons given above. As a way into Gold as a theme, I prefer a mix of individual Gold producers and collective funds. Covering underground and overground (Especially tailings) operations with a bias towards low-cost production. But I certainly would not put all my eggs in one golden basket. Ironically, I suspect that rising Gold prices may exasperate some of the above problems.
There are only a handful of large gold miners out there*. Rick Rule gave Centamin a high score and said they were cheap hence my interest in them. Their >7% dividend is nice too.
*Note that Apple's current cash position could buy every single gold miner in the world. It is a small/risky market and not for the risk averse.
£CEY is starting to look really cheap? Has this oversold?
Yes it is looking cheap. And it ought to be an excellent long term prospect at this price (126) as Donald Pond suggests. I got stopped out at 179 and am looking to buy back but I'm waiting for a definite sustained upward move, possibly up to the 200 day EMA before buying back (say around 150-160). The problem as always is calling the bottom, and with the current macro uncertainties (Covid, US election), the price could still fall well below 100 before recovering.
Wilkonz. Agreed, the spot price is sitting between the 50 and 100 SMA. Gold will pull back if we get a repeat of March & the weak handed selling for margin calls.
Nevertheless my thesis remains the same, more rounds of currency debasement (stimulus packages) are on their way, more Friedmanian helicopter money to the proletariat and eventually an upward shift in the velocity of money. This time next year I expect the spot gold price to be significantly higher, of course I would like to time this properly and buy in the big pull backs - the question is will we get a big pull back before the next FED round of confetti money.
Centamin's >7% dividend is pretty attractive right now considering their value/quality.
The price of Centamin (LON:CEY) has fallen about 20% this morning (around 161 pence as I write) because of delays at the open pit Sukari mine - presumably due to safety concerns with ground movement. The drop hit my stop loss at 179 and I no longer hold but I believe the company is intrinsically sound and I may buy back at 150 pence if the price falls further. It sounds as if the response to the bad news has been somewhat overdone but I'd be interested to know other opinions.
I don't hold but this seems to me a short term issue that will affect production for a quarter or so but then have no long term impact. So while picking the bottom may be tricky I think it presents a buying opportunity if you are keen on the company
Thank you for your informative and thought provoking article. As a holder of Centamin shares for some years, it's been a roller-coaster of a ride, but I shall continue to hold them for the time being with rather greater peace of mind.
A thought provoking article Roland. I have been in Centamin for a few years and it has rewarded me admirably and over the last 9 months been top slicing and am considering letting the rest go looking for a multi basic materials stock. As they say it is a fluid market, and no one is right or wrong!
Roland
I like the gold (and silver) sectors and have a spread of precious metal investments (in descending order). I view them as as good cash, with upside potential.
Royal Mint Physical Gold ETF
Centamin – Best single Gold miner idea
Ninety One Global Gold
Golden Prospect Precious Metals (£GPM) 70% Gold/30% other metals
Fresnillo – Mainly Silver
Global X Silver ETF
Sylvania Platinum
An interesting podcast yesterday with Meb Faber where silver gets a particular mention. https://mebfaber.com/2020/09/0...
Extract.... We produce (internationally) about 800 million ounces of Silver a year, but so far this year, we’ve had almost 300 million ounces go into the ETFs. So maybe by the end of the year, it’ll be 500 million ounces go into the ETFs. Well, if we produce 800 and the industry needs 70% of it, how do you get 500 million going to the ETFs? Plus all the offtake and the COMEX (Futures)? I mean, something’s missing here. And let alone the coin sales all the data in silver is screaming at me that what we went through for these last decades has been wrong and that we’re going to correct itself. The same is true of gold.
My biggest single holding is a UK listed gold miner, and so I am cutting off my nose a little here, but if you want exposure to the gold market, I'm really not convinced that you will do better than buying either an ETF, or one of the giants like Barrick or Newmont. Funds such as the Ruffer Gold fund and Ninety One Global Gold have also generated brilliant returns. It is a sector in my opinion where the UK market offers slim pickings, unless you are willing to look at more junior plays. There's no shortage of those, and some (I'm thinking Pure Gold Mining Inc (LON:PUR) and Phoenix Copper (LON:PXC) look very promising).
Pure Gold Mining Inc (LON:PUR) certainly merits further examination, it's due to go into production in December 2020. Because it's not yet in production, it does come with risk. However, it has carried out around 1.3 million metres of drilling on its assets (Some 47 square kilometres). So it probably has a very accurate picture of its resources. It also looks set to be a low-cost producer (AISC of US$787 per oz). Importantly, it's Canadian focused. So there are no jurisdictional issues. This is something that I think many investors overlook - rising Gold prices are great for Gold miners but that makes them a target for corrupt and incompetent Governments.
As you mention, the London market offers slim pickings and so investors may be better served through some form of collective investment. Incidentally, I certainly would not put all my eggs in one basket. Gold mining is simply inherently risky.
I understand the real hesitance reflected in the article, I guess is to be expected given Centamin's historic volatility and current berthing around ATH's, along with the metal. I am a holder since 2017 and I must admit it has been a trying long term hold at times, but for lack of other good precious metals offerings on the LSE it serves it's purpose (I did hold Randgold however sold the Barrick shares recently). One thing I do like about Centamin is the potential for exploiting other resource locally, Centamin is currently the only operating miner in Egypt, and with the prospect of other significant gold finds in the area it is not outwith the realms of possibility that they may expand the operations here in the future. I understand there is an auction of mining licenses ongoing currently. Perhaps this is what the $300m+ is being held in reserve for, they do not seem keen to throw it at their west African sites, which they might instead prefer to sell on...
I'd want to see $HUI break 360 before buying into any gold miners
The US election is weakening the dollar and I don't believe that either candidate winning is going to strengthen it in the short term. Gold is therefore likely to benefit and Cantamin's fundamentals look strong. There's political risk with almost every gold miner and Egypt seems less of a threat than Russia or any of the unpredictable African countries.
Hi Roland, I think Centamin is as good as any as a gold play if you have SIf criteria to hit. if you want to see some more opportunity for growth outside the Sif portfolio my choice is still Ariana. Also, I put Golden prospect precious metals(GPM) up against it on the compare tool and GPM beat it on the system. I would have GPM because of the price and its a bit more diverse
Hi Roland
Centamin (LON:CEY) is on my list of possible candidates should I decide to diversify my gold miner exposure. As I recall, their AISC is around $900 which is great at current gold prices. They would be susceptible if there were a significant change in the price of gold. That said, gold is very strong and the weakening dollar, negative yields and expansion of the Fed (and other central banks) balance sheet all suggest that gold has some way to go yet. Plus, as you have highlighted, there is some legal/political risk. Centamin is a good company though and I would be comfortable holding it as part of a basket of miners.
Cheers
Simon
Why didn’t you consider Pan African Holdings (PAF) a better bet? Metrics seem stronger and big bounce in profit and cash generation is certain. Disclosure. I hold.
Hi mmol,
Interesting suggestion re £PAF. The only reason I didn't consider it was that it fails one of my screening rules - it's too cheap!
The rolling forward P/E is currently 4.9, which is below my minimum P/E of 7.
I use this rule as part of my quest to avoid outliers - when a stock has a P/E this low, there's often a reason for it. (I don't know of any specific problems at PAF, but perhaps the market is unsure if the FY21 forecasts can be achieved - they imply an 88% increase in earnings).
Cheers,
Roland
Too cheap??? Strange reason not to buy stock! And up from 10p to c. 24p since I started buying. The metrics in terms of future profits based on current gold price, production costs and production volumes (oz) look very very encouraging. Do the maths. Cash generation should be tremendous, and now American investor interest to add to the mix. Disclosure. I hold 570k shares.
Bought this as a political/gold play some years ago,still not comfortable with all eggs in egypt,have taken profits recently,GOVERMNENTS can make strange moves in these times?