SIF Folio in April: Should I sell in lockdown? Plus CAPD, HAT and MGP

It’s the end of the month. This would normally mean that it’s time for me to review and consider selling any stocks that I’ve held in the SIF folio for nine months or more.
In the turmoil of March’s market crash, I suspended my usual month-end review. I could see no benefit in selling stocks into such a negative market. This week, I need to decide whether to return to my normal trading rules or extend my selling ban until visibility improves.
I’ll also take a look at the latest news from three stocks which should be under review this month:
Capital Drilling (LON:CAPD)
H&T Group (LON:HAT)
Medica Group (LON:MGP)
The lockdown dilemma
In my main personal portfolio, all of my positions are held for the long term. Managing the crash has been relatively easy. So far, I’ve only sold one share in this portfolio this year (to swap for a better quality peer). Otherwise, all I’ve done is to selectively average down on some positions.
The situation is more complex for the SIF folio (which I also own in smaller size). This is essentially a trading fund, where the typical holding period is just over nine months. I expect most if not all of the companies in the portfolio to stage a decent recovery eventually. But in some plausible scenarios, this could take several years. I can’t wait that long.
My inclination is to wait until forward visibility improves before selling any stocks. But this could backfire badly. When forward visibility improves, the view could be grim. We could see a renewed market slump as the harsh reality of what’s happened hits investors.
Conversely, the world’s economies could rebound relatively quickly, cushioned by the vast wave of government support measures which have been put in place.
If I continue to sell stocks on my usual schedule, I’m effectively taking a neutral stance. This has been the strategy I’ve followed religiously over the last four years.
However, the current situation is unusually severe. It’s been 12 years since we had a market crash of this magnitude, and 100 years since we had a global pandemic. I think I can justify taking a more active stance in such circumstances.
My decision: On a long-term view, I share Warren Buffett’s view that stock markets will generally continue to rise. But over the short term, and perhaps even the medium term, I’m less sure.
I’m also concerned that I shouldn’t stray too far from the rules-based ethos of the SIF folio. The whole point of the strategy is that I allow my rules (you can see the SIF screen here) to interpret the data objectively and consistently. The screen’s output guides my trading decisions.
I don’t want to distort this process too much. But at the moment, I feel we’re almost in a false market. As Graham highlighted in Monday’s SCVR, valuation and forecasting is almost impossible for many companies at the moment. Until we know the likely extent of the lockdown, this won’t change.
Taking all of this into account, I’ve decided to extend my selling ban until the end of May. From then on, I will consider stocks on a case-by-case basis, with a strong bias towards following my normal rules. That means I’d return to selling stocks after nine months if they no longer qualify for my screen.
Portfolio performance review
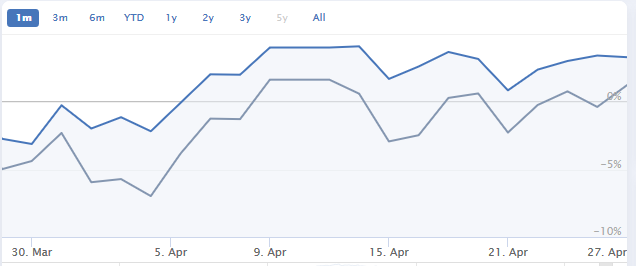
In the interests of transparency, let’s start with a look at how the portfolio has performed over the last month. This chart shows SIF (dark blue) vs the FTSE All-Share (grey):
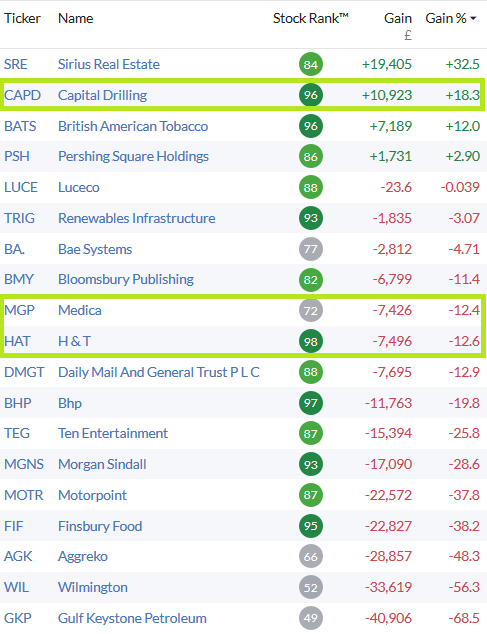
Here’s how the full portfolio looked at the time of writing (27 April). I’ve highlighted the three shares that are due for review this month:
Let’s take a brief look at the latest news from each of these three firms.
Capital Drilling (LON:CAPD)
(Original coverage: 02/07/2019)
Capital Drilling is a Main Market-listed drilling contractor whose main business is supporting gold miners in Africa. The firm’s client list includes many of the world’s largest gold producers.
First-quarter trading looked fairly strong, supported by the group’s continued expansion into West Africa. COVID-19 does not appear to have caused any significant disruption to the group’s operations.
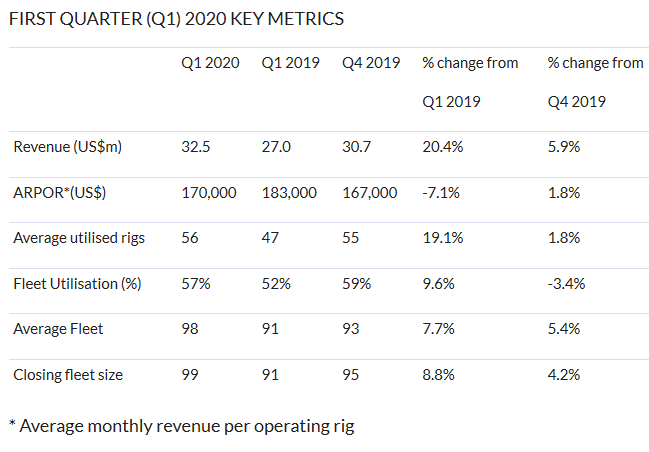
Naturally, the strength of the gold price over the last year has been “highly supportive”, as it encourages the group’s clients to invest in exploratory drilling and expansion capex.
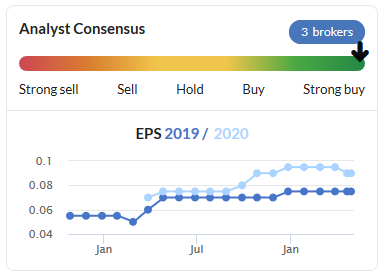
Brokers remain positive, too:
The shares looked decent value to me, trading on around eight times trailing free cash flow and a similar multiple of forecast earnings:
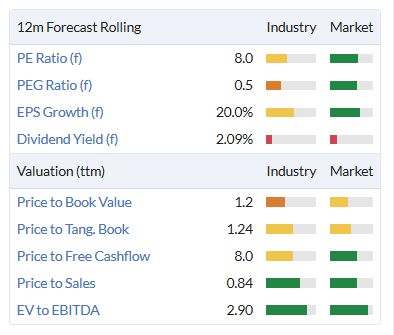
Capital Drilling no longer passes all of my screening tests, so I would normally sell this stock. However, the only two rules it fails relate to the stock’s dealing spread and the dividend growth rate.
In the current situation, these don’t seem like compelling reasons to sell to me. Especially as the group ended 2019 with a net cash balance.
My view: The only real concern I have about Capital Drilling is that it could be hit by a slump in the gold price. There’s no way to know how likely this is. But for the next month, I will accept this risk.
Total return to date: +19%
Verdict: Hold
H&T Group (LON:HAT)
(Original coverage: 16/07/2019)
The UK’s lockdown measures required H&T to close its estate of 253 stores. However, the impact on this pawnbroking and personal loan firm seems likely to be lower than for traditional retailers.
In H&T’s COVID-19 update, management suspended the dividend but sounded fairly sanguine about the outlook. Graham covered the update in more depth here. I share his view that shareholders probably don’t need to be too worried.
My screening rules don’t entirely agree. They fail H&T because the stock’s forecast rolling P/E has dropped to six, below my minimum of seven. I have this rule to filter out abnormally cheap stocks. But at the present time, I don’t think it’s relevant for otherwise strong businesses.
My view: Given the continuing cash flows from its loan business and government support on wages and business rates, I think H&T will survive lockdown without too much drama. I’d be a buyer at this level, personally.
Total return to date: -13%
Verdict: Hold
Medica Group (LON:MGP)
(Original coverage: 23/07/2019)
Medica Group provides outsourced ‘teleradiology’ services to the NHS, which is the group’s sole client.
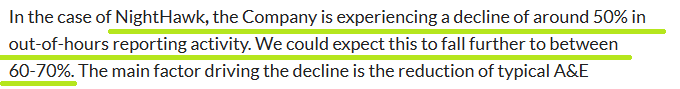
The COVID-19 pandemic has resulted in a dramatic reduction in regular admissions. This has caused a sharp reduction in demand for the group’s services. This applies to emergency out-of-hours services:
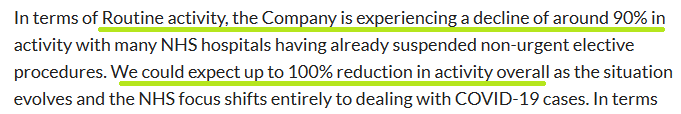
And also to routine scheduled demand:
I think it’s fair to assume that demand will gradually return to normal as the COVID-19 pandemic eases. But at this stage I don’t think we’re in a position to predict when this might be.
That’s one concern. I’m also a little worried about the change of CEO and CFO this year. The new CEO appears to be targeting more aggressive expansion and aiming to double revenue in five years, with the help of some extra capex.
There’s also the potential for further pushback on margins/market share from the NHS, which is apparently considering setting up its own teleradiology reporting networks.
However, Medica’ balance sheet looks fine to me and the group notes that two-thirds of its cost base is variable. Essentially, it doesn’t pay radiologists if they’re not working -- these consultants could be said to be moonlighting as highly-paid gig workers!
My view: Medica shares aren’t without risk, but I think it makes sense to wait for some clarity on the outlook. I’d also like to see brokers’ forecasts for the 2021 financial year, which have not yet appeared on Stockopedia.
Although Medica doesn’t pass all of my screening tests, this might change when the FY21 figures filter through. At this point in time, I think it makes sense to sit tight.
Total return to date: -12%
Verdict: Hold
Disclosure: Roland owns shares of Capital Drilling, Medica Group and H&T Group.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Roland, once again thanks for a very interesting article. H & T looks an interesting possibility at this price but I have made no move so far.
My eye is also drawn towards one of your holdings ,GKP ,particularly since reading Michael Taylor’s recent note. I hold no oil stocks in my portfolio at present and have not for some time but at these prices unless you think that the industry is about to be wiped out , there has to be value and serious money to be made should things ever return to normal.
GKP has plenty of cash and as Michael pointed out directors have been buying shares. I have no doubt that if this share came up as having been in the SIF portfolio for nine months it would be evicted under your rules, I cannot get over the thought that buying these shares at his price would look to have been a clever decision in a couple of years time. After all what else could go wrong for the oil industry. Am I brave enough to have a punt?
Roland, do you have any further thoughts on this stock at this time?
BB
Thanks for your thoughts, as always, Roland. Very interesting and I agree with you that the market does seem somewhat false, or perhaps disconnected to reality. I also believe that the markets will ultimately recover but share your view that there may be some pretty grim updates on their way over coming months which could well lead to a further sharp leg or legs down. An interesting article on this from Seeking Alpha describes some of the disconnect from reality and the potential for chaos if millions of unemployed Americans stop paying their bills because they are literally unable to do so. Scary stuff as it explains how this could be the first step in the debt fuelled house of cards tumbling down.
https://seekingalpha.com/artic...
Richard
Roland,
I'd appreciate your thoughts on Finsbury Food (LON:FIF) - I picked up some after your thorough analysis earlier this year. I'm still reasonably confident but the lack of rebound (or any volatility) is confusing to a relatively new investor.
Cheers.
IncredibleMosesLeroy,
Thanks for your comment. I thought that the latest (COVID-19) update from Finsbury Food (LON:FIF) was fairly encouraging. Broadly speaking, the firm's foodservice sales (to cafes, etc) are suffering but sales through supermarkets are going well, as you'd expect.
https://www.stockopedia.com/sh...
Although it's too soon to say exactly what the impact will be, I'm not too concerned overall. I don't see any serious risk to the survival of the business.
Debt looks manageable to me and the firm appears to have access to enough cash to handle any short-term impacts. In my view, the shares look decent value at current levels, as far as anyone can tell.
I wouldn't read too much into the short-term share price action - this is a small cap (£80m) and liquidity isn't great. So dealing volumes could be low.
I'm quite comfortable continuing to hold, although of course this is only my opinion. Please DYOR.
Regards,
Roland
Hi Roland, having just engaged in both Investing / Trading & Stockopedia I welcome your transparency article as key to my learning curve. Can I ask are the £values actual pound notes invested. If so the negative values are a real eye opener. In particular Gulf Keystone. If it is actual money invested and as advised by many of the experienced traders I have read about, why has a “stop loss” not been activated
Hi Captaincarter,
I should have made it clear that SIF folio that's pictured in the article is a virtual fund, based on a £1m starting value in April 2016.
Although I am personally invested in these stocks with real cash, the amounts involved are much smaller!
Re. stop losses. I don't use stop losses as I have never been able to achieve satisfactory results with them. In my experience they are either too high or too low.
In more normal times, I do have a rule for SIF which forces me to sell stocks after a profit warning. I'm not doing this at the moment as almost every company on the LSE is expecting a hit to profits this year (except Plus500 (LON:PLUS) and its peers!).
Cheers,
Roland
thank you Sir, i can now sleep more soundly tonight :)