SIF Folio: Is Cake Box the next Domino's Pizza?

The momentum that carried the FTSE 100 up from a low of under 5,000 to almost 6,500 seems to be fading. The FTSE has slipped back in recent days and is hovering around 6,000 as I write.
The pullback appears to reflect concerns about the longer-lasting impact of the coronavirus pandemic. Much of the news and views I’m reading are inconclusive and contradictory, but I think I’m starting to see a pattern.
Retail and hospitality businesses are enjoying a strong bounce as they satisfy pent-up demand. But cyclical businesses which need to plan for the next couple of years are preparing for a period of weaker demand, by cutting capacity and laying off staff.
Airlines, car makers and industrial firms with exposure to aviation and oil are among the examples on this depressingly long list. FTSE 250 builders merchant Travis Perkins joined the list on Monday, warning that “it is evident that the UK is facing a recession”.
Of course, there may be an element of opportunism in this and other similar announcements. The pandemic will provide perfect cover for tough cost-cutting that might otherwise attract criticism. But I think it’s fair to conclude that many of the businesses which are starting to cut jobs do expect to face a slump in demand.
Safety in a storm?
Given this, where’s a safe place to invest? One option that comes to mind in the consumer sector is takeaway food - an affordable treat.
I’d expect Greggs and Domino’s Pizza to do relatively well in a recession. The stock I want to look at today also fits this mould. Cake Box Holdings (LON:CBOX) is a high street business that sells fresh, hand-decorated cakes. The business model is essentially very similar to Domino’s; Cake Box franchisees run stores and buy supplies from the parent company.
The SIF Folio already contains bakery and cake maker Finsbury Food. By rights I should exclude Cake Box on grounds of diversification. But whereas my new pick last week, K3 Capital, implies a more bullish view on the economy, I see affordable fresh cakes as a far more defensive choice.
Cake Box now qualifies for the relaxed version of my SIF stock screen. If the numbers impress me, I could be tempted to take a second slice of cake.
The story so far
Cake Box was founded in 2008 and floated on AIM in 2018. The group now has 133 franchised stores. Although this business doesn’t have a very long track record, it does have a few potentially attractive features:
Founder-managers own almost 52% of the stock
All stores are franchised, meaning that expansion capex is low for Cake Box
Franchise model generates very high returns on capital employed
All the founders are said to have run their own franchises before moving to the executive suite
As luck would have it, Cake Box published its full-year results for the 12 months to 31 March on Monday. You can read Paul’s comments on the business here. This timely news means that I have some fresh figures to look at, although at the time of writing they’ve not yet been loaded into Stockopedia.
Perhaps more important than last year’s accounts is an update on current trading. Cake Box has been reopening stores since May and says that 75% of shops are now trading at pre-COVID-19 levels.
That seems pretty encouraging to me, so let’s take a closer look at the numbers.
Value: priced for growth?
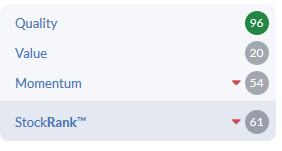
Cake Box has a ValueRank of 20 at the time of writing. This suggests the shares aren’t particularly cheap. More charitably, we might say they’re priced for growth. The FY20 results don’t change the picture all that much.
Revenue rose by 11% to £18.7m, while underlying operating profit dropped from £4m to £3.8m. Adjusted earnings fell 1.3% to 7.8p per share. These figures were slightly below consensus, but given the disruption to March trading caused by lockdown, I don’t think this is too much of a concern.
Encouragingly, online (click & collect) sales have risen by 60% since the end of March. The group is also now offering delivery, through Deliveroo, Just Eat and Uber Eats.
Free cash flow is a little hard to ascertain due to spending on new facilities and some property transactions. But my sums suggest underlying free cash flow (excluding expansion capex) rose from about £2.7m to £2.9m last year. Net cash remains positive, at £2.1m.
These figures give us the following valuation metrics:
Price/sales: 3.5x
Price/free cash flow: 22x
EV/EBITDA: 15.6x
Trailing price/earnings: 20x
It’s hard to see much value here. But if the company can deliver high-quality growth, this might still be okay.
Quality: attractive returns
For investors, one of the big attractions of a franchise model is that it’s capital light. Franchisees pay the parent company for the franchise and fund new stores themselves. As you’d hope, Cake Box scores much more highly for quality:
We can see that the group’s profitability has been excellent in recent years (although note that pre-2019 numbers are pro forma). I’ve added in FY20 numbers:
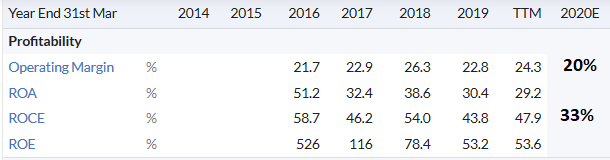
By way of contrast, Domino’s Pizza, a much larger franchised takeaway food business, generated an operating margin of 14% and ROCE of 31% last year. So Cake Box compares pretty well on these metrics.
Free cash flow conversion: I think that free cash flow conversion is good, but the picture has been clouded somewhat by property transactions and expansionary capex over the last couple of years. However, I’m encouraged by the group’s stable net cash balance and limited debt (a £1.6m mortgage on two food factories).
Inventories seem a bit high to me: Cake Box’s store count rose by 17% to 133 last year. But the group’s year-end inventory rose by 54% to £1.4m. Some of this may be due to the company opening two new manufacturing plants. But it still seems like a big increase to me.
My sums suggest that Cake Box holds about 42 days of stock in inventory. This compares to 20 days for Greggs and 14 days for Domino’s. I’m not quite sure why Cake Box might hold so much more.
I note that Cake Box qualifies for the Montier ‘Cooking the Books’ short-selling screen. I believe that the firm’s high inventories are one reason for this - high levels of stock can be a sign of channel stuffing.
I’m not suggesting any wrongdoing here, as the surplus inventory might relate to lockdown. But I think this is certainly a metric that’s worth watching.
Momentum: uncertain
A MomentumRank of 54 suggests an ambiguous outlook. To try and understand more about how the market is viewing Cake Box stock, let’s break down the stock’s momentum into its two composite parts.
Price momentum: Monday’s results didn’t move the share price, which remains flat on a year-on-year view. This leaves the stock well ahead of the wider market, giving us positive relative strength:
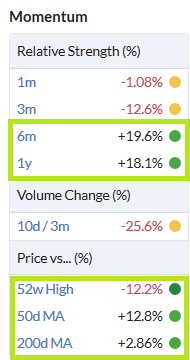
Given the circumstances, I would argue that the stock’s price momentum looks quite good at the moment.
Earnings estimates: Cake Box’s results missed forecasts, which will have a negative impact on its momentum score.
The company hasn’t provided any guidance for the current year. But broker forecasts on Stockopedia suggest earnings of 11.1p per share for FY21, which would represent a 42% increase from FY20. This would be impressive, but I’m reluctant to put much trust in this forecast at this time, given the lack of guidance from management.
My decision
I can see plenty of potential for Cake Box to grow into a highly-profitable franchise business. I’m also impressed by the rapid recovery in trading volumes. However, I’m puzzled by the group’s high inventories and I’m concerned about the uncertain outlook.
On balance, I’ve decided not to double down on cake. I’ll stick with Finsbury Food and continue to watch Cake Box with interest.
Disclosure: At the time of publication, Roland owned shares of Finsbury Food.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Is Cake Box Holdings (LON:CBOX) the next Patisserie Holdings (LON:CAKE)?
OMG!! Anyone have an idea what is going on with Cake Box Holdings (LON:CBOX) today? 23% drop on no news!
https://forum.quidisq.com/t/ca...
very honest report
Sales per locations were 140k in latest FY and 149k prior year, adding 20 new locations which is a 15% increase. Looking through their store list they really look quite saturated. One can also to an extent overlay locations on a map of average or median wages and see the target demographic. No one is buying a franchise where there is still a conventional baker. Combined with the somewhat esoteric product (are their family wars over whether to go flour free or egg free?) I just don't the case for sustained growth. It is also highly dependent on the skill of the franchisees navigating difficult economic circumstances.
When I was a teenager my family ordered Domino's Pizza (LON:DOM) at least once a week. I think cake is more of an occasional treat and can't rival the market size of delivered pizza.
When doing research I look to look at the company website - the cake box site is pretty awful in my view and it doesn't extend any confidence of quality - in fact it screams supermarket quality cake.. I don't mean to be negative but that's my tuppence worth!
It also seems that the Investor section of the website is sorely neglected. In the about Cake Box section it says
“The Group’s franchise estate has grown rapidly in recent years, from 19 stores as at 31 March 2013 to 91 franchise stores as at 13 June 2018”
I am assuming that Cake Box has had some expansion since 13/06/2018. It seems quite neglectful to have this page so out of date.
I suspect sensible decision not to go for this one and dare I mention £CAKE. Sadly I found myself agreeing with Luke Johnson in his Sunday Times article this week. However I still hold him responsible for the Patisserie Holdings (LON:CAKE) fiasco and investors like myself who watched the directors cash in share options on the back of fraudulent accounts would like to see them relieved of their ill gotten gains and given a prison sentence - though not much chance of that given the SFO record in prosecuting anyone successfully!
Cake Box Holdings (LON:CBOX) financially looks very nice with a growth opportunity. Equity Development did a presentation and had a note out yesterday.
Reports show 70% of shares held by directors / related parties and the fact that they themselves are franchisees. Also, CFO owns 30% of EggFree Cakes Ltd, but the group owns 100% - seems odd.
I asked about these matters at the presentation yesterday, which the analyst did not put to management. Treatment/Protection of minority shareholders was mentioned - apparently no need to worry because they don't need to raise any more capital, and if investors want to buy in any size, they have to buy from directors.
Not for me, at least for the time being, which I may well prove to regret.
I struggle a bit with seeing this as a stock that would do well in a recession. Greggs yes, affordable food on the go (assuming people are on the go and not hiding at home because of covid). Dominos possibly, take away pizza and a film is a cheap alternative to cinema/meal out. But if you're tight on cash would you splash out on a hand decorated cake? I admit I don't know the business or prices, so I am assuming that ready made cakes at a supermarket would come in cheaper.
I would maybe classify Cake Box as affordable luxury. Cakes are (were) cheaper than Patisserie Valerie. At about £15-£30 per cake, it doesn't break the bank for a celebration. Especially if that celebration now takes place at home, instead of dining out - so is a way for a family/group to save money.