SIF Folio: Is super stock Ocean Wilsons Holdings a hidden bargain?

Have we reached peak Brexit uncertainty? Let’s hope so. Regardless of the eventual outcome, it certainly feels like now could be a good time to add some overseas diversification to my rules-based SIF fund.
Happily, my SIF screen has come up trumps this week and delivered a new stock for me to consider. I reckon this company is comfortably removed from the UK economy and offers tempting value.
Ocean Wilsons Holdings (LON:OCN) is one of those interesting and historic businesses you come across on the stock market occasionally. This £400m business is a holding company which runs a portfolio of international investments and a maritime services company in Brazil.
At the heart of the enterprise is Wilson Sons Limited, a Brazilian company founded by two Scottish brothers in 1837.
Wilson Sons Limited started out in shipping and coal. It’s since diversified to become one of Brazil’s largest providers of marine, port and logistics services. The company’s interests include two container terminals, tugboat and offshore support vessels, shipbuilding, and agency services for ship owners.
Alongside this, Ocean Wilsons Holdings also runs what it describes as “a portfolio of international investments”. At the end of 2018, this portfolio was valued at $258m. Judging from this 2017 page on the company’s website, investments are in a mix of equity funds, hedge funds and private equity.
A quick look at the firm’s 2018 results suggests that this group trades at a 25% discount to its sum-of-the-parts valuation. There’s also a 5% dividend yield. Could this unusual company be a bargain buy for the SIF fund?
2018: a mixed year
2018 was not a vintage year for Ocean Wilsons Holdings. Although the container port business delivered a stable performance, towing and offshore operations suffered from soft conditions in the oil and gas industry. This resulted in an increase in cut-price competition.
The group’s investment portfolio suffered too, falling by about 6% as a result of weak global equity performance.
Ocean Wilsons’ headline figures for the year were mixed, with revenue down 7% to $460.2m and operating profit down 9.1% to $99.5m. However, some of this related to foreign exchange losses. And the group still managed an operating margin of 21.6%, versus 22.1% in 2017.
Interestingly, Wilsons Sons announced plans for a strategic review of its container terminal and logistics assets in July 2018. This caused a spike in the Ocean Wilsons share price, but has not yet resulted in any decisions.
No explanation was given for this review, but I wonder if one reason might be that the firm wants to share the cost of the continued expansion of these capital-intensive assets.
In any case, it’s worth noting that the 2018 results show a net asset value per share for Ocean Wilsons Holdings of £15.24. That’s a 25% discount to the last-seen share price of £11.40. However, I’d expect a business like this to trade at a discount. I see this as reassuring asset backing, rather than a reason to buy in itself.
A value buy?
Ocean Wilsons’ discount to book value isn’t reflected in the Stockopedia stats, which show a book value of $554m. I’m not sure why this is, as the latest balance sheet shows a net asset value of $777.7m, or roughly £595m.
Despite this, the stock scores well for value with one exception:
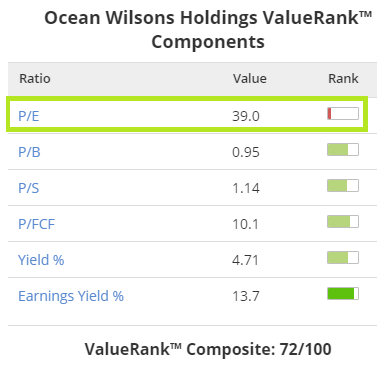
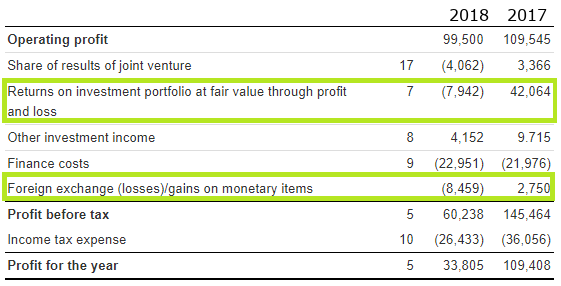
The elevated historic P/E of 39 reflects the fact that after-tax earnings fell by 69% to $33.8m last year. However, this fall isn’t as bad as it sounds.
As the screenshot below shows, the decline was mostly caused by movements in the fair value of the group’s investment portfolio. This had an adverse effect on statutory profit of about $50m. Foreign exchange costs were also significant, with a $11m adverse swing from last year:
Overall, I think Ocean Wilsons value metrics suggest that the stock offers good value. I’m particularly keen on the earnings yield (EBIT/EV) of 13% and the stock’s price/free cash flow ratio of 10, which confirms my impression that cash generation is good.
Quality: built to last?
Is this a quality business? Stockopedia’s algorithms seem to think so, awarding the stock a QualityRank of 82:
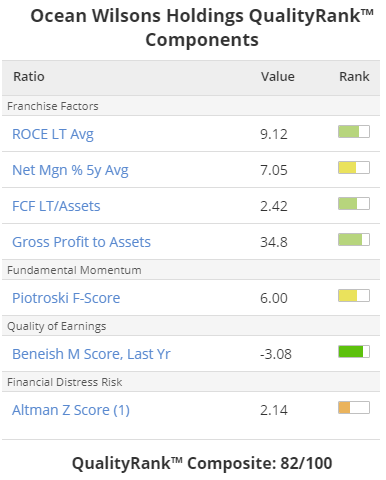
These are all fairly decent figures, although I wouldn’t describe any of them as outstanding. However, I think the group’s mix of investment assets and trading business might have something to do with this.
For example, the return on capital employed figure of 9.1% seems a little disappointing, given that the trading business reported an operating margin of 21% last year. But whereas operating profit only relates to the trading business, the ROCE figure includes all the group’s assets -- including a $258.9m investment portfolio.
If I strip the investment assets out of the balance sheet and recalculate ROCE, I get a return on capital of 12.3%, which seems more impressive.
This does suggest that Ocean Wilsons Holdings investment portfolio could be a drag on the group’s returns. I get the feeling that the firm’s management aren’t too bothered. They have a long-term outlook and are backed in this by major shareholders.
According to the Major Shareholders page of the website, about 52% of shares are owned by the Hansa Trust and two connected parties, non-executive director William Salomon and Victualia Limited Partnership. A further 11% are controlled by another non-exec. Hansa Trust has been invested in Ocean Wilsons since the 1950s and is famed for its long-term focus.
Overall, I’m quite comfortable with the quality of this business. A 182-year history and a strong body of supportive shareholders (including two non-execs) suggest this group is unlikely to make reckless or rushed decisions.
Momentum: limited info
Of course, the problem with investments of this kind is that they can sometimes struggle to deliver meaningful growth. For investors wanting to generate a reliable income and preserve their capital, this can be good news. But it’s not necessarily a winning formula if you’re looking for growth.
Although momentum isn’t the same as growth, the short-term focus of my SIF fund means that there is some overlap. So how does Ocean Wilsons score on momentum (and forecast growth)?
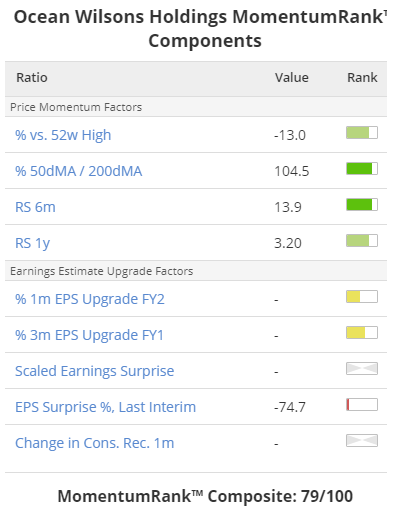
The stock’s MomentumRank suggests decent price action but very little in the way of broker support. Looking at Stockpedia’s broker forecast information, it seems that only one broker provides earnings forecasts for the stock.
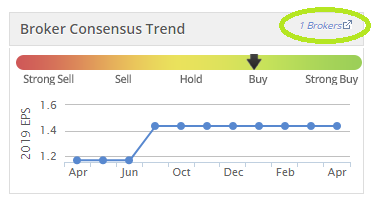
It’s hard to say how much growth this forecast equates to in terms of underlying earnings, as the company doesn’t provide an adjusted figure. But the broker trend seems fairly positive and suggests a reasonable forecast price/earnings ratio of about 10, with a prospective yield of almost 5%.
Ocean Wilsons stock trades on a standard LSE listing, rather than a premium listing. So it’s not a member of a FTSE index. Liquidity is also fairly poor for a £400m firm, with Stockopedia showing a spread of over 3%.
I’m not convinced this is an ideal candidate for a short-term strategy. But equally, I like the business. I see it as a fairly low risk choice that could generate a modest positive return. The shares also pass all of my SIF screening rules, so I’m going to add Ocean Wilsons Holdings to the SIF this week. I’ll also buy it for my own holdings after this article is published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Very interesting as I hold Ocean Wilsons via Hansa Investment Trust, a double discount. The problem is Brazil, it has natural resources, a young population and poor economic management.