SIF Folio: My UK fund lags the market in H1 + international update

We’re now more than half way through 2019, so now seems a good time to take a look at the performance of my rules-based SIF fund over the first half of the year.
I think that the results so far this year can best be described as mixed. Although the portfolio has risen by 7.2% over the last six months, the benchmark FTSE All Share index has gained more than 10%.
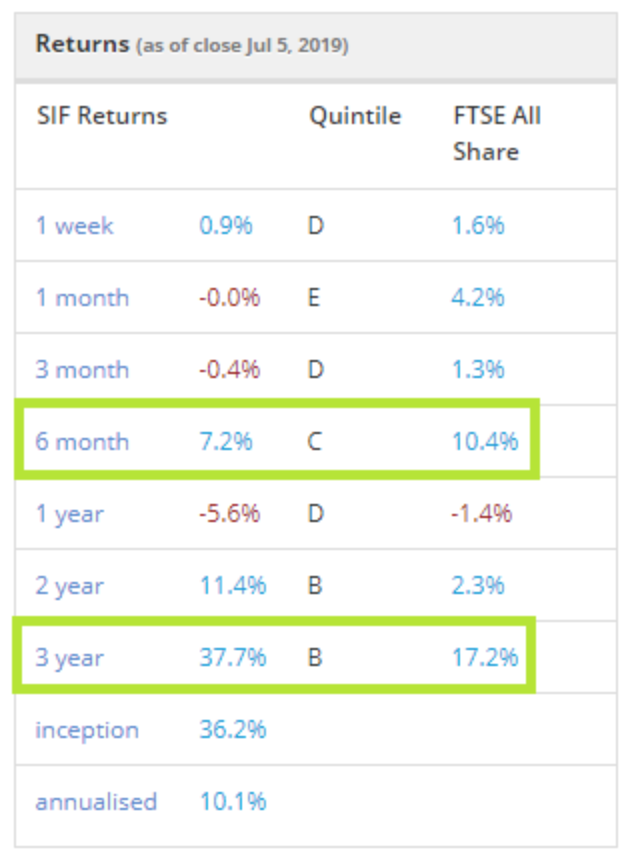
This means that the fund’s lead over the wider market has narrowed:
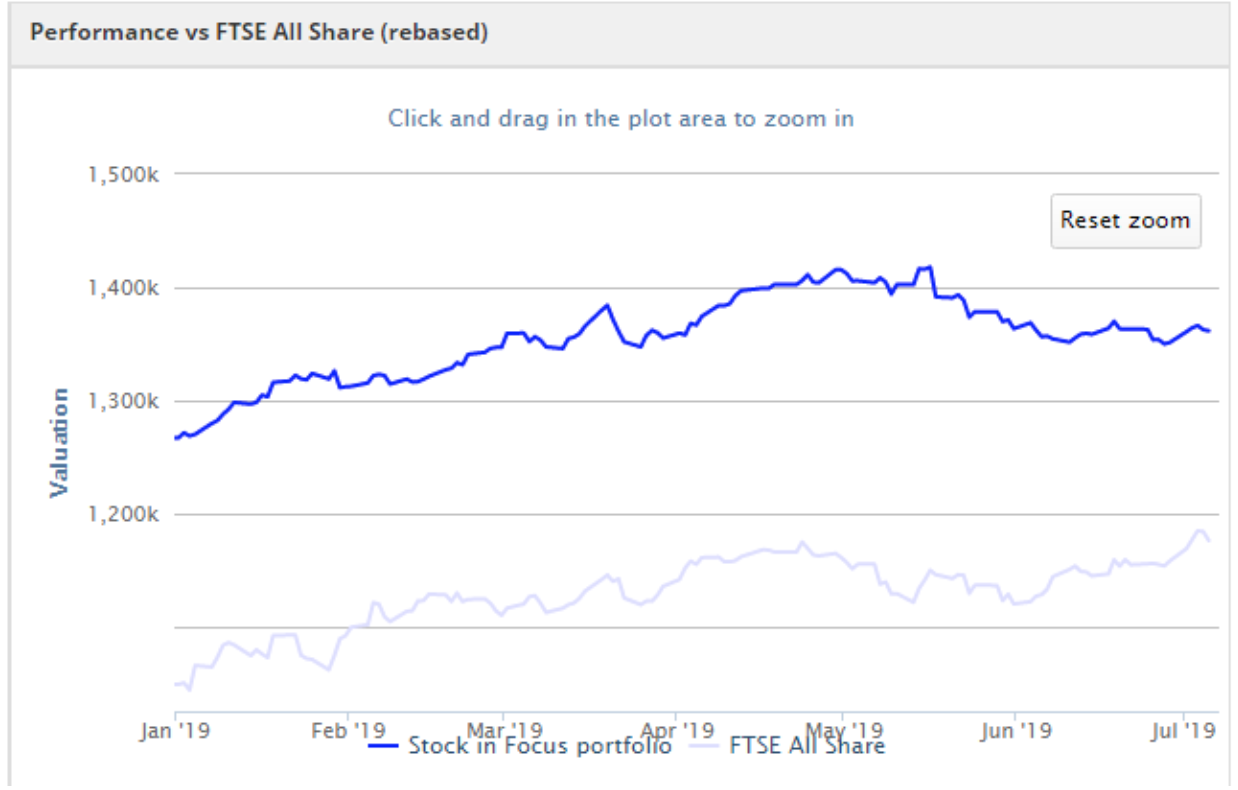
However, the picture remains fairly positive if we consider performance since the portfolio’s inception in April 2016:
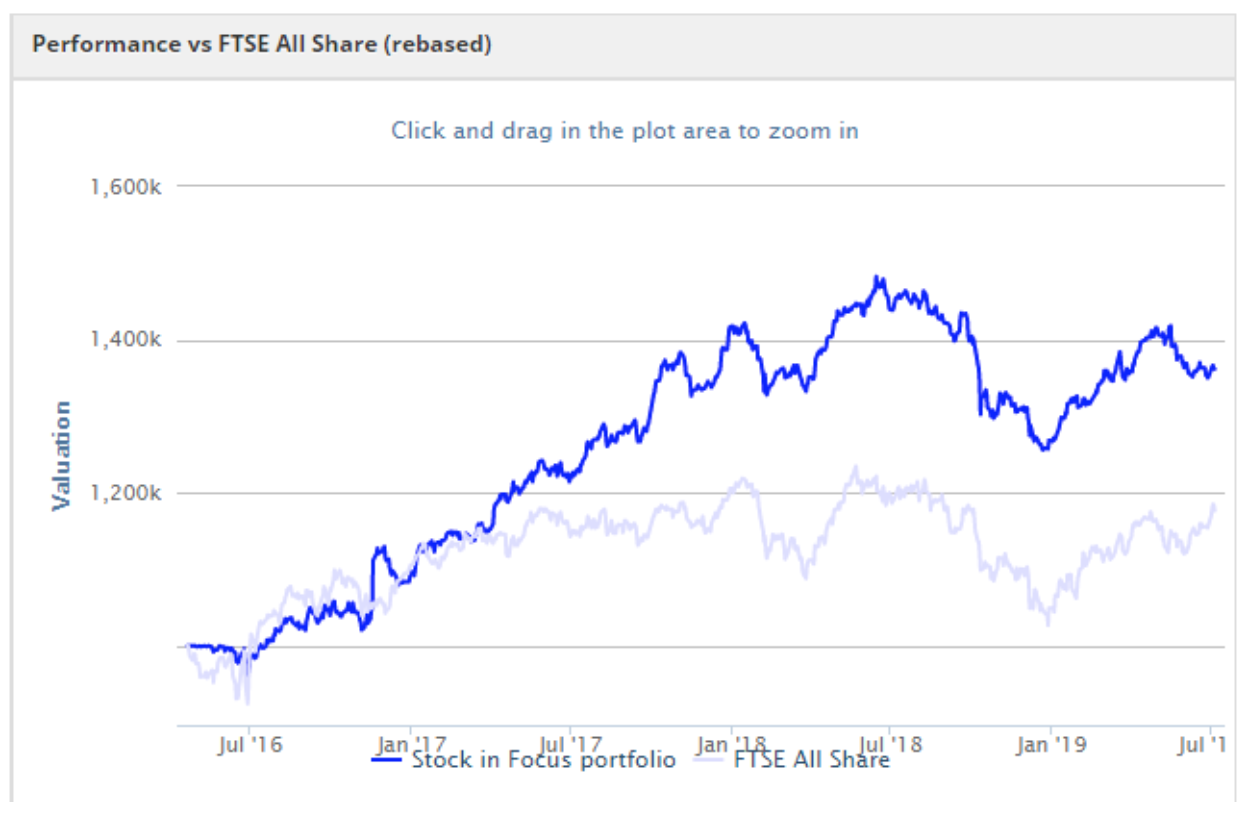
The story here seems to be that the portfolio outperformed from (approximately) January 2017 to July 2018. From July ‘18 to May ‘19 it broadly followed the market. And over the last couple of months, SIF has lagged the market.
This suggests to me that my rules work best in a bull market where strong stocks find good support. Given my short (nine month) holding periods and inclusion of momentum metrics, that’s not a surprise. However, it does mean that I could now face a longer period of underperformance.
As my Stockopedia colleague Jack Brumby explains in his latest piece, most strategies experience such periods of underperformance. They aren’t necessarily a reason to make changes, and I certainly have no intention of doing so.
As we head into an uncertain second half, I’m going to continue running the SIF fund as I have previously. I’ll revisit the fund’s performance at the start of 2020 to see how this plan has worked out.
New stocks this week?
My UK Stock in Focus (SIF) screen remains a desert, dominated by a handful of mining stocks. However, SIF already contains two mining stocks after last week’s addition of Capital Drilling (LON:CAPD). I won’t be adding any more stocks from this sector for the time being.
The only remaining stock in my screen results that I could consider adding is small-cap construction firm Renew Holdings.
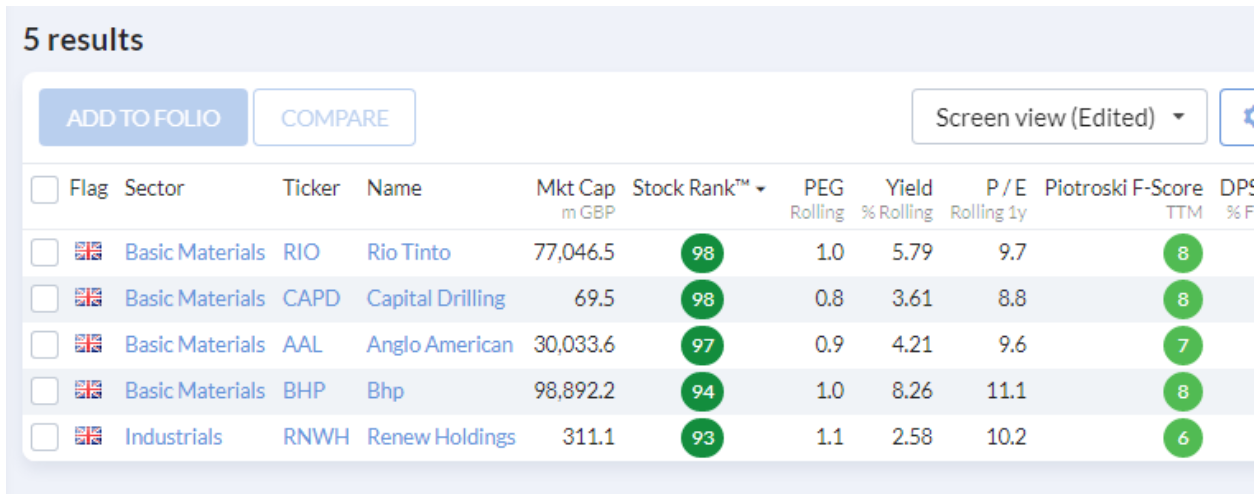
Although Renew passes my screening rules, I share Paul Scott’s view that the balance sheet may contain hidden risk and the price tag isn’t especially cheap. Given how many companies in this sector have faced difficulties -- most recently Kier -- I’m going to stay away.
Given all of this, this week seems like a good time for the monthly review of my International SIF portfolio.
Signs of hope?
As a reminder, this virtual portfolio is strictly experimental. I don’t own any of the stocks (unless otherwise stated) and am certainly not recommending any of them as purchases. For all sorts of practical and fundamental reasons, they may not be sensible buys.
Indeed, the performance of the portfolio has been pretty poor so far. As this chart shows, the International SIF has lost money in absolute terms and also lagged the wider market:
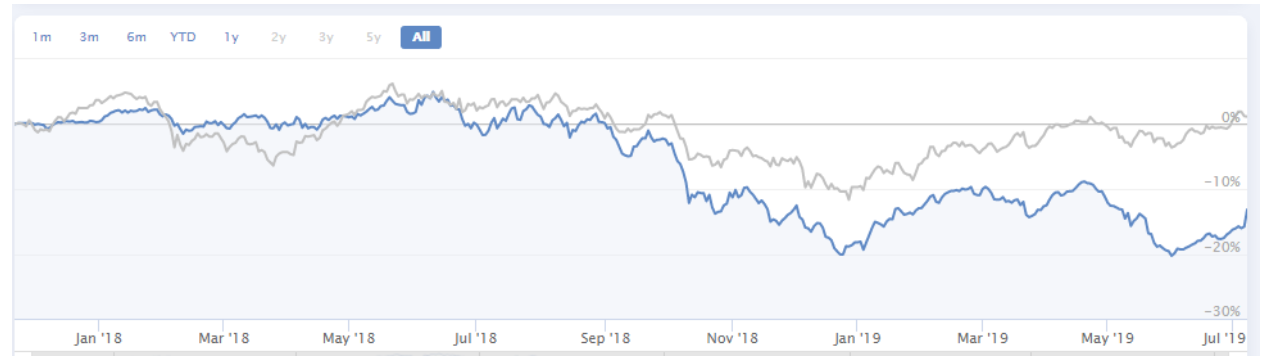
(Intl SIF is the blue line)
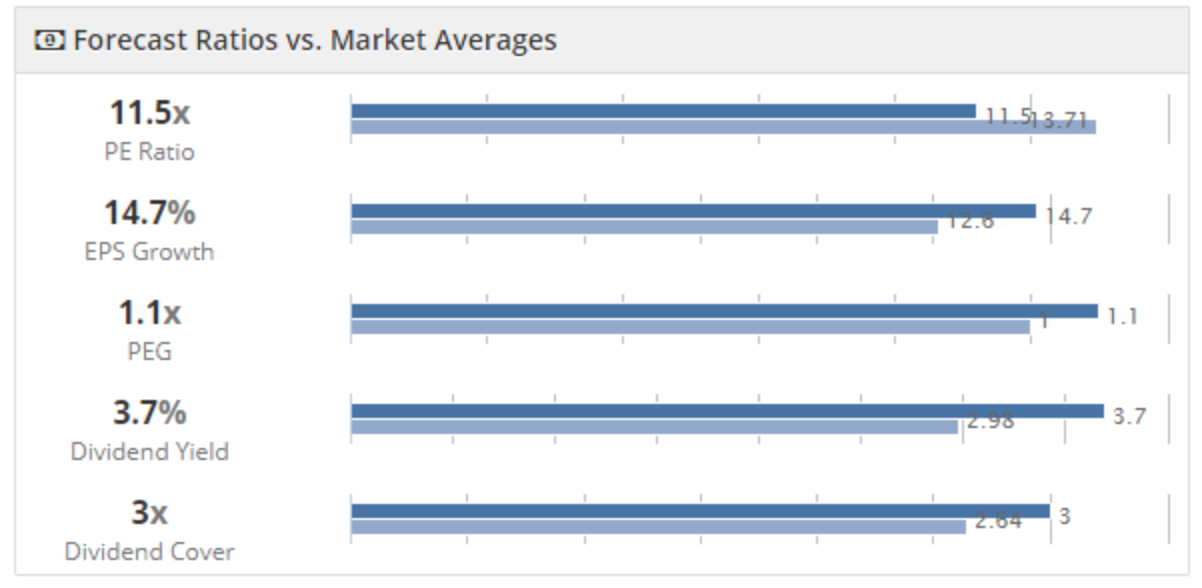
I haven’t given up hope just yet, in part because the aggregate characteristics of the portfolio still look very attractive to me (dark blue line):
I added some new stocks to the International SIF last month. That would normally mean that this month is a selling month, but for various reasons none of the stocks in the portfolio have been in it long enough to qualify for a possible sale.
This is something of a relief to me, to be honest. The portfolio currently has only 17 stocks, well below my target size of 20-24. So I’m going to use this month’s lull as an opportunity for another round of buying. Hopefully this will bring the folio closer to its target size and provide more opportunities for diversification.
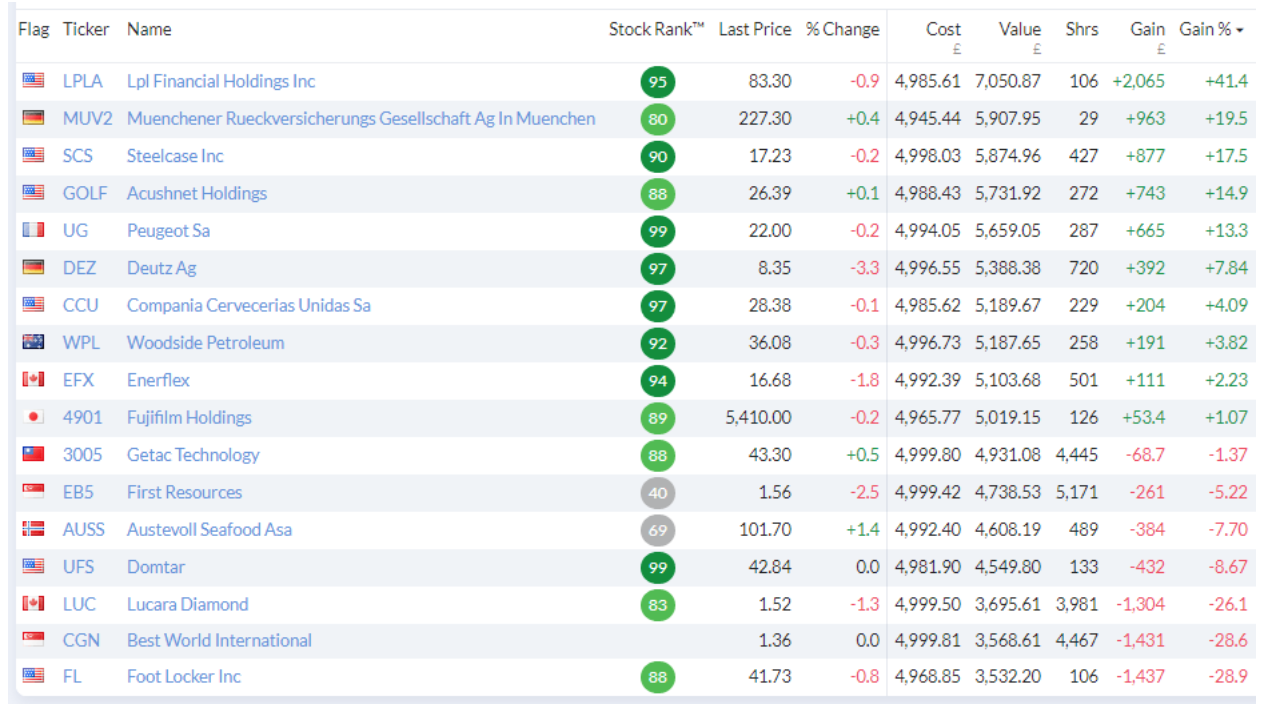
Before I start, here’s a snapshot of how the portfolio looked at the time of writing, before any changes:
This month’s new stocks
Happily, my international screen is still providing a diverse mix of stocks for me to choose from. As a result, I’ve been able to add three new stocks to the portfolio this month. This brings the stock count up to 20, within my target range.
These latest buys will also mean that the portfolio is fully invested, so further buys will be dependent on the sale value of existing holdings.
Let’s take a look at the new additions.
Discover Financial Services (NYQ:DFS)
This US firm offers banking services, credit cards and loans to consumers and SMEs. Its brands include the Diners Club charge card as well as a range of Discover-branded financial products.
Stockopedia likes the stock, awarding it a Conservative RiskRating and Super Stock StockRank Style. That’s a combination that has historically delivered above-average returns and below-average volatility.
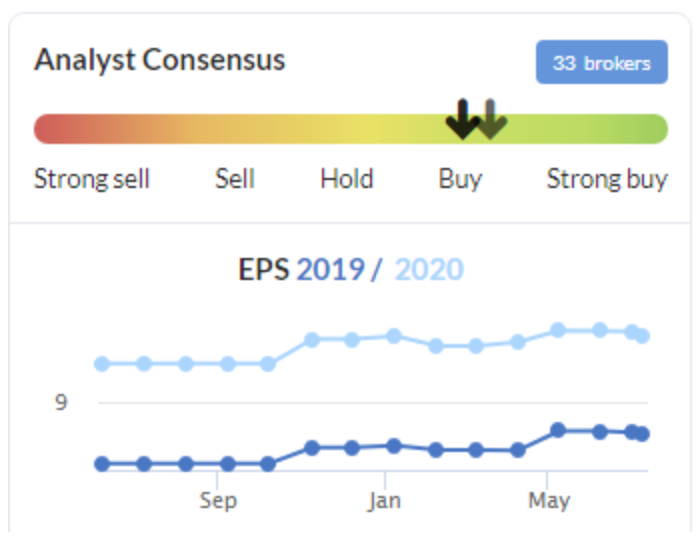
Return on equity has been above 20% since 2014 and the trend for analysts’ forecasts looks positive to me:
I guess that in the event of an economic slowdown, rising bad debts might put pressure on profits. But for now, the valuation seems reasonable, on about nine times forecast earnings.
Television Francaise 1 SA (EPA:TFI)
The name of this French firm is fairly self explanatory. It’s a television broadcaster whose operations include the TF1 family of channels and related studio businesses.
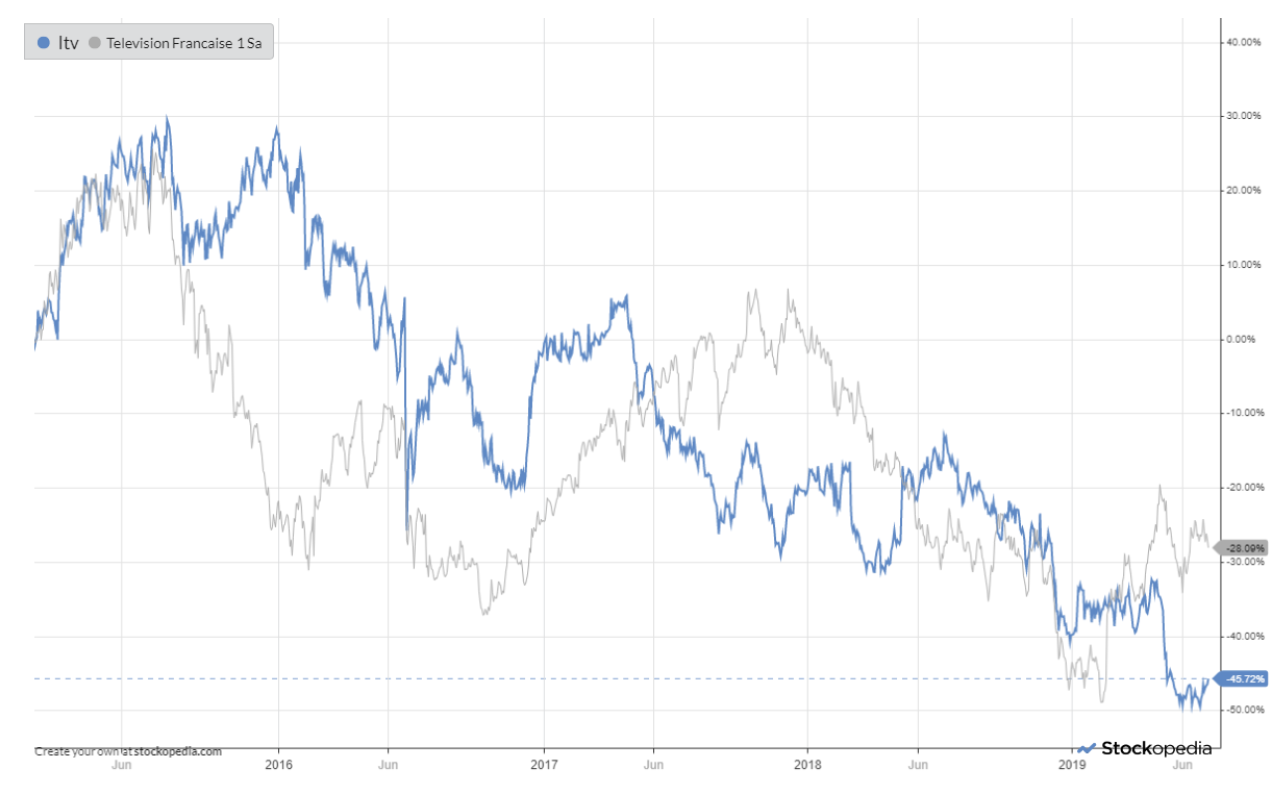
Like FTSE 100 firm ITV (in which I own shares), TF1 has seen its share price fall in recent years. However, continued profit growth has helped the group outperform its UK rival:
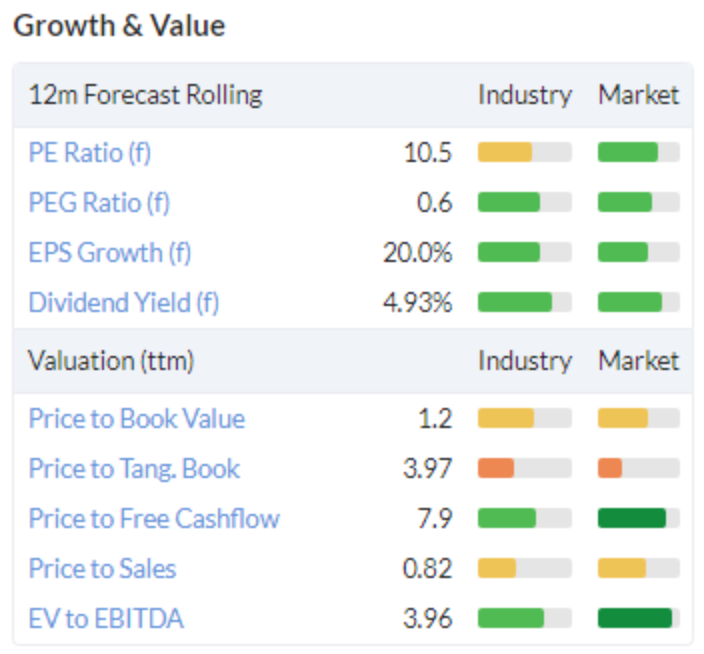
Brokers are fairly positive, forecasting continued profit growth in 2019 and 2020. Like ITV, TF1 generates plenty of free cash flow, only has modest debts, and offers an attractive dividend yield:
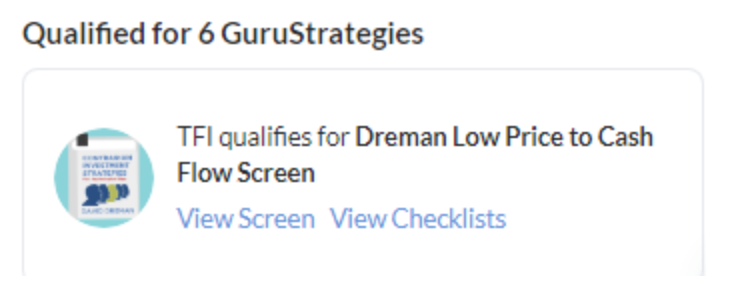
The Stocko computers like this stock too, awarding it a StockRank of 99 and a style of Super Stock. The stock also qualifies for no fewer than six Guru Screen strategies:
I welcome the extra European exposure, an area where the International SIF has been weak.
Mytilineos Holdings SA (ATH:MYTIL)
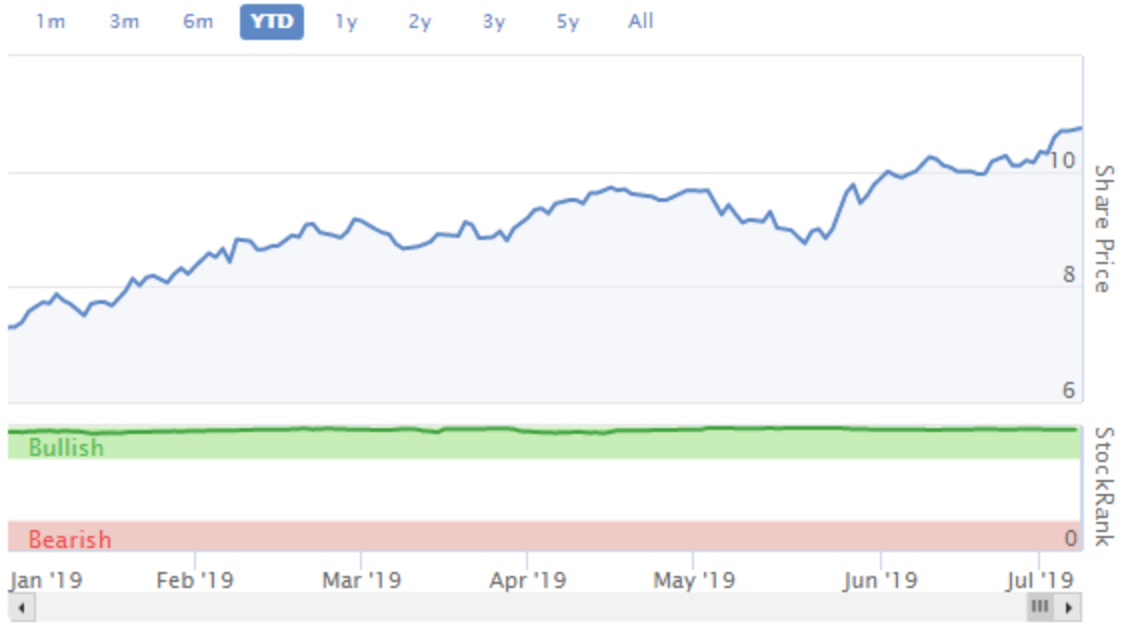
This Greek conglomerate operates in areas as diverse as aluminium, renewable energy and defence contracting. It’s been in the International SIF already, exiting in March 2019 with a disappointing 15% loss.
Given the share price gain since then, this is a case where I’d have done better to continue holding.
But will performance be any better second time round?
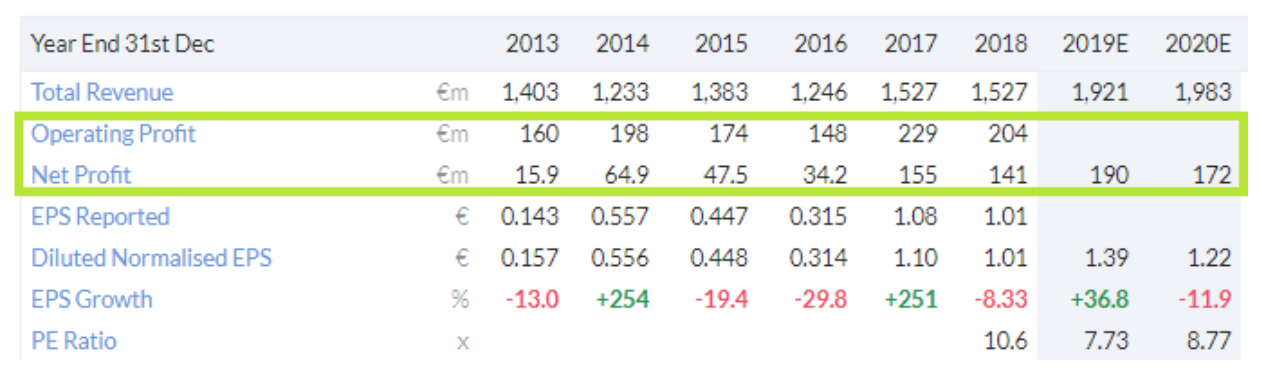
It’s hard to say. The shares have gained about 28% over the last year and earnings are expected to rise by about 36% this year. But reported profits have been inconsistent since 2013, although the trend has generally been upwards:
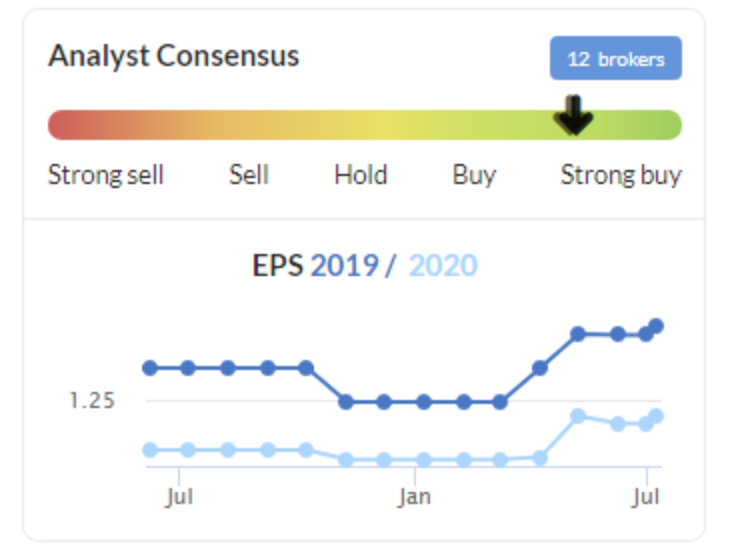
The broker consensus trend shows us that analysts have become more positive about the outlook for both 2019 and 2020 in recent months:
The balance sheet seems reasonable, with net debt down from €617m in 2016 to €390m at the end of last year. MYTIL shares trade on about eight times forecast earnings and offer a 4% yield. I’ve now added to this stock back into the International SIF, completing this month’s update.
Next week...
I’ll be focusing on the UK next week, hopefully with the addition of a new stock to the SIF fund. If nothing presents itself, then I’ll take a closer look at another interesting UK company.
Disclosure: At the time of publication, Roland owned shares in Capital Drilling and ITV.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Hi Carey,
Interesting point about Renew Holdings (LON:RNWH) and nuclear work. I'll have to take a closer look to understand more.
Regards,
Roland
I have to admit I kind of like Renew Holdings (LON:RNWH) . I take the point about the balance sheet but they do a lot of work in the Nuclear sector where the barriers to entry for competitors are huge, the revenues are good and projects last many years and so are predictable.
I feel its a slightly different beast to Kier (LON:KIE) . I'm not saying it wouldn't get hit in a downturn but I think it could be more stable than we give it credit for. You don't stop decommissioning a nuclear plant if the economy takes a downturn. Maybe its just a case of finding a good entry point to buy.
Apologies. It was not a 'thumbs down' and was meant to be a 'thumbs up'..... mouse movement at the point of clicking error. :-(
TT