SIF Folio: Persimmon's 8% dividend yield tempts me

UK housebuilders' have enjoyed a decade-long run of government subsidies and policy support aimed at propping up prices. Whenever there’s been any risk of the market grinding to a halt or - heaven forbid - prices falling, the government has pumped in some cash.
With no apparent irony, measures such as Help to Buy, the stamp duty holiday and now the Chancellor’s 95% mortgage guarantee are billed as helping affordability. As far as I can see, all they actually do is inflate prices and increase buyers’ ability to make highly-leveraged purchases.
From what I can see the main beneficiaries are the big housebuilders. Companies such as FTSE 100 group Persimmon (LON:PSN) have been able to generate a 30% return on capital in recent years. That seems exceptional to me, given the semi-commoditised nature of their products.
I covet the cash-backed 8% dividend yield available from stocks such as Persimmon. But I’m concerned about the unpredictable nature of government incentives and the wider risk of a housing market crash.
However, in my role as the virtual manager of the rules-based SIF fund, I’m not allowed to take subjective macro views on stocks. I must follow the numbers.
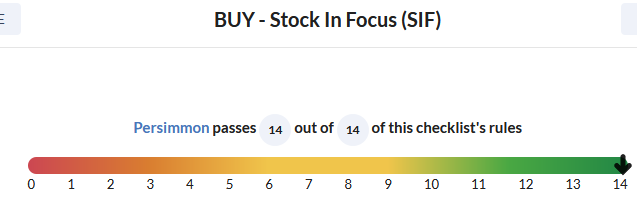
The numbers tell me that Persimmon passes all of my screening tests with flying colours.
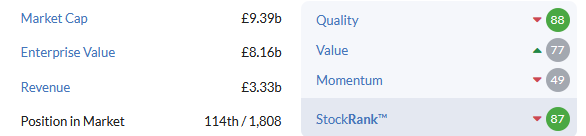
Stockopedia’s algorithms rank the the stock highly too, although with some possible weakness in momentum:
Should I add the stock to SIF this week? I’ve been taking a closer look at this housebuilder’s factor scores to understand more.
Value: profits vs assets
Persimmon’s ValueRank of 77 suggests the shares may be quite affordably valued. This seems to be true when the shares are valued relative to last year’s pandemic-hit earnings and dividend:
2020 P/E: 14.7
2020 dividend yield: 3.8%
Earnings yield (EBIT/EV): 9.6%
However, this is essentially a property company, so I think it’s important to look at asset-backed measures of value. Here the picture is more mixed.
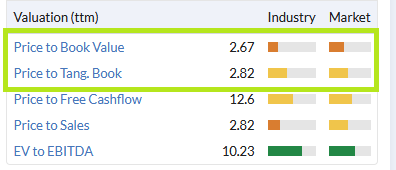
Net asset value per share was 1,102.7p at the end of 2020. With the shares trading at c2,900p,this gives the stock a price/book ratio of 2.7. This valuation may be justified by Persimmon’s high profit margins, but I can’t forget the cyclical risk here.
I would say the stock looks fully priced relative to assets, a view echoed by Stockopedia’s valuation graphic:
A discussion of Persimmon’s net asset value must include the group’s net cash, which stood at £1,234m at the end of 2020. This is enough to fund this year’s planned total dividend of 235p per share, independent of any free cash flow generated in 2021.
It’s also worth making a second point about Persimmon’s cash pile. The reported net cash figure doesn’t include land creditors (money owed on contracted land purchases). I view land creditors as equivalent to debt, so I prefer to subtract it from net cash.
Persimmon’s land creditor balance fell to £329m last year. So even after these obligations are deducted from the group’s cash balance, this year’s promised dividend of 235p per share is covered by surplus cash.
It’s worth noting that this isn’t true of all housebuilders. Some of Persimmon’s peers have net debt positions when their cash balances are adjusted for land creditors.
As far as I can see, this year’s forecast 8% dividend yield is safe and affordable. The only question is whether it will be sustainable in future years.
Quality: what’s not to like?
Persimmon’s strong cash generation and high profit margins support a QualityRank of 88.

Indeed, we might wonder why the stock’s QualityRank isn’t higher than 88. I think the clue to this lies in the Piotroski F-Score, which is only 6/9.

This fundamental health score measures profitability, cash generation and other important factors. It’s heavily weighted in the QualityRank calculation. Six is an acceptable score, but not outstanding. In Persimmon’s case, the reason for this middling score is that the F-Score tests are relative - they compare the trailing 12 months with the prior period.
The impact of the original lockdown meant that Persimmon was less profitable in 2020 than in 2019. So it fails a few tests. For example:

I’m not overly concerned by this. All the indications so far are that trading will recover strongly in 2021. Unless I start to see signs of failing momentum, Persimmon’s quality metrics don’t worry me at all.
Momentum: the weakest link?
Persimmon’s MomentumRank of 49 does not seem all that inspiring. To be honest, I’m a little surprised the figure is so low. MomentumRank is calculated by combining price momentum indicators (technical) with earnings estimates (fundamental).
Although I don’t know exactly how Stockopedia’s algorithms weigh these various factors, I’m struggling to see much weakness in either area.
Price momentum: Persimmon shares are trading close to 52-week and all-time highs. The stock has seen strong buying support recently and has outperformed the market over the last year. This information is conveniently displayed in the momentum graphic at the top of each StockReport:

Earnings estimates: It’s a similar story for earnings. Broker forecasts have been tweaked higher over the last one month and three months. Modest earnings growth is expected in 2022.
We can see all this (and more) from the consensus trend chart and the analyst forecast summary:


These forecasts price Persimmon shares on 12 times forecast earnings, with an 8% dividend yield. If house prices and transaction levels remain stable, then this doesn’t look too demanding to me.
My only concern is what might happen if macro or political conditions change. For example, what if we see a sharp rise in unemployment when furlough and other government support measures are finally withdrawn? At current levels, I don’t see Persimmon stock as offering much margin for error.
My decision
I don’t really want to buy Persimmon shares for SIF. But I accept that this is partly down to my own subjective views on the housing market.
To counter these, one bullish viewpoint that makes sense to me is that the housing market is also being supported by ultra-low mortgage rates and competitive lending. While funding remains readily available, there may be no reason for the market to slow.
Trade decision: According to my rules, Persimmon is a suitable purchase for SIF at this time. So I will add this FTSE 100 housebuilder to SIF and my personal holdings this week, with my fingers crossed.
As always, both the virtual and real-money trades will be executed after this article has been published.
Please feel free to share your views on the housing market. I’m aware that my own experience and opinions give me a significant bias when judging housebuilders. In this case, I’d be happy to be proved wrong!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
rock solid investment
I love Persimmon and have been lucky enough to be receiving dividends from them for some time. However, I agree that should there be changes political or otherwise that could be a problem as the stock is looking 'toppy' momentum wise. That could be said about many high yielding companies which is why I try to keep as far away from my own subjective opinion as possible and rely on what the current fundamentals and technicals are showing me.
I really struggle with the concept that the current dividend yield for Persimmon (LON:PSN) is sustainable. It has to pay out more or less all of its eps to provide that level of dividend and that is a huge drain. Surely it will have to come off that drug sooner rather than later, unless it decides to borrow to maintain an artificial dividend level? Moreover, the PBV is extremely high (much closer to 3 than 2), in contrast to the likes of Redrow (LON:RDW) and Bellway (LON:BWY). I find all of that rather scary.
Just compare the largest U.S. Builders with the U.K. ones and all are consistently 'cheaper'. USA markets are considered overvalued but it is not the case in this sector.
The market is in a type of bubble, but a long lasting one, not a pop and drop. There are genuine fundamentals that support the market (e.g. constrained land supply) but equally there are temporary and artifical factors (e.g. govt incentives). The affordability of the market has been going steadily down and down over the years. What cannot go on for ever must eventually stop.
The key issue here is interest rates. Property has exploded on the back of the long decline in interest rates since the early 80s. Long term yields collapsed from 16% to 0.2%. This has increased the apparant affordability of interest payments, as opposed to the true affordability of housing and has allowed people to take ever more leveraged bets. What cannot go on for ever must eventually stop and there are now signs that the tide is turning. Central banks are signposting a future in which we try to move higher in all 3 of: growth, inflation and interest rates. This should start to move us back towards historical norms of house prices to average incomes.
Personally I don't see any real danger to housing in the medium term. The govt will be desperate to support prices. Longer term though, it shouldn't be possible for bog standard housebuilders to return 30% on capital and so they wont be trading on 2.7 times book value. So, for me, short and medium term, housebuilders look good, long term not.
The govt supported UK housing bubble has to pop at some point, wages are not rising, young people entering the job market have poor prospects, hundreds of thousands of EU workers have gone home never to return, BTL rents are being slashed in London, the baby boomer ranks are withering. Rising US bond yields would mean the same for UK rates and there would be a tidal wave of repossessions.
Its propped up by:-
- Old(er) people owning and affording good quality houses.
- Old people living much longer than at anytime in world history.
- A punitative Stamp Duty tax than punishes moving or right-sizing.
- An archaic post medieval non plain English speaking legal system and entirely self serving unhelpful law society. *
* FFS - I've spent over 3 months just on the antiquated legal process of selling a simple bog standard house. I've had to pay 3 sets of lawyers to remove 8 toxic words of legal waffle.
Round'em up and shoot'em. They do nothing for civilization. (Joking... or am I)
It needs reform, of which there is no sign of a competent Government capable of such re-legislation.
What are these eight toxic words of which you speak (twice)?
Section 121 of the 1925 Property Act...
The landlord management company has the right to seize the property without notice if the rent charge is outstanding after 40 days.
Legal bullshit.
I challenged this when I bought 8 years ago and my incompetent Solicitor dismissed my challenge, only for my buyer's Solicitor to block my sale 8 years later.
Arseholes!
I may make a Malpractice complaint...
Those are huge generalisations. The same could easily have been said after the Brexit vote and a crash hasn’t happened. But if we are going to make generalisations, it should also be taken into account that there are a large number of people inheriting properties of high value from their parents now and that supports people getting on the property ladder later in life. Additionally, supply of all housing remains constrained by planning laws. Then there are other demographic trends like more people living on their own too. Steps have already been taken to dampen down the BTL market with increased stamp duty on second homes and changes to what costs can be deducted from rental income and that hasn’t collapsed the market.
The market isn’t in a bubble. Prices have not shot up rapidly in the last two or three years like they have for some other assets. Much more likely that house prices go sideways as affordablility restricts growth for a while than prices crashing. London prices may come down as more people reject commuting into the centre for work. But Persimmon are not particularly focused on London.
Persimmon (LON:PSN) have been making quite a lot of effort to improve their build quality and change their culture that was causing them to rush completions through before the houses were ready. But there’s probably still plenty of shoddy workmanship in the pipeline from sites started before this initiative. They have also made a commitment to sort out any cladding issues on high rise blocks and made a provision for that (looks like their exposure is fairly modest). So, I think they are going in the right direction regarding improving quality and reputation.
They have been highly profitable in recent times. I’m not sure to what extent this was dependent on buying up development plots while they were cheap in the aftermath of the GFC, but if that effect is still there it has to dwindle sometime.
I don’t see the housing market crashing anytime soon. The forecasts of disaster last year never came to fruition because the government took measures to stimulate the market and there was pent up demand for house moves but limited supply. The same seems to be continuing.
I continue to hold as I think results are going to improve as the initial slowdown from sorting out the quality issues works it’s way through and the number of completions starts to climb again.
I hold Redrow (LON:RDW) which I believe offers some great growth potential (with the risks highlighted above) and potentially scores better on a number of measures. What made you look at Persimmon (LON:PSN) over some of the others mentioned below?
Hi KevinS1,
In this portfolio the stocks I select to buy are all drawn from my stock screening results:
https://www.stockopedia.com/sc...
Redrow (LON:RDW) does not currently pass all of my screening tests. For example, the stock has (slightly) underperformed the market over the last year according to Stocko data, resulting in negative relative strength.
Hope this helps,
Roland
Yet Redrow (LON:RDW) has much higher Momentum score of 91 v 55 and SR is 98 v 90, QR is also higher. Persimmon (LON:PSN) dividend is higher though.
I see Alumasc (LON:ALU) is also on your screen, any reason why that has not been considered?
Bellway does not have any nda's according to Money Box enquiries.
I think there's better value in some of the slightly smaller housebuilders, such as Bellway (LON:BWY) and especially Vistry (LON:VTY) the latter trading on a single digit PE and closer to book value.
Money Box highlighted that PSN was a housebuilder did not respond to the BBC re enquiries : gagging orders on new build. They will have to set money aside to cope with any legality which seems will ensue sooner or later. Sold today.
agreed
The industry has some serious quality issues, Grenfell and the Cladding disaster being the worst.
My neighbour's new build of 8 years old has support columns holding up the front of his house. No, not the marble neo-corinthian sort but screw jacks.
I've just nearly completed a 3 month legal drama costing me £1500 (luckily) because Barratt planted 8 unlawful and toxic words in my Deeds making my house unmortgageable.
The Builders collectively have tucked up a lot of people and can probably be considered borderline predatory.
At some point, either after the next tragic disaster (fire or collapse) or when The Con-socialists cock up the next General Election, the otherside will rightly want some payback and culpability.
I hold Persimmon for the medium term but worry (1) that net migration of a million out of the UK must dampen demand and (2) a flood of vacant commercial land will be repurposed for housing... a decrease in demand and an increase in supply points only one way