SIF Folio: Robert Walters could profit from Asian recovery

It looks like parts of the UK could face regional lockdowns in the coming days and weeks. Other European countries are also suffering a second wave of coronavirus - in some cases more severe than the first time round.
Against this backdrop, I’d imagine that it takes a certain confidence to reinstate dividend payments and restore staff to full working hours. These measures were announced by recruitment group Robert Walter (LON: RWA) last week, when it reported an improved third-quarter performance and a net cash balance equivalent to 46% of its market cap.
Recruitment is a notoriously cyclical business and most decent listed firms operate with plenty of cash. But the tone of the group’s third-quarter update did seem encouraging to me. I’m also attracted to the group’s sizable exposure to the Asia Pacific region, which has historically provided around 40% of net fee income.
Asia was hit first by coronavirus and I’m pretty sure it will be the first region to recover. Walters’ commentary supports this view, noting “early signs of improvement particularly across our Asia Pacific business”.
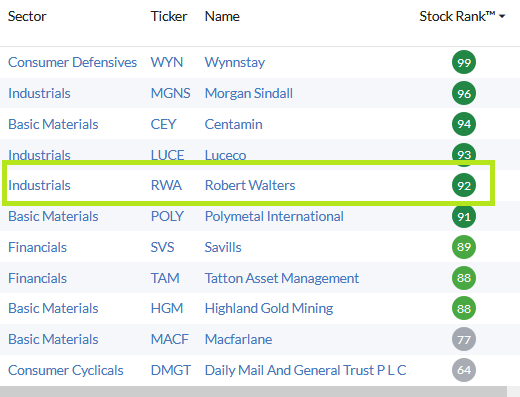
I haven’t been able to add a stock to my rules-based SIF Folio for four weeks. This allows me to consider stocks from my relaxed screening results, which you can see here. This screen takes a slightly more lenient view on valuation and growth to broaden the opportunity set for the portfolio.
With a StockRank of 92, Robert Walters comes close to the top of my relaxed screen’s results and doesn’t hit any diversification issues. I’m attracted to the idea that the company could provide UK investors with early exposure to an Asian recovery. This week I’m going to take a closer look at these shares as a potential buy.
Cash-backed value
Recruitment stocks tend to look cheap and be cash generative, and Robert Walters is no exception:
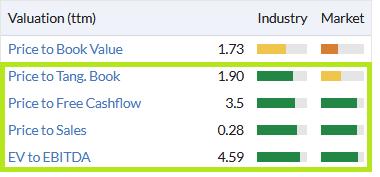
It’s worth noting that the company’s book value is bolstered by a lot of cash. The half-year balance sheet showed cash and equivalents of £133.4m, offset by just £14.4m of borrowing. Although the statutory net debt figure of £46.8m includes £72m of lease liabilities, I don’t see these as a concern given that the group remains profitable and cash generative.
Robert Walters also scores highly on another key metric which forms part of the ValueRank calculation and which I use heavily:
Earnings yield (EBIT/EV): 12.9%
For context, the minimum earnings yield accepted by my regular screening rules is 8%.
As you’d expect, Robert Walters scores less well on measures which reflect the earnings slump seen during the first half of the year:
Trailing 12-month P/E: 13.8 (H1 earnings fell by 82%)
Dividend yield: 1.1% (the 2019 planned final dividend was cancelled in April)
I’m not too concerned by these ratios, especially as the company has just reinstated its interim dividend unchanged from 2019. That’s relatively unusual this year. Although a number of companies have reinstated dividend payments, far fewer have maintained last year’s payout levels.
It’s a little hard to judge value at the moment, given the extreme uncertainty facing the wider economy. But I feel confident that Robert Walters’ balance sheet is strong enough to cope with most plausible scenarios. I also believe that based on current information, the stock looks fairly valued.
Overall, I’ve no concerns here. This business has plenty of cash and - as we’ll see - attractive quality metrics. These could support a strong recovery.
Quality metrics reassure
A QualityRank of 99 suggests a healthy and profitable business. The StockReport certainly highlights some attractive metrics:
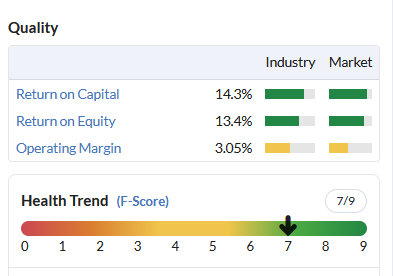
Although the return on capital figure of 14% is reasonably attractive, falling profits this year mean that it’s well below the group’s normal level of recent years:
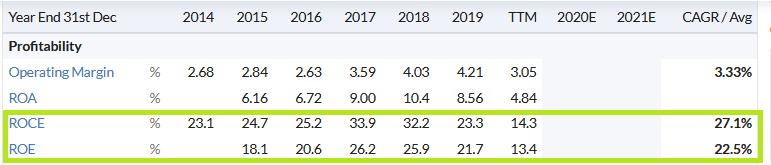
The company has taken steps to preserve cash this year. Operating costs fell by around 15% during the first half. This was mainly due to a big reduction in headcount, which has fallen from 4,258 to 3,240 since the end of September 2019 -- a reduction of 25%. This is typical for a recruiter, where the vast majority of costs are for staffing -- fewer ‘fee earners’ (recruitment consultants) are needed in a downturn.
As with Robert Walters’ value score, I think the quality metrics stack up very well. Naturally, this verdict comes with the caveat that if we suffer a global recession that’s longer or deeper than expected, the firm’s performance could get much worse.
Momentum: early signs of stability?
Fittingly for a firm with sound fundamentals but an uncertain outlook, Stocko’s algorithms award Robert Walters a MomentumRank of 51. As usual, I’ll divide this section into two parts, covering price and earnings momentum.
Price momentum: The short-term technical indicators aren’t that great:
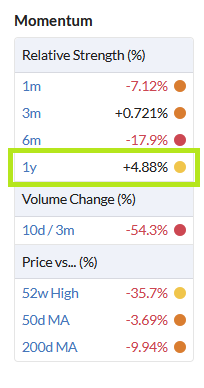
One potential highlight is Robert Walters’ one-year relative strength, which is positive. This is a metric that’s used in my stock screen and indicates that the stock has outperformed the wider market over the last year. Statistically, one-year relative strength is generally seen as a positive indicator for the next 6-24 months. So there’s some hope here.
I’m also cautiously encouraged by the stock’s long-term chart, which suggests a strong uptrend over the last 17 years. Buyers who’ve bought near the black line have generally done well over the following 12-18 months:
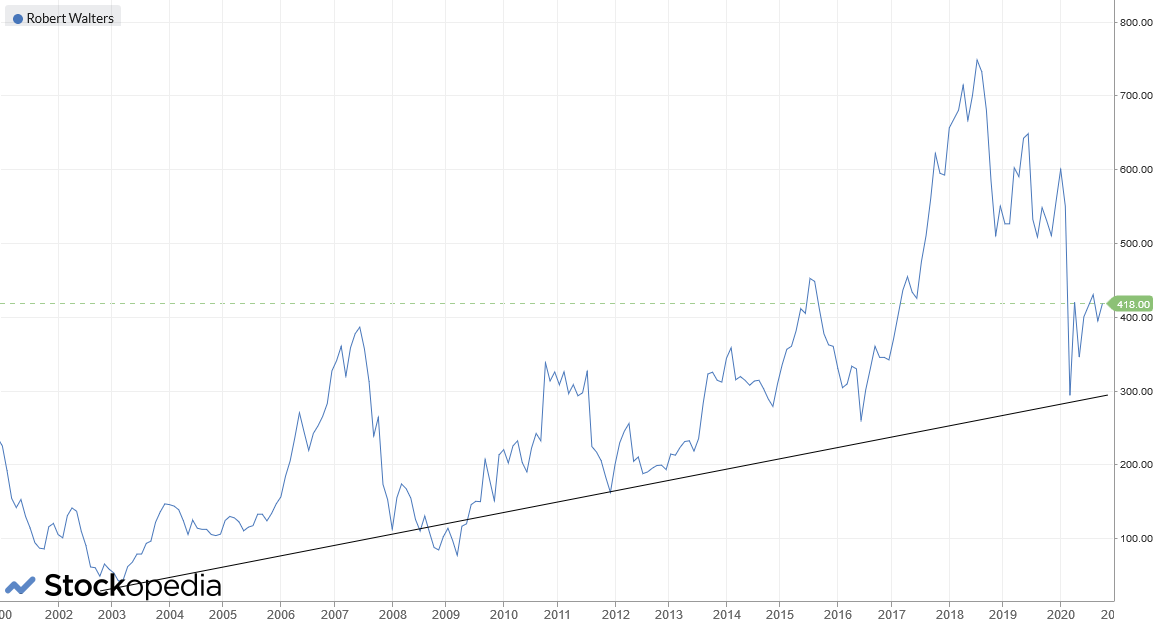
Past performance is no guarantee, but I see this as a positive indicator.
Price momentum: Earnings aren’t expected to return to 2019 levels anytime soon. Forecasts for 2021 show profits on a level with 2016. But the outlook does seem to have stabilised in recent months. Broker sentiment also seems to be improving (as shown by the black arrow being to the right of the grey arrow):
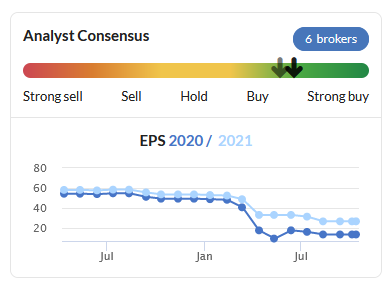
In the firm’s third-quarter update last week, CEO Robert Walters said that he expected full-year results to be in line with current market consensus. Based on Stockopedia data, that puts the stock on a forecast P/E of 29 for 2020.
Although that seems expensive, cyclical stocks traditionally look pricey at the bottom of the cycle. A forecast P/E of 14 for next year looks more reasonable. I’d also note that the valuation is supported by a cash-backed 3.2% dividend yield.
My decision
There are obviously lots of things that could go wrong here. But that’s true of many businesses right now. I don’t think it’s a good enough reason to rule out investing in companies with sound balance sheets and solid track records.
Robert Walters ticks both of these boxes for me. The company has historically enjoyed strong profitability and entered the pandemic period with a very strong balance sheet. I expect the business to benefit from its heavy exposure to Asia markets, which I’m fairly sure will recover ahead of Europe and perhaps the US.
I’ve decided to add Robert Walters to the SIF Folio and my personal holdings this week. As always, I’ll make the trades after this article has been published.
Let me know what you think - is it too soon for cyclical recovery plays, or are you backing up the truck?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
I think S THREE is also worth consideration. A STEM recruitment company. Beats RW on a Stocko comparison. Cash of £39m. Not as big in Asia but expanding in that area.
Great post, interesting perspective Roland, thank you for taking the time and effort to post.
I am also holding Robert Walters (LON:RWA), just for the sake of transparency, if any is needed here - this is my first post on Stockopedia, I only joined 10 days ago and am therefore a little uncertain of protocol.
Having spent 24 years in recruitment and having survived two or three "Slight Market Movements" the only point I would like to add is that recruitment is often one of the very first industries to feel a downturn as clients start to batten down the hatches. It is also however one of the very first to recover due to the uncertainty of any recovery leading to clients being unsure about recruiting staff permanently. RWA is involved in the contract hire sector of the industry and, sad as it is, their clients, having laid off staff in these difficult times, will not want to hire permanent staff at first and will more than likely go through a temporary solution to permanent employment model until a greater degree of certainty about the recovery is visible.
RWA will benefit from this recovery strategy in two ways. They will pick up the temporary or contract work and they will then pick up the fee based work off the back of that as economies get stronger again.
It is interesting to read of their involvement in Asia.
Re: Cyclical recoveries, see how the next couple of weeks pans out in the U.S, lets hope for a Biden win - less entertaining I know, but it would be good to have some predictabiility back in the markets.
Thanks once again for your post, kindest regards, TW.
very interesting! Quite a jump today My eldest daughter has just started with a recruitment agency and settled in very well ( made redundant by car phone when managing etc) I intend to watch this area with a great deal of interest especially the Asia part