SIF Folio: Should I buy City of London Investment Group? (& WIN)

My SIF stock screen continues to deliver results that are heavily weighted towards the UK housebuilding and construction sector. In more than five years running this model portfolio, I don’t think I’ve ever seen such a concentrated set of results.
At the time of writing, nine of the 15 stocks which qualify for the screen are involved in construction or supplying building materials to the UK domestic market:
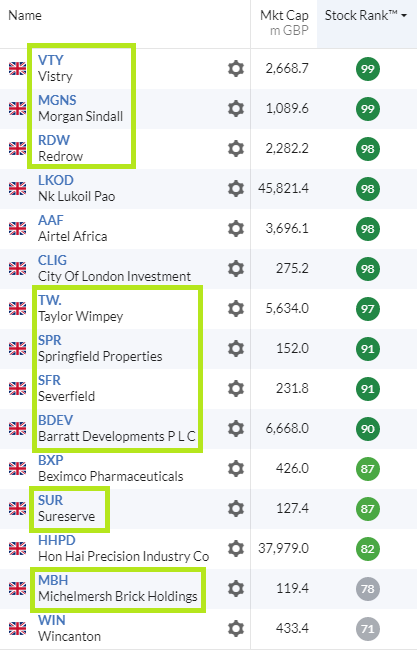
As SIF already owns shares in Persimmon (LON:PSN), I don’t intend to add any of these other stocks to the portfolio at this time. But this unusual concentration of stocks does make me wonder about the outlook for this sector. Right now, many construction-related shares look cheap and appear to have rosy outlooks. Will this still be true in 6-12 months? I’m not entirely convinced.
As always, I’m looking for new stocks to add to SIF. Excluding the nine construction-related stocks I’ve highlighted above leaves me with six potential candidates.
Two of these are foreign firms and two - Airtel Africa (LON:AAF) and Beximco Pharmaceuticals (LON:BXP) - are already in SIF. This leaves me with two remaining candidates, logistics group Wincanton (LON:WIN) and small cap fund manager City of London Investment (LON:CLIG) (I hold).
Wincanton (LON:WIN): big faller
I looked at Wincanton in August and concluded that the wafer-thin balance sheet did not truly satisfy my screening rules. I also highlighted the group’s slim profit margins and ongoing pension deficit recovery payments. Although I think that Wincanton is a market-leading business in operational terms, as an investment it’s a stock I’d only buy at a low valuation.
As it happens, Wincanton’s share price has fallen by nearly 20% since I wrote about the stock in August. This has brought the stock’s rolling forward P/E multiple down from 11.6 to 9.3. The rolling forecast dividend yield has risen from 2.8% to 3.5%.
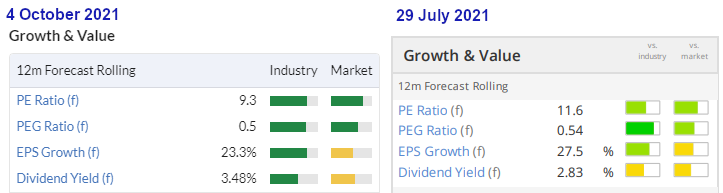
If this de-rating continues I might be tempted to take a look at this stock. Although the logistics sector is facing well-known problems with driver shortages and rising costs, Wincanton said in September that 70% of its revenue is open book, with costs passed through to customers. A further trading update has been promised for “early October”. I await this with interest and may return to Wincanton over the coming weeks.
City of London Investment (LON:CLIG): the right time?
In the meantime, I want to look at emerging market asset manager City of London Investment Group. Purely by chance, I recently bought this stock for my main personal portfolio. However, it’s not currently a SIF holding.
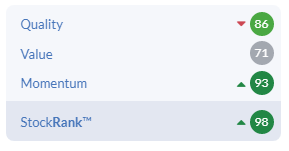
CLIG’s attractions for me included a high, well-covered dividend yield, strong profitability, and hopes of a return to growth after a recent merger. Stockopedia’s algorithms seem to like CLIG too. The stock is classified as a Super Stock and boasts high factor scores:
CLIG has a market cap of £275m and had £8.3bn of funds under management (FUM) at the end of June. Historically, CLIG’s main focus has been the niche area of emerging market investment trusts. The company has a value-oriented approach which involves buying investment trusts at a discount to their fair value.
This strategy appears to have delivered decent investment results. In its latest accounts, the company said that more than 95% of assets under management had outperformed their benchmarks over the five years to June 2021.
Despite this success, growth has been slow in recent years:
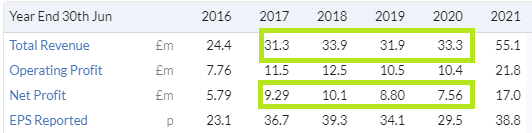
In an effort to address this sluggish performance, CLIG merged with US investment trust specialist Karpus last year. The combined group now offers a broader mix of fund types and a more diverse client base, including both institutions and high net worth individuals.
However, despite the general enthusiasm for equity markets last year, the enlarged group’s funds saw net outflows of almost $800m last year. This affected both Karpus funds and those run by City of London:
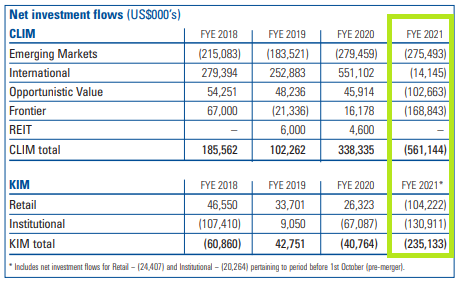
Source: City of London Investment Group FY21 annual report.
I suspect this lacklustre performance is the main reason why CLIG has been a perennial value stock in recent years, despite generating high returns on equity.
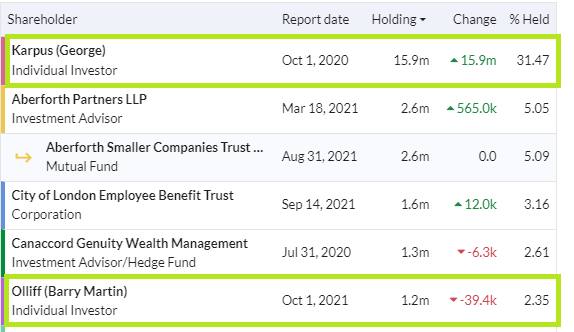
Insider ownership: Until quite recently, CLIG was led by founder Barry Olliff. However, Mr Olliff has gradually reduced his holding in recent years, and stepped down to a non-exec role following the Karpus merger. I understand that Olliff plans to retire altogether later this year.
Karpus founder George Karpus is now CLIG’s largest shareholder, with a 31.5% stake. My hope is that his presence on the board will ensure that CLIG continues to be run with a founder’s mentality.
With that introduction, let’s drill down into City of London’s financial metrics with a look at the stock’s factor scores.
Value: pretty decent
Despite describing CLIG as a perennial value share earlier, this stock’s ValueRank of 71 is actually its lowest factor score. I suspect the reason for this is that the shares trade at a hefty premium to their book value. This is partly because of the group’s strong profitability:
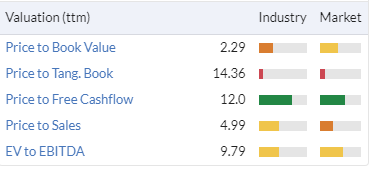
Looking elsewhere for value, the picture improves. CLIG’s price/free cash flow ratio if 12 is quite modest in my view. I think that CLIG’s earnings yield of 8.6% also suggests a potentially attractive valuation.
The shares also look reasonably priced on other standard measures, with a trailing P/E of 13 and a historic dividend yield of 6.1%. Net cash at the end of June was ample, at £22.8m.
One caveat to this favourable portrayal is that last year’s results coincided with unusual market conditions. The year to 30 June also included the first nine months’ contribution from Karpus.
We don’t yet know how the enlarged CLIG business will perform during a downturn or more generally in the future. But given the group’s consistent track record and Mr Karpus’s ongoing involvement as a non-exec, I’m not too concerned about this.
On balance, I think that City of London is quite reasonably valued at current levels.
Quality: high
Lots of asset managers have struggled to grow in recent years. But very few of them can boast a QualityRank of 86 and such impressive profitability metrics:
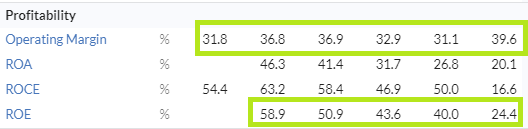
Balance sheet: One point worth mentioning above is the sudden fall in return on equity (and ROCE) last year. This doesn’t indicate a dramatic collapse in profitability. Instead, it’s due to the recognition of £41.6m of intangible assets and £69.7m of goodwill following the Karpus merger. These additions increased CLIG’s equity value from £19.1m to £120.3m last year. This explains the reduction in return on equity.
Using the alternative measure of return on tangible equity, which excludes intangibles and goodwill, CLIG’s returns rose from 39% to 88% last year. This reflects a 66% increase in fee income due to higher funds under management, thanks to market movements and the Karpus merger. The group’s average fee margin remained largely unchanged, falling from 0.75% to 0.74%.
Broker consensus forecasts on Stockopedia suggest that we can expect similar levels of revenue and profitability in the future.
Cash flow: I’ve already mentioned CLIG’s strong cash generation. A quick calculation suggests that the company has converted 114% of its earnings to free cash flow since 2016, based on Stockopedia data. This is a very good result by any standards, in my view.
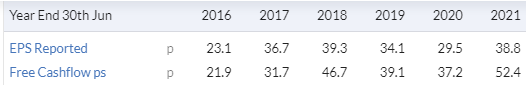
On balance, I don’t have any serious worries about the quality of this business. My only real concern is whether City of London will finally start to deliver more consistent growth.
Momentum: cautiously optimistic
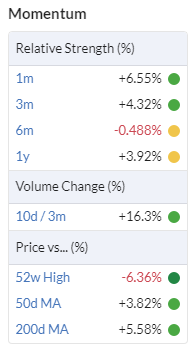
City of London’s MomentumRank of 93 suggests a strong outlook for earnings, with good technical support for the share price.
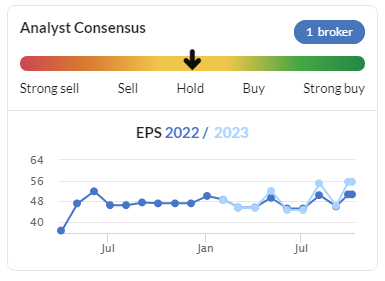
Earnings estimates: Broker coverage is limited but the consensus trend has drifted gradually higher since the start of this year. Forecasts for the 2022/23 financial year have also improved and show more growth than previously expected:
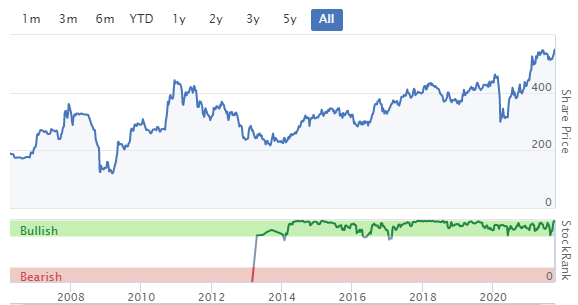
Price momentum: CLIG’s share price is currently close to all-time highs:
This is reflected in a strong set of technical momentum scores:
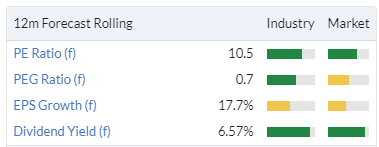
My view: Analyst coverage is limited but the consensus view seems to be that the earnings growth seen last year is sustainable and should continue. If that proves correct, then I’d argue that CLIG shares could offer good value and decent upside potential at current levels:
My decision
The logic behind the CLIG-Karpus merger was that by offering a wider variety of services to a broader mix of clients, the enlarged group will be able to stimulate fresh growth.
Early results appear promising, but I think it’s too soon to be sure. Stock market history is littered with examples of companies that have attempted to diversify, but have only managed to ‘diworsify’, as Peter Lynch famously termed it.
I’m sufficiently optimistic to be a recent buyer of CLIG stock for my main personal portfolio. But I’m not entirely convinced that it’s a suitable addition to SIF, due to portfolio diversification concerns.
SIF already holds shares in financial services group Tatton Asset Management (LON:TAM). While there isn’t much direct overlap between TAM and CLIG, both ultimately derive most of their income from selling asset management to western investors. I suspect that both would see fee income fall in the event of a broader market downturn.
For this reason alone, I’m not going to buy City of London Investment Group for the SIF folio this week. But my favourable impression of this business remains intact.
Disclosure: At the time of publication, Roland owned shares in Persimmon, Tatton Asset Management, Airtel Africa, Beximco Pharmaceuticals and City of London Investment Group.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
I'm glad you've put the spotlight on City Of London Investment (LON:CLIG) Roland. It's a long-term favourite of mine and is about 9% of my portfolio which is high for me. There are a couple of other points I'd like to draw out for the benefit of other readers
Pros:
Risks:
Their latest investor report is worth a read for anyone starting their research: https://www.clig.com/investor-...
You reference City Of London Investment (LON:CLIG) reaching all-time highs but I think the historic chart should be treated carefully now as the merger has created a larger company with a higher earnings per share so it should absolutely be hitting all-time highs.
ps I always enjoy your articles - they're very thoughtful - and would be great to see you as a more regular commentator in the SCVR.
Roland - On the old site it was very easy to navigate to your list of recent trades and the SIF Folio now I can't seem to do it. Is this function no longer possible or am I missing the obvious?
@icm
It's no longer possible to view the SIF folio in the way you could on the old site.
However, I publish a monthly review article which includes a snapshot of the portfolio. You can find the review for September here:
https://www.stockopedia.com/co...
At present, these reviews only include details of stocks I'm selling. New buys are listed in other weekly articles.
However, what I'll do from now on is to include a list of recent buys in each monthly review too. That way, each review will provide a complete snapshot of activity in the preceding month.
Incidentally, you can find all of my articles on my author page, which can be found on the "Discuss" tab:
https://www.stockopedia.com/au...
Regards,
Roland
Roland - Thank you for taking the time to reply and for your proposed strategy going forward, much appreciated - it was hugely helpful on the old site to be able to look at the list of recent trades, I can be offline for weeks at a time so it was a quick way of double checking I hasn't missed anything.
One reason CLIG has not performed better, share price wise, in recent months is that Barry Olif is SLOWLY selling off his entire stake.- 2.35%. 1.2 million shares . At the present rate of selling this is going to take some time. But when done the sp. should catapult upwards.
In the meantine a healthy divi. supports having a holding.
xd. Thursday - 22p
As a sizeable shareholder (28%) City of London has been an active player supporting the recent move by the board of Genesis Emerging Markets to switch the management contract from Genesis to Fidelity, which is a situation that I think is well worth looking at if you are a follower of investment trusts . The new ticker is FEML. There will be a tender offer to shareholders which will reduce the size of the trust, but thereafter the board and shareholders will hope to see the trust grow and perform better. (Jonathan Davis, Editor of the Investment Trusts Handbook).
Great write up Roland, City Of London Investment (LON:CLIG): comes up in one of my favored screens but the killer with this stock is the spread can be all over the place and sometimes stretch's out to north of 5-10% so even at 5% your looking at making 12% on a round trip just to break even when you factor in dealing costs and stamp duty also.
Regards Andy
The spread is only about 2% at the moment but I know it will vary depending on volumes traded and time of day. This is a problem with UK small/mid caps.
Hi Andy,
I agree; liquidity is not always that good on £CLIG. The spread can be wide, but looks reasonable at the moment at c.2%.
If I added the shares to the SIF folio, liquidity might be an additional risk - the spread would likely widen on the event of bad news.
Regards,
Roland
Disc: I hold CLIG.
I have held City Of London Investment (LON:CLIG) for a few years but this week sold out of most of my holding., as the price was holding up despite general market weakness. My reasons for selling were
1). Last year saw AUM growth because of rising markets but despite the approx £800m of net outflows. There seems no reason to assume the trend of net outflows will be reversed.
2). In the most recent quater, markets have been weak and in particular emerging markets (still half of AUM). So will AUM have fallen in last quarter?
3). Last year most of the funds outperformed as discounts narrowed - in the last quarter we have generally seen discounts of ITs widen - therefore can we expect underperformance?
4). I had not realised before how large CLIG’s holdings are in some of the key emerging market Inv Trusts - sometimes close to 30% (eg JII). I presume this bulkiness of position will put off a number of potential investors in CLIG’s EM funds.