SIF Folio: Super profitability at Tatton Asset Management

My stock screen store cupboard is almost bare once again this week. But there is one new contender which could fit into my rules-based SIF portfolio.
AIM-listed Tatton Asset Management (LON:TAM) describes itself as “powering the UK’s leading financial advisers”. What this firm does is to provide discretionary fund management, a range of IFA support services and mortgage provision for IFAs. In short, it’s a complete ‘back end’ for financial advisers.
Graham looked at Tatton’s 2018 results here and a later trading statement here, where he flagged up strong growth.
The firm has just published an audited set of results for the year ending 31 March 2020, so now seems an ideal time to take a fresh look at this stock, which has performed well in the interim.
So far, so good
Back in 2018, Graham commented that as Tatton only floated in 2017, he feared a post-IPO mishap. It’s a common phenomenon, but so far these fears have proved unfounded:
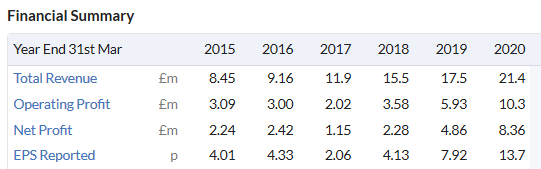
One reason for the continued strong growth may be the presence of founder-management. TAM is led by founder and chief executive Paul Hogarth, who floated the company in 2017. Despite selling a chunk of shares in the IPO, he retains an 18.9% holding and is the firm’s largest shareholder.
We can see this information with Stockopedia’s excellent new(ish) major shareholder feature (on the Accounts menu):
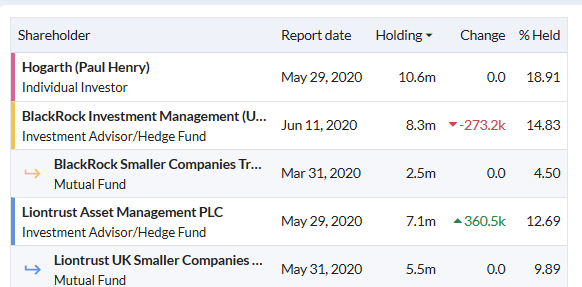
The other major shareholders are all well-known institutional names. I’m encouraged to see this £160m firm already has a strong following in the City. This impression is reinforced by the make-up of the board. Tatton’s chairman, Roger Cornick, was previously chairman of (then) FTSE 100 firm Aberdeen Asset Management.
Is there space for Tatton Asset Management in the SIF Folio? At first glance, the portfolio already appears to have a big allocation to financials:
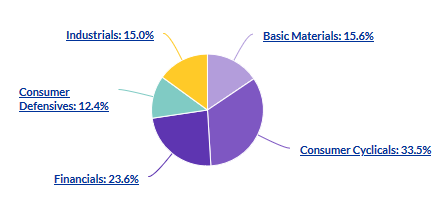
This allocation to the financial sector currently contains three stocks. The first two of these are pawnbroker H&T Group and German commercial property group Sirius Real Estate. I’m confident there’s no overlap with these.
However, the third of my existing financials is business broker K3 Capital. This is a recent addition that bears some similarities to TAM, with high margins and owner-management. I feel that K3 Capital could be subject to the same kind of cyclical effects as Tatton.
However, I’m not going to rule out Tatton on this basis. My rules on diversification aren’t cast in stone and if I like the stock enough, I’ll consider adding it.
Impressive results
Before I take a look at Tatton’s quality, value and momentum scores, I think it’s worth taking a quick look at the group’s latest results. As I mentioned earlier, these are fairly impressive.
Revenue +22% to £21.4m
Underlying operating profit +47% to £8,714m
Operating margin: 48>#/p###
Net cash +5% to £12.8m
Assets under management +9.6% to £6.6bn (net inflows £1.1bn)
Gross mortgage lending +17.5% to £9.9bn
I should point out that Tatton is a middleman in all asset management and mortgage transactions. The Paradigm mortgage business works as a distributor, with access to a panel of mortgage lenders.
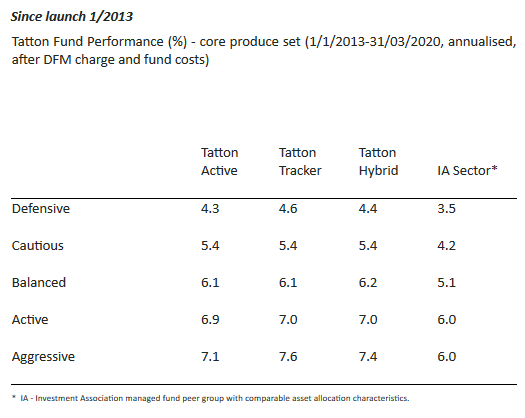
Similarly, the investment portfolio options offered by Tatton for clients of its member firms are administered by other institutions. However, Tatton plays a role in defining these portfolios and on the whole, they appear to have modestly outperformed the managed fund sector since launch in 2013:
The firm’s value-add appears to be in its scale and reach. The Paradigm Consulting business offers a broad range of support services to its IFA members. These increased by 10.9% to 1,544 last year, representing 66,100 customer accounts. This equates to an average customer investment account size of c.£100k.
Cash generation from this business is good and although Tatton only takes a slice of the fund management fees and mortgage commissions, it’s still able to generate very high margins and returns on equity.
Let’s take a closer look.
Value: not really
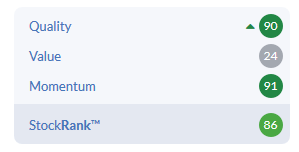
Tatton Asset Management enjoys a StockRank of 86 and is styled as a High Flyer by Stockopedia’s algorithms:
Unsurprisingly, the firm’s shares are priced for success, not value. The shares look expensive on most trailing measure of valuation:
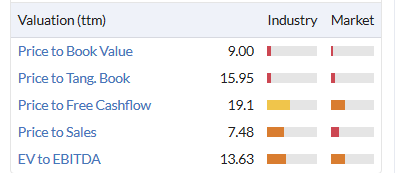
Despite this, Tatton still passes my screen’s valuation tests. The reason for this is that my screening criteria look at valuation in the context of profitability and growth rate. Here’s how it works.
The relaxed version of my screen that I’m using currently has three rules relating to valuation:
Rolling forecast P/E between 7 and 30 (TAM: 20.6)
Earnings yield (EBIT/EV) > 6% (TAM: 7%)
Rolling forecast PEG (price/earnings growth) <1.3 (TAM: 0.9)
As you can see, Tatton passes all of these comfortably.
I’d also add that although the stock is richly valued, the group’s high return on equity and strong cash generation mean that it can still support an attractive trailing dividend yield of 3.4%.
For these reasons, Tatton Asset Management’s demanding valuation doesn’t necessarily concern me too much.
Quality: star attraction
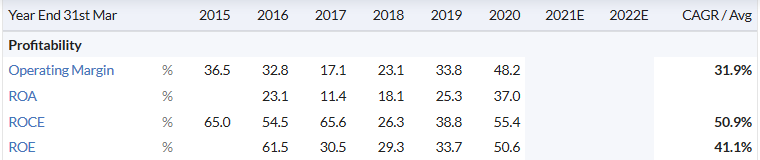
A QualityRank of 90 suggests great things in the quality department. Tatton’s profitability metrics don’t disappoint. Last year’s return on equity of 50% is outstanding:
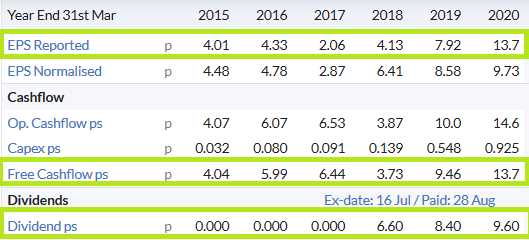
Another quality measure that is very important for me is free cash generation. In its latest results, Tatton says it converts c.100% of operating profit into operating cash flow. This is reflected in the close match between [after-tax] earnings per share and free cash flow per share:
I’m very comfortable with Tatton Asset Management’s profitability and quality metrics. My main concern relates to the outlook. As the UK faces a possible recession, is now the right time to invest in a company which ultimately relies on the economic health of Middle England?
Momentum: limited growth
I’ve no idea how well the economy will recover from the impact of the COVID-19 pandemic. Early data as lockdown eases seems inconclusive to me. I think it’s prudent to expect some degree of slowdown, however, if only because of the number of job cuts which seem likely.
Brokers covering Tatton appear to share this view and have trimmed their forecasts over the last three months:
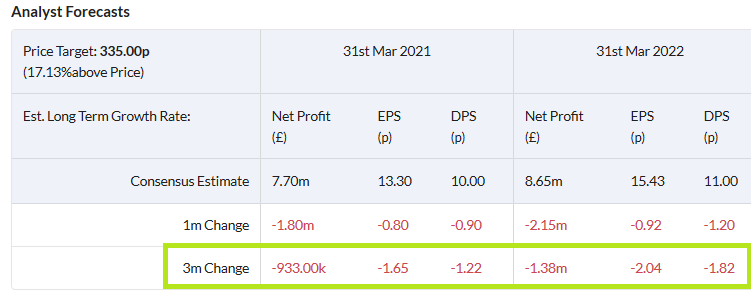
However, these forecasts still indicate eps growth of 10%-15% in FY21 and FY22. If the group’s profitability can be maintained, then I’d suggest the current valuation might still leave room for growth.
The stock’s price momentum certainly appears to be strong:
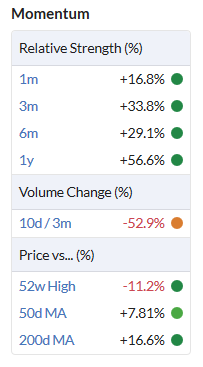
As things stand, the stock’s MomentumRank of 91 seems reasonable to me.
My decision
There’s obviously considerable uncertainty about the outlook for the UK’s financial sector and the wider economy. But Tatton appears to have a very sticky customer base, with recurring revenue of 85% over the last three years. I’d hope that many of the end clients of its services would stay put during a recession.
Although the valuation is quite full, this appears to be good quality business with a strong balance sheet and very attractive margins. Net cash at 31 March was enough to cover a year’s operating expenses, providing a reassuring margin of safety.
I’ve decided to add Tatton Asset Management to the SIF virtual portfolio and my own real money portfolio. Like my recent purchase of K3 Capital, this is a bullish choice that assumes a fairly prompt recovery.
My hope is that any disappointment in this regard will be partially hedged by more defensive portfolio stocks, such as B&M, BAE Systems, Finsbury Food and British American Tobacco.
As always, I’d very much welcome your views on Tatton and the outlook for the wider market. How are you positioning your portfolios? Or are you staying in cash until greater certainty appears?
Disclosure: At the time of publication, Roland owned all the shares mentioned except Tatton Asset Management.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
Recent interim results were very strong in my opinion yet I have been surprised by a lacklustre SP performance. Do others think it is just symptomatic of a struggling financial sector just now?
I agree the the H1 results were good. These are the thoughts that I wrote down last night after going through the results and listening to the results presentation:
Tatton is a remarkably high quality business at a decent valuation. I say this because consistently high operating margins (>30%) have enabled a high ROCE (>50%) even as the business has grown at double-digit rates. Capital requirements have remained low driving the FCF conversion rate above 100% in many years. Despite this the share price hasn't managed to gain much traction since listing at 156p in 2017. For sure its done alright, being up 81% since that point, but the P/E rating has drifted down from 30 to ~20 now which tells me that the shares haven't kept pace with earnings growth. This is a conundrum as analyst forecasts point to 40% EPS growth in 2020, despite dipping 8% from 14.95p to 13.7p over the year, and Tatton have just reported H1 earnings of 6.55p (up 21% on improving margins). Listening to results presentation it's clear that the investment part of the group has performed very well so far while IFA services took a knock from mortgage and valuation work cratering during the lockdown. Still the housing market has bounced back strongly since the summer and it's reasonable to have some optimism for H2. It's still hard for IFAs to bring on new clients, which is a headwind, but eventually restrictions will ease and Tatton will be in the right place to benefit. At the same time it's clear that management are on the acquisition trail. One bid fell through (which suggests that they won't pay any crazy price) but they now have a £30m credit facility in place which makes them deal ready. There's a lot to like here and when the share price breaks 300p I reckon that it'll move up quickly to the 400p level.
The CEO Paul Hogarth previously co-founded Bankhall. He has been there and done it. One of the reasons I hold this stock.
I like Tatton AM - but dont like the chances of a V shaped recovery. Will definately mark this stock as one to potentially buy when the current house of cards falls (as I suspect it will between mid-August / September)
Sounds tempting - however I'm sitting on my hands for now. As a newby not "qualified" to say more but thanks for asking. Iv'e just got burned - bought Babcock back in April just wish I had had Stockopedia then rather than relying on Simply Wall Street. Also bought Enbridge, Ternium and Unum using same source. First two Okay but UNUM is a bit sticky will hold all (they are in this years ISAs') for now in the hope that the divis will help compensate for poor pics.
By-the-bye, and fortunately, I bought Gilts many years ago and they are providing a good reliable I/C will definitely hold and just trade around the edges with cash as it becomes available. At 84 and 81 our horizons are limited!
Hi Roland, very interesting - thanks. I happen to own the 4 defensive shares you mention above. Finsbury is part of my new Blastig portfolio that I've created since I joined Stockopedia. The portfolio was started on 20th Feb (so awful timing) and is based on Screens (Q/V). I am pleased to report is in the black - just - so ~20% ahead of the Market. TAM has gone onto my watch list. BTW have you any views on FIN - the news form them is quiet to the point of morbid.
Regarding cash - I am mostly invested with my UK Portfolio but am at about 40% cash with my (very successful, but much smaller) US one. Think the valuations of the US tech shares are entering bubble territory.
Hi Berksbee,
Thanks for your comment. It sounds like your new portfolio has performed pretty well so far this year.
I don't know much about Finablr (LON:FIN) but I believe it has until until 28 August to file accounts (here). I fear the outlook for equity may not be very good, given the possibility of fraud and high levels of indebtedness. Commiserations to holders.
Regards,
Roland
Hi Roland - many apologies - I meant Finsbury Food (LON:FIF) - Finsbury Foods - which is the one real laggard in my portfolio and you also hold in SIF. I appreciate though that everything depends on an in price. FIF ticks a lot of boxes but has shown no inclination to bounce. I too had never heard of FIN - and am glad I hadn't!
Morning Berksbee, I too had been frustrated with the RNS silence from Finsbury Food, so I shot them a cheeky email at the end of May asking if everything was ok, and did they need rescuing from a giant dough mixer, etc.
A very nice PR bod called me back that day to explain that FIF were trading to the big supermarkets at roughly the same rate, but that their catering supply side was effectively paused. She promised a big update by the end of June.
When the end of June came and went with no update I sold 50% of my stake. I still like them as a business, but it seems very straightforward to know how many cakes you are selling and to whom, and the impact on revenues- not sharing with investors makes me uncomfortable.
As ever DYOR.
44% in cash as of this morning
Hello Roland,
I always enjoy your SIF articles as they bring to life many of the qualities I aspire to in my investing. Your professionalism, self discipline and systematic approach are all things I think I need to work on.
I am essentially a growth investor and I am willing to pay a very high price if I think sufficient quality and potential are on offer. As such it is rare for SIF and me to be watching the same candidate shares.
However in the case of tam I am a big fan. I will probably buy this when it breaks above £3. I think you have covered most of the good points but in addition I would emphasize the cost advantage of tam vs it's competitors.
According to tams claims it is approx 50% cheaper than its competitors (in the prospectus). I haven't independently checked this claim but if true it would explain why organic growth of aum is so strong. Tam thinks it's quite hard for competitors to copy the cost structure too.
Damian Cannon did a good write up on tam here:-
https://www.stockopedia.com/content/equity-development-seminar-february-2020-558651/
Hello HRR,
Thanks for flagging up Damian's write up. It's always useful to get another perspective.
I'll have to dig a little further into Tatton Asset Management (LON:TAM) cost structure.
Regards,
Roland
Great write up Roland I like Tatton Asset Management (LON:TAM) also has flagged up on my screen all be it seems close to two year high I would want to see it either get through £3 before entering or a bit of a pull back to the £2.50 area before entering.
Bail out of BooHoo or hold ??