SIF Folio: Two new stocks for 2022

The stock buying screen I use to add shares to my rules-based SIF portfolio has been going through an extended dry spell. I have not been able to add a new stock to my rules-based SIF portfolio since 23 November, when Burberry joined the fold.
This lack of supply has coincided with a run of profit taking on positions across the portfolio. As a result, SIF had a 45% cash weighting at the end of 2021. This situation has come about as a result of me following the rules, so I’m not unhappy. But I’m aware that unless the market falls sharply, my cash weighting could dampen down returns from the portfolio in 2022.
A New Year double dip
SIF’s long dry spell means that I’m able to activate my fallback plan. This allows me to relax two of the valuation criteria in my screen to widen my pool of potential buys. It’s an idea I borrowed from the legendary Jim Slater that has worked quite well for me over the last few years.
To relax my standard buying screen, I make the following changes:
Minimum earnings yield: reduce from 8% to 6%
Rolling PEG ratio: increase limit from 1.2 to 1.3
You can see the full amended screen, with current results, here.
When market conditions are buoyant, I’ve found that switching to the relaxed screen can make a big difference to my screening results. That’s true now. Only nine stocks currently qualify for my standard screen, but 19 qualify for the relaxed screen.
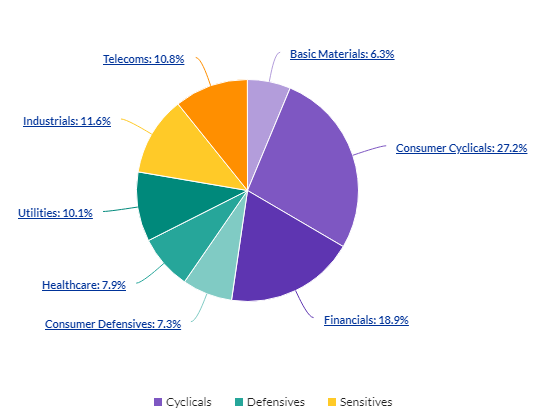
I sort my screening results by StockRank. At the top of the list are housebuilders Redrow (LON:RDW) and Vistry (LON:VTY) . But with 27% of the portfolio already invested in consumer cyclicals – including Headlam (LON:HEAD) and Vertu Motors (LON:VTU) – I am not comfortable adding further exposure to this sector.
Instead, I’m going to look at adding not one but two new industrial stocks to the portfolio, Redde Northgate (LON:REDD) and £MGAM
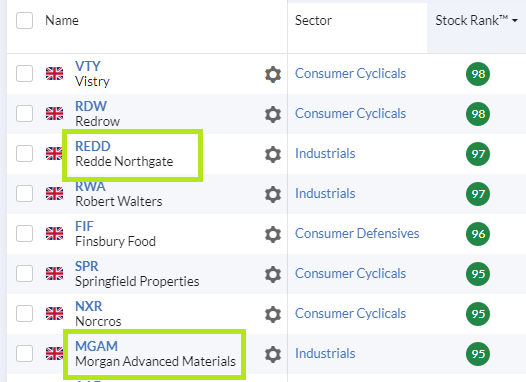
I don’t normally add more than one stock at a time to SIF, but there’s no rule against it. In this case, I looked at Morgan Advanced Materials a few weeks before Christmas and liked what I saw.
I’d recommend taking a look at my original write-up if you haven’t seen it, but one key attraction is that the group has been trading ahead of expectations in recent months:
Another attraction for me is that renewable energy demand appears to have created a structural growth market for some of Morgan’s key products. I think this has the potential to dampen cyclicality and support continued growth for some time to come.
As I’ve already done the leg work on MGAM and this stock satisfies my relaxed buying rules, I’ve decided to add Morgan Advanced Materials to SIF this week.
Can I love Redde Northgate?
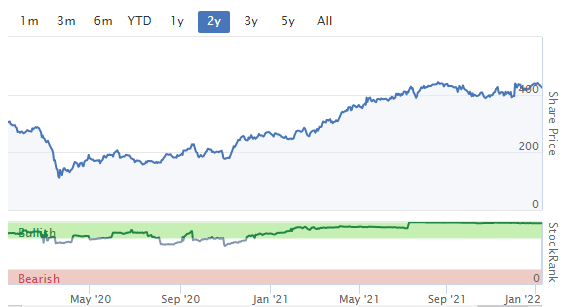
I know that “integrated mobility solutions platform” (van hire plus accident management) group Redde Northgate is popular with many subscribers. The company’s performance over the last two years suggest this view may be correct. The StockRanks also correctly spotted this opportunity:
Personally, I’ve always struggled with this business. When the merger between Redde and Northgate was announced in early 2020, I questioned the value of the combination.
In December, I looked at the group’s latest half-year results in the SCVR. I pointed out that the merged group was formed during the pandemic and has been a net beneficiary from new vehicle shortages. I was also discouraged by the low margins on accident management, compared to hire operations.
However, I have to accept that so far, the numbers say that I’m wrong. Redde Northgate appears to be trading well and is winning new business from corporates such as Tesco and insurer Admiral. December’s interims were very strong, in my view.
Perhaps the company’s combined offering really is hitting a sweet spot with enterprise customers who want to outsource their fleet management and accident repair activities.
Ultimately, SIF is a rules-based portfolio. This means I must set aside my prejudice and consider Redde Northgate with an open mind. In that spirit, let’s take a look at some of the stock’s key financial metrics.
Value: pretty reasonable
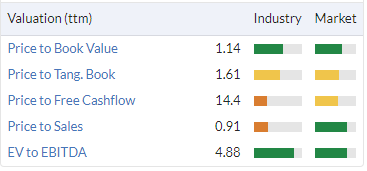
A ValueRank of 79 suggests a broadly favourable valuation. This view seems to be supported by Redde Northgate’s main valuation metrics.
Balance sheet & cash flow: I covered the latest accounts in the SCVR in December, so I won’t repeat that analysis here. My conclusion was that leverage and underlying cash flow were both acceptable.
Valuation: Stockopedia shows a trailing 12-month earnings yield of 7.6% for Redde Northgate. That’s only a whisker below my standard screening threshold of 8%, which I consider to be good value.
I’ve no serious concerns about the stock’s valuation at current levels.
Quality: improving
Running a 120,000 vehicle hire fleet is fairly capital intensive. In a competitive market, I don’t expect very high margins or returns on capital. However, Redde Northgate’s profitability looks acceptable to me. Most importantly, the trend is improving:
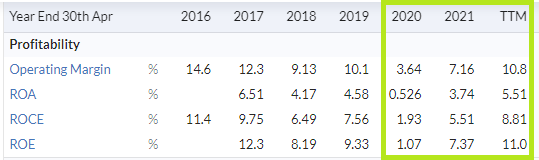
Although these profit margins and returns are fairly average, Redde Northgate enjoys a QualityRank of 76. One reason for this is the stock’s Piotroski F-Score of 7/9.
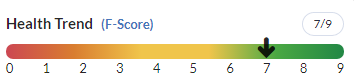
A high F-Score indicates improving trends in profitability and cash generation. I find the F-Score a useful metric – for more ideas on how it can be used to find affordable quality stocks, check out this new piece from Ben.
Momentum: stonking
Redde Northgate’s MomentumRank of 96 is near perfect and suggests a strong set of tailwinds for the stock. Let’s drill into this to see what’s behind these numbers.
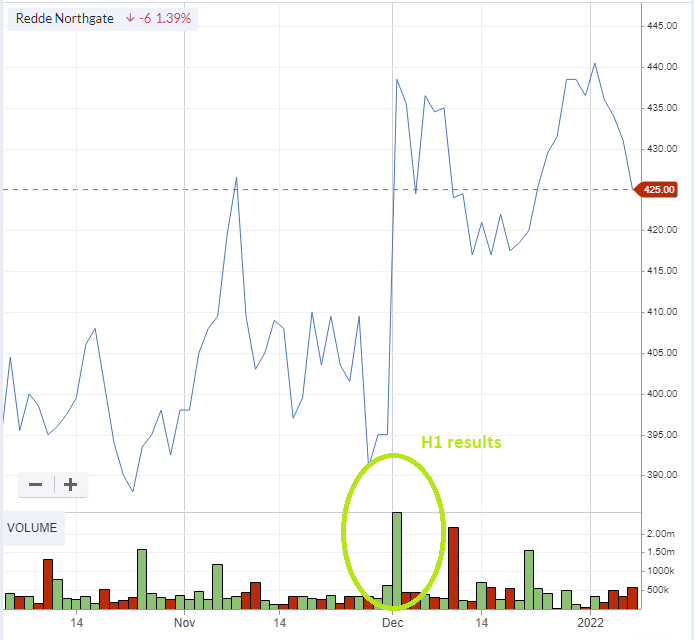
Price momentum: The stock’s strong performance over the last year means that technical indicators are mostly positive:
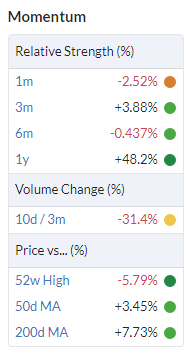
The only exception here is the 10d/3m volume indicator, which shows a drop-off in trading compared to the three-month average. Looking at the volume data on the three-month chart, I think this is probably due to the post-results surge in trading, followed by the quiet period over Christmas. I don’t think it’s a concern.
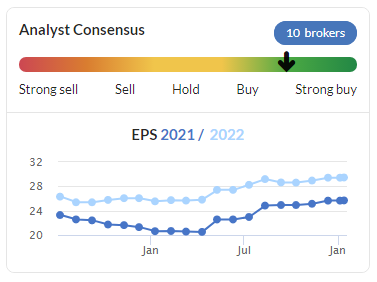
Earnings estimates: The other element to momentum is earnings growth. This is neatly illustrated by Stockopedia’s consensus trend chart, which shows regular upgrades to earnings forecasts over the last year – a positive momentum indicator:
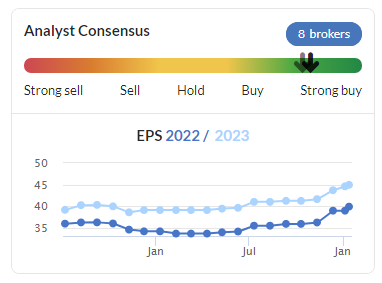
Overall, I can’t find anything to fault with Redde Northgate’s momentum metrics.
My decision
As you can probably guess, I have decided to add Redde Northgate to SIF this week, in addition to Morgan Advanced Materials. I’ll also add both stocks to my personal holdings. All trades, virtual and real, will be executed after this article has been published.
Let me know what you think about REDD and MGAM in the comments. Do they deserve their Super Stock status, or are there hidden risks I’m missing?
Disclosure: At the time of publication, Roland owned shares in Burberry, Headlam and Vertu Motors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
since January the Ukrainian war, a probable US recession and scary economic news from China have happened. I am pondering whether to cut my losses in MGAM as the downward share price continues. And yet I can't find any company specific news in that period. To sell or not to sell, that is the question.
The list of 8 stocks shown above which includes the two new stocks REDD & MGAM, where can we find the live screen 'Of your current S.I.F Portfolio
post same two indian stocks for jan2022
Why don't you?
Most subscribers don't have access to Indian stocks and can't trade them.
Thanks Roland for a fantastic review, its comforting to see that we have quite a few stocks in common, Vertu Motors (LON:VTU), Airtel Africa (LON:AAF) and Redde Northgate (LON:REDD) . Burberry is flagging on my screen , so I think I will go through your article on Burberry as a starting point.
Thanks for sharing your insights .
Roland I first bought Redde Northgate (LON:REDD) in Nov 2020 at 227p after listening to Andy Brough and Richard Leonard on PI World hosted by Tamzin Freeman who I have to say always brings out the best in those she interviews.
I added in March 2021 at 275p and I sold one third of my holding in June at 402p and the remainder in October at 394p.
I was influenced to sell by my sale of Reach (LON:RCH) in August & Sept which produced a massive return but then fell sharply. I was afraid Redde Northgate (LON:REDD) might perform likewise but I was wrong.
Your decision to add Redde Northgate (LON:REDD) has encouraged me to consider buying back in but the market is rather scary at the moment so I am being very cautious.
I always find your articles very well researched and when your choice is backed up by the views of guys like Richard Leonard and Andy Brough it makes for compelling reading.
Thank you very much.
Hi Roland - great write-up as usual.
Like portugull I had bought into Redde Northgate (LON:REDD) lateish 2020 after doing further research following both Richard L & Paul's reviews. I am not regretting it.
I did sell a chunk of it after Aug 21 when it started to drop, but was pleased that it didn't drop as much as many of the other small-caps (possibly as this is larger than a lot of others with a mkt cap over £1bn) and there didn't seem to be a lot of volume driving the market. Therefore I topped back up again.
Whilst I can see the risks that have been mentioned by many it is also pleasing to see that the fundamentals look very solid and management seem to be delivering on their promises.
I remain happy with my holding and will look to continue to do so.
I'll take a look at Morgan Advanced Materials (LON:MGAM) as this is one I am not familiar with at all.
Thanks very much.