SIF March review: Locking in profits (K3C, BME, MOTR, SRE)

As I write, the sun is shining and the temperature is unseasonably high. Lockdown is starting to unwind. Is this finally the start of a return to normal, or are there more setbacks to come?
It’s too soon to be sure, but markets seem optimistic. I can think of a number of stocks in the travel, leisure and hospitality sectors that are priced at pre-pandemic levels when recent debt and equity issuance is factored in.
Checking through my portfolio records I find there are four stocks that have been in SIF for nine months or longer. This means they’re due for a monthly review against my selling criteria. The companies concerned are:
Used car supermarket Motorpoint Group (LON:MOTR)
Corporate finance firm K3 Capital Group (LON:K3C)
German commercial property firm Sirius Real Estate (LON:SRE)
Discount retailer B&M European Value Retail (LON:BME)
I’ll look at each of these in more detail in a moment. But let’s start with a look at the performance of the portfolio over the last month.
SIF Folio: March performance
The portfolio has continued to bounce around its all-time high over the last month:
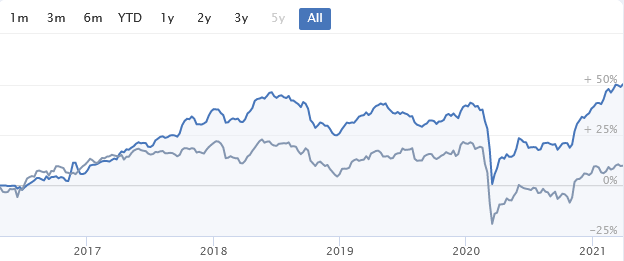
However, there has been little real change since my last monthly report. SIF’s performance has been broadly in line with the wider market in March:
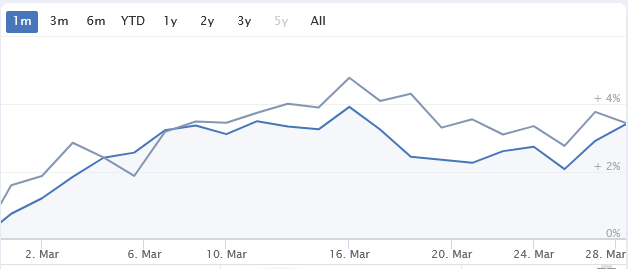
I’m not going to attempt to read the tea leaves on future market movements. But for what it’s worth, my feeling is that many valuations remain quite full. However, I think that some pandemic winners -- such as B&M -- are now starting to come back down to earth.
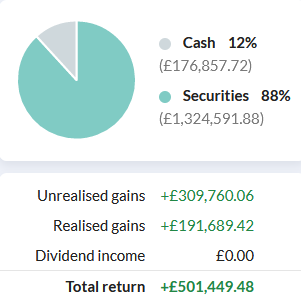
The portfolio’s cash position increased after last month’s sales of Morgan Sindall and Countryside Properties:
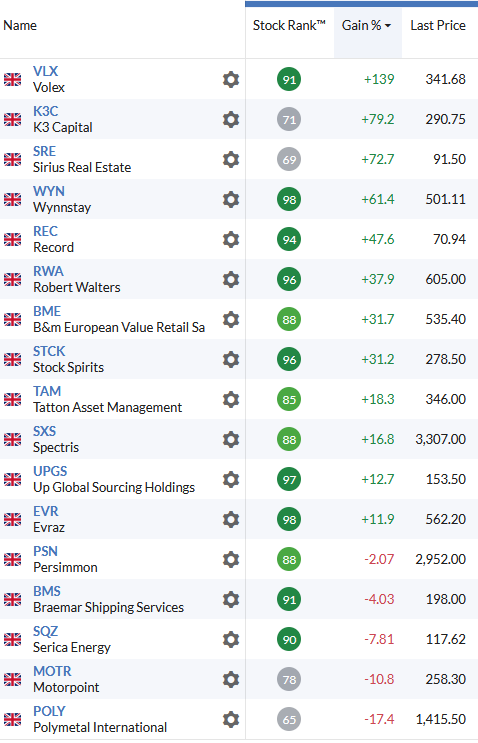
Finally, here’s a full list of the portfolio’s holdings on 29 March, before any transactions that might result from this review:
B&M European Value Retail (LON:BME)
This value retailer has been an excellent performer for SIF, but the stock is well down from its 600p highs. B&M has stayed open during lockdown, thanks to its essential retailer status. The company’s wide product ranges and retail park locations mean that it’s attracted shoppers who might normally have gone elsewhere.
In fairness, recent commentary from CEO and significant shareholder Simon Arora has been quite open about the possibility that sales growth will slow when other shops reopen.
Investors who aren’t convinced by this logic might want to consider Mr Arora’s recent actions. In November and January B&M declared special dividends totalling £450m. Shortly after the second of these, the Arora family sold 4% of their shareholding, generating gross proceeds of £218m. They now control 11% of the stock, down from 15% previously.
B&M still passes most of the tests on my selling screen. The only exception is the PEG ratio test. B&M fails this test because profits are expected to fall this year:
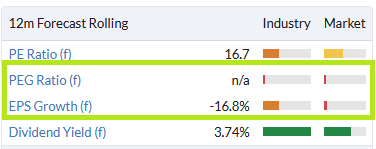
Stockopedia shows earnings falling by 17% in FY22, versus FY21 (year end 28 March). Digging around elsewhere, I’ve found that consensus forecasts also suggest that FY23 profits will be lower than in FY21.
My view: Recent special dividends of 25p and 20p per share mean that B&M has paid the biggest dividend SIF has ever received. These payouts plus two ordinary dividends have generated a 13.5% cash yield on cost for SIF’s holding. This isn’t what I expected when I bought the shares last June, but this firm really has been a pandemic winner.
I suspect B&M’s formula will remain popular and successful. But from a short-term perspective, I think now could be a decent time to lock in a gain for SIF.
Total return: +45%
Verdict: Sell
K3 Capital Group (LON:K3C)
This corporate broker has been another strong performer since last June. K3C is listed on AIM and has a market cap of £200m. The group has six main operating companies which collectively handle SME company sales, corporate tax advisory, insolvencies and corporate finance.
K3C’s most recent acquisitions are tax advisory specialist RandD UK and restructuring firm Quantama. Both deals appear to have been successful, so far, and the firm has traded through Covid-19 with little apparent impact:
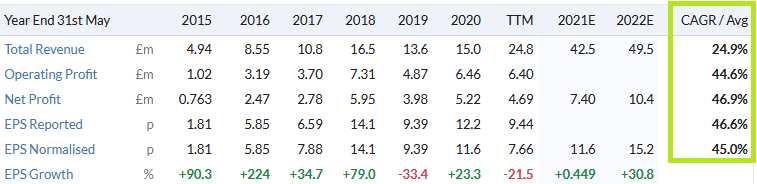
K3 said recently that it was trading ahead of expectations for the current year. However, consensus forecasts for 2021 and 2022 have since been trimmed, suggesting that analysts expect growth to slow.
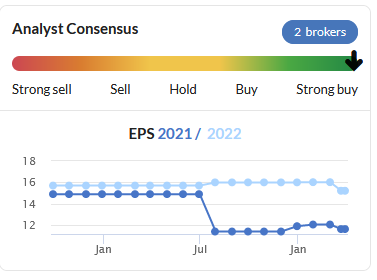
For this reason, K3 Capital shares no longer pass all of my screening tests.
My view: I’ve been impressed by K3 Capital’s profitability, cash generation and growth over the last year. But the shares have doubled since November and I feel that there are some cyclical risks here too. I’d imagine that business could slow dramatically in a recession.
As Paul and Jack often note in the SCVR, buy-and-build strategies can deliver volatile results. K3’s share price action has certainly been mixed since its flotation in 2017:
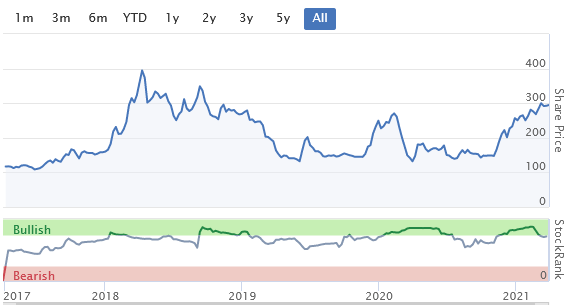
SIF’s holding has delivered a total return of more than 80% in nine months. I don’t feel too bad about taking profits at this point.
Total return: +82%
Verdict: Sell
Motorpoint Group (LON:MOTR)
I’ve admired used car supermarket group Motorpoint for some time. I’ve held onto the stock in SIF despite a lacklustre share price performance. Until this month, I’ve been able to say that the shares still pass all of my tests. That’s no longer true.
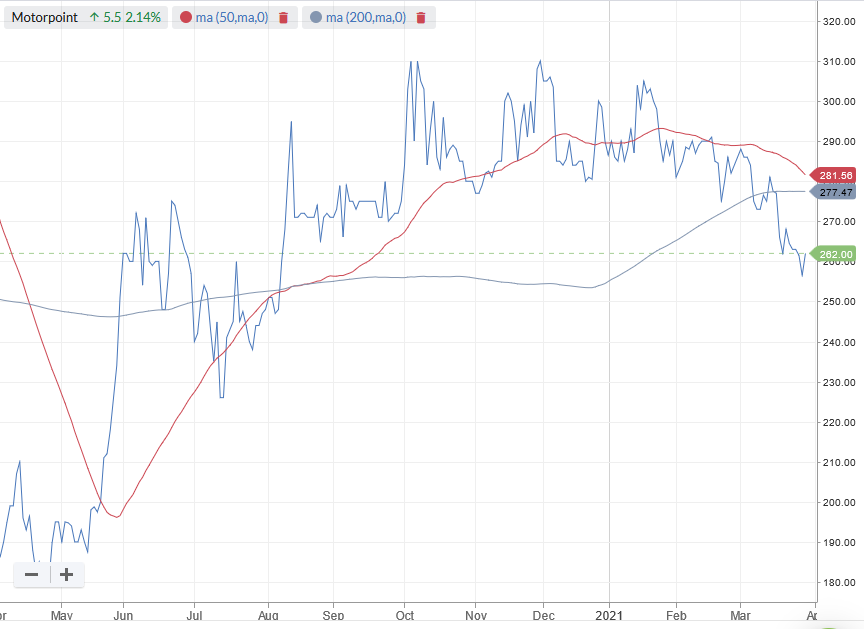
Motorpoint’s weak share price performance means that the stock has now fallen below its 50-day and 200-day moving averages:
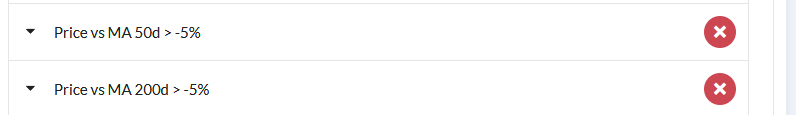
This violates two of the tests in my selling screen:
My view: I still rate this business highly and believe it’s likely to recover well when car showrooms reopen. But this is a simple case of following the rules, which say I must sell Motorpoint from the SIF fantasy fund.
Total return: -11.5%
Verdict: Sell
Sirius Real Estate (LON:SRE)
German commercial property group Sirius Real Estate popped up in my buying screen in late March 2020, when markets were about to bottom out. This FTSE 250 group is a stock I’ve held before, so I was already familiar with its business model.
Sirius’s business parks generally have a mix of property types and tenants. The result - so far - has been a very robust performance through the pandemic. Rent collection for the nine months to 31 December was 97.7%. The company says that only 43 out of 5,000 tenants have been “adversely impacted by the pandemic”, accounting for just €400k of rent.
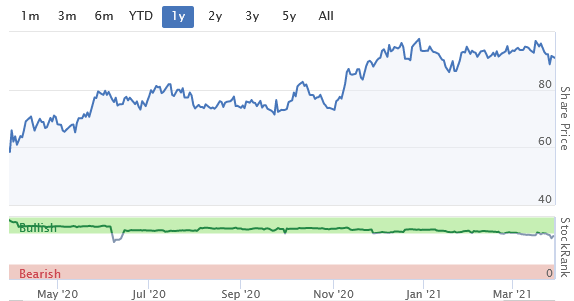
As a result, the shares have performed very strongly since last year’s crash:
My view: I continue to rate this business highly but Sirius Real Estate shares no longer pass all of my screening tests - even after the adjustments I’ve discussed previously.
The main issue seems to be that return on assets has declined over the last year. I don’t see anything to be concerned about and would probably continue to hold the stock in a long-term portfolio. But for SIF purposes, I think I should sell.
Sirius has generated a total return of nearly 80% in one year and the shares are starting to look fully priced to me. I don’t see this as a multibagger from here, so I’m comfortable taking profits at this point.
Total return: +79%
Verdict: Sell
What next?
I didn’t expect to be selling four stocks from SIF (and my personal holdings) this week. These trades will leave the portfolio with only 13 holdings and a fairly heavy weighting to cash.
However, I’ll follow the rules and hope for some new buying opportunities over the coming weeks.
As always, I’ll make the trades listed above after this article has been published. Please share your thoughts in the comments below.
Disclosure: At the time of publication Roland owned shares in all the SIF folio companies.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Totally don't get the sell on K3C, just read Jack last report on them and this totally goes against that. Fair enough views make a market etc but basically your selling because it's cyclical but then cyclical companies are currently doing great and probably will continue to do so for quite some time
I'm a K3 Capital (LON:K3C) holder and I'd suggest that the consensus forecasts seem either wrong or wonky. House broker finncap upgraded by 1.8p after 3 March TU to 13.7p for 2021. That would mean the other broker forecast (Canaccord?) would need to have responded to the significantly ahead of expectations 3 March TU with a downgrade. All things are possible...
But K3C went into 2021 with very conservative guidance on all 3 main areas of the business particularly corporate finance. It seems likely to me that bar a precipitous decline in one area of business, or meaningful slowdown for all 3, that K3C have high chance of positive surprise for year end still.
I need to go back and work out contingent payments to acquisitions made but the guide numbers are probably adjusted for that. EBITDA guidance works out at at least c.17.4p per share and conservatively adjusting that to adj eps means a figure above 14p for 2021.
Short term is unpredictable due to the success fee element of corporate finance business (but note they don't include that in guidance). I'm invested on a longer duration basis believing in the model and people and not seeking to play the short term numbers but I'd guess that 2021 will come in decently above 14p
Earlier anaylsis:
https://www.stockopedia.com/co...
The above was not intended to sound snarky or defensive I hasten to add...
Been thinking of when to sell my B&m European Value Retail Sa (LON:BME) holdings. Always appreciate your honest in depth appraisals, keep it up Roland !