SIF October review: I’m selling one and holding two (FIF, MOTR, DMGT)

The clocks may have gone back but my SIF Folio has made satisfactory progress over the last month, given the wider uncertainty we continue to face.
As it’s the end of the month, I must review stocks which have been in the portfolio for at least nine months. This month, there are three companies on the list:
Cake and bread maker Finsbury Food (LON: FIF)
Used car supermarket Motorpoint Group (LON: MOTR)
Media and events group Daily Mail and General Trust (LON: DMGT)
I’ll come to these shortly, but let’s start with a quick look at the performance of the whole portfolio.
SIF performance: October 2020
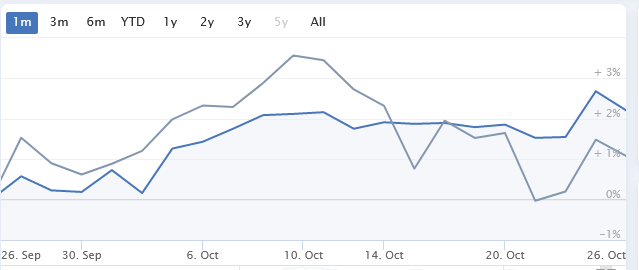
My rules-based SIF portfolio delivered a less volatile performance in October than the wider market, while continuing to edge ahead (SIF = blue, FTSE All Share = grey):
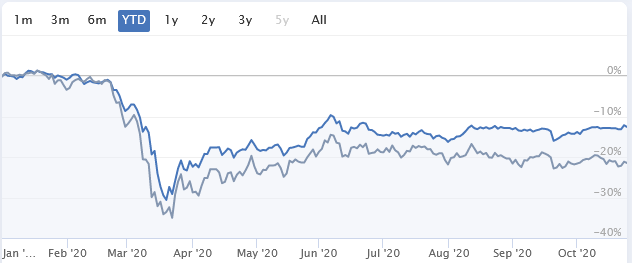
This continues the trend of modest outperformance seen so far this year:
In terms of individual stock performance, it’s been a mixed bag. Nat Rothschild’s firm Volex and German commercial property group Sirius Real Estate have been the standout winners so far this year, but the jury remains out on a number of my other pandemic picks:
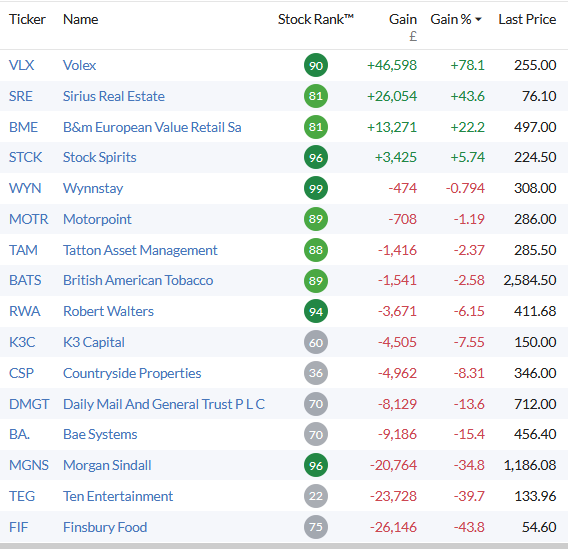
The biggest losing position left in the portfolio after last month’s sales is Finsbury Food. This is one of the positions up for review this week, so let’s start with this food producer.
Finsbury Food (LON: FIF)
(Original coverage: 21-Jan-2020 / FY20 results review 22-Sept-2020)
I did think that this bread-and-cake producer’s recent annual results deserved a slightly stronger show of support from the market. I covered the figures here, which I thought were reasonably in the circumstances.
As a reminder, Finsbury Food historically generated around 20% of its revenue from the foodservice (hospitality) sector. Obviously much of that has been lost this year, with a consequent impact on profits. But sales to retailers have been resilient, on the whole.
However, Finsbury’s share price has remained resolutely unloved since these results. So I’ve been wondering what I might have missed. I can see three possibilities:
The hit to profits from lower foodservice sales could last well into 2021. Perhaps I didn’t weigh this enough.
I was disappointed by the £7.5m impairment charge against the £25m acquisition of gluten-free specialist Ultrapharm in 2018. To me, this looks like a classic example of management paying too much to chase a trend. But perhaps I should be more critical of this wasted corporate cash?
Ultimately, Finsbury is and probably always will be a low-margin business that’s subject to price pressure. Maybe the market is right to be cautious, given the group’s mixed track record.
On balance, I would still argue that Finsbury Food is probably a contrarian buy on six times forecast earnings. But I can see downside risks and my enthusiasm for the stock is cooling. I don’t think it’s really a special business.
My SIF screen takes a stronger view - Finsbury fails four of my screening rules, thanks to its weak momentum, super-cheap valuation (a potential warning flag) and subdued profitability. I have no choice but to sell the shares this month.
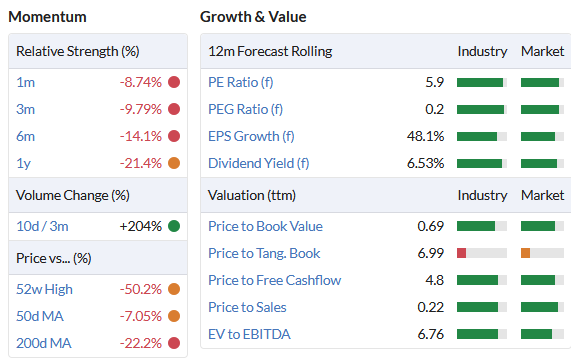
Weak momentum - but it’s cheap if current forecasts can be delivered.
This sale will continue the process of cleansing the portfolio of pre-pandemic buys. Although I think the shares are probably too cheap, I’m not entirely sorry to get rid of them. Brokers covering the firm have taken a dim view on the outlook since the firm’s results were published.
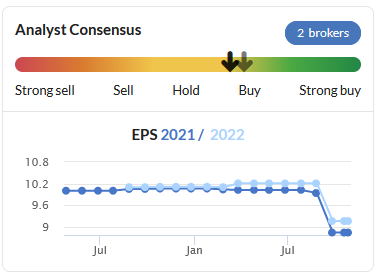
If trading doesn’t improve over the winter, I wonder if the stock’s contrarian rating could slip to value trap.
Verdict: Sell
Total return: -45%
Motorpoint Group (LON: MOTR)
(Original coverage: 14-Jan-2020)
Used car supermarket Motorpoint has (in my opinion) a focused, successful and very profitable business. In contrast to Finsbury, this is a stock where I have stronger conviction and do want to stay involved.
The group’s recent half-year update was encouraging, in my view. Pre-tax profits are expected to be ahead of last year’s figure, thanks to strong demand and good performance on margins.
The only reservation I have is that I’m unsure how much of the recent surge in used car demand is sustainable. I suspect sales could normalise somewhat next year.
In any case, I’m happy to report that Motorpoint continues to satisfy all of my screening rules and will stay in the portfolio.
However, I do have one small confession to make here. I’ve not relied on Stockopedia’s figures entirely and have made an adjustment to Motorpoint’s enterprise value. Without this change, the shares would have failed my screening requirement for an earnings yield (EBIT/EV) of 8%.
What I’ve changed (and why): Stockopedia’s data provider shows Motorpoint as having net debt of £131m at the end of March. Set against the group’s market cap of £270m, this is a material amount.
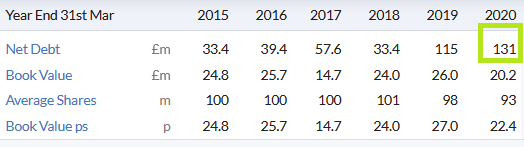
However, according to Motorpoint’s accounts, this debt is limited to stocking finance facilities. All such financing is said to be secured on the vehicle it’s used to buy. According to the firm, stock financing is repayable when the vehicle is sold, or else within 90-150 days.
Excluding this inventory funding, Motorpoint’s net debt position was c.£0m at the end of March. By the end of September, the company says that it had a net cash position of £13m, excluding stocking finance.
I’ve opted to recalculate Motorpoint’s enterprise value (market cap + net debt) by excluding stock financing, which I have effectively reclassified as a trade payable. As it happens, this is also the way it is classified in the company’s own accounts:
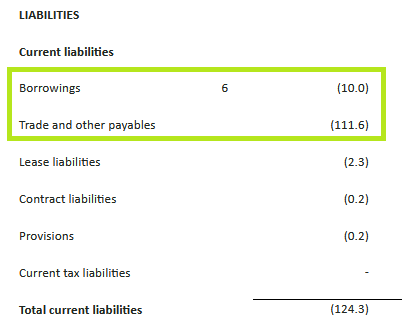
Extract from Motorpoint FY20 balance sheet - stocking finance drawdown of £86m included within trade payables. Borrowings are offset by £10.8m of cash (not shown).
I accept that by taking this decision I am leaving myself open to accusations of bias and of interfering with my system. I don’t habitually recalculate all the stock data for a company, so why do it here?
Broadly speaking, there are three reasons.
1. I believe the view I’ve taken is a reasonable interpretation of the firm’s balance sheet and is not excessively complacent. Motorpoint’s auditors also appear to accept this classification.
2. Taking a wider view, the firm’s half-year trading update indicated that profits for the six months to 30 September should be ahead of expectations. The company also reported an improved net cash position.
3. Finally, I believe this is a good business. It enjoys benefits including high returns on capital and owner-management, via CEO Mark Carpenter. One of the things I’m thinking about as the SIF portfolio ages is finding a route to hold onto good quality stocks for longer.
Motorpoint’s half-year results are due on 26 November. I’ll review the stock then to see if I still believe it satisfies my screening rules. But for now, I’m going to continue holding these shares.
Verdict: Hold
Total return to date: Breakeven
Daily Mail and General Trust (LON: DMGT)
(Original coverage: 07-Jan-2020)
Another company that’s issued a positive trading update recently is Daily Mail and General Trust. This unusual business owns the Daily Mail, plus data and information services, events and trade shows.
There are a lot of moving parts and it’s not always easy to understand. But the firm’s recent trading update usefully narrowed the range of market expectations:
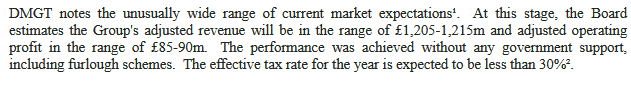
September’s profits were boosted by two elements of the DMGT group:
As things stand, DMGT still passes all of my screening tests. That means the stock automatically wins an extra month’s stay in the SIF Folio.
Given that DMGT’s full-year results are due on 23 November, these numbers will be incorporated into the stock’s data before my next monthly review. Broker forecasts should also be updated. This will give my screen a fresh set of data to digest. Until then, I’m going to keep DMGT in the SIF folio.
Verdict: Hold
Total return: -13%
Disclosure: At the time of publication Roland owned shares in all the companies listed in the SIF Folio.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Really solid sounding performance from Finsbury today at their AGM. Seem to be heading in the right direction having weathered the Covid crisis very well. SP has recovered a bit in recent days but still has plenty of recovery potential at these levels. I really can't see much of a risk to the downside, with debt falling and dividend likely to be reintroduced this year. I've added to my position this morning.
I like the angle on Motorpoint (LON:MOTR)
A major shareholder is Punchcard Capital. They are very concentrated in their investments and have some great successes.
I love reading your SIF updates Roland. They provide a fascinating insight over time into the buy/hold/sell process of a rules based system and the dilemma sometimes posed in terms of how much (if any) of our own judgement to apply.
Thanks for sharing! Some great food (perhaps not of the Finsbury kind) for thought!
Sorry but not too keen on the Ultrapharm expertise in producing gluten free food being called a ‘trend’. For those who choose gluten free as a faddish life style I have no time for but for my daughter who is coeliac the greater choice of gluten free foods available is a godsend and much of it is preferable in texture and taste to the ‘regular’ versions.
Hi Pennyledges,
Thanks for your comment. I apologise for any offence caused - I appreciate that for a number of people a gluten-free diet is a medical necessity. I can imagine that the improved choice of gluten-free products in recent years is a great benefit for coeliac sufferers.
However, I think it's fair to say that a lot of the recent growth in the gluten-free food market has been driven by dietary trends. This was the point I was trying to make.
Regards,
Roland
MOTR (Motorpoint)
Positive Points:
Possible formation of Cup and Handle pattern.
Used Car Sector has proved to be profitable due to Covid. Nobody wants to travel by public transport. How long will it last?
Owners shareholding shows their faith.
Other sources crunching same numbers as Stocko give thumbs up. Vector Vest (to which I also subscribe) computes value over 4 pounds.
Comparaison with North American KMX (CarMax) and CRMT (America's Car-Mart) plus U.K. car dealers favourable.
Negative Points:
Price to Book and Tangible Book higher than peer group.
Leased sites rather than freeholds.
Free Cash Flow per share high. This caused me some problems so did some investigation and came up with this:
Good stuff as ever Roland. I feel your pain with LON:FIF as its hard to see why its so down in the dumps. I've held my breath and bought some more recently, the Directors Wives have been buying of late which makes me wonder if there will be a return to paying a divided on the mid term horizon.
Hi Berksbee,
Yes, I've noted the insider buying recently at Finsbury Food (LON:FIF) - I would expect a return to dividends at some point in the next 12 months.
It's hard to gauge how realistic the current broker forecasts might be, but if correct the stock could provide an attractive 6%+ yield.
Roland
Beware the curse of Gnome. DMGT is a long standing "wouldn't touch with a bargepole" stock with Private Eye. They are usually proved correct eventually.
I see your point re. Daily Mail And General Trust P L C (LON:DMGT) :-) Although Lord Rothermere and the Eye aren't exactly natural allies, are they?