SIF Portfolio: A simple decision to add McColl's Retail

Opinions vary about this week’s addition to the SIF portfolio, but one thing that’s certain is that convenience store operator McColl’s Retail is officially a defensive stock. As I explained last week, the portfolio is desperately short of defensive businesses. Adding McColl’s will help improve this balance, so I was pretty chuffed to spot this new addition to my screen results this week.
McColl’s started life as a vending machine operator in 1973. The shift to convenience started in 1994, when McColl’s started converting some of its Forbuoys newsagents into food stores.
The group’s current operating brands include McColl’s, Martin’s and R S McColl. The acquisition of 298 convenience stores from the Co-op in July 2016 for £117m has put McColl’s on track to have 1,000 convenience stores by the end of this year, along with more than 400 newsagents.
To put that in context, Tesco, the largest supermarket convenience store operator, has more than 2,000 convenience stores, while Sainsbury’s has 783. However, McColl’s lack of large format stores means that it remains a relatively small business. Annual sales are less than £1bn, and the FTSE Small Cap-listed group’s market cap is just £201.3m.
Stockopedia’s algorithms rate this low-margin business very highly, with a StockRank of 98. In fact, it’s the top-ranked stock in the Food & Drug retailing sector:
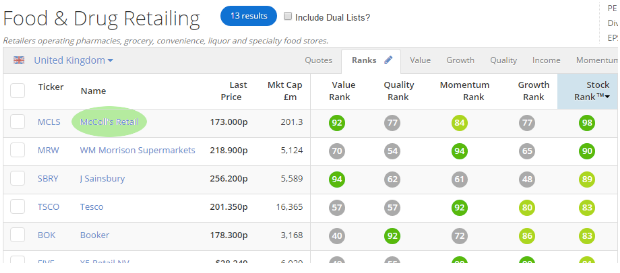 Let’s take a closer look.
A value retailer
A low-margin business like this shouldn’t have a high valuation. McColl’s doesn’t. The group’s shares trade on a trailing P/E of 11, and a trailing price/free cash flow ratio of 9. There’s also a very healthy earnings yield of 10.1% and a dividend yield of 5.8%:
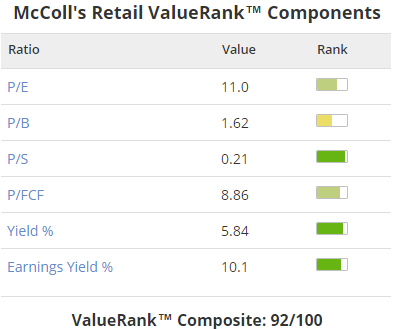
In my view, earnings yield (EBIT or operating profit / enterprise value) is a very useful ratio for judging how attractively valued a business is. By including net debt and excluding interest and tax, you get a direct view of how much profit a company’s operations are generating, relative to its total valuation.
The SIF screen requires an earnings yield of at least 8%, but McColl’s double-digit earnings yield suggests to me that it could be very attractively valued at current levels.
It’s also worth noting that McColl’s free cash flow yield of 11.3% (1 / 8.86) highlights the firm’s strong cash generation. Not only is the dividend well covered by free cash flow, but more than 100% of McColl’s earnings yield is being converted into genuine surplus cash. That’s very attractive.
There only seems to be one real weakness to McColl’s valuation, which is a lack of tangible assets. The StockReport shows a P/TB of ‘n/a’, which means that net tangible assets are negative. Looking at the balance sheet suggests two reasons for this. Firstly, property assets seem relatively low, at £64m. This is presumably because many stores are leased.
The second reason is that McColl’s has negative working capital. In other words, current assets are much smaller than current liabilities:
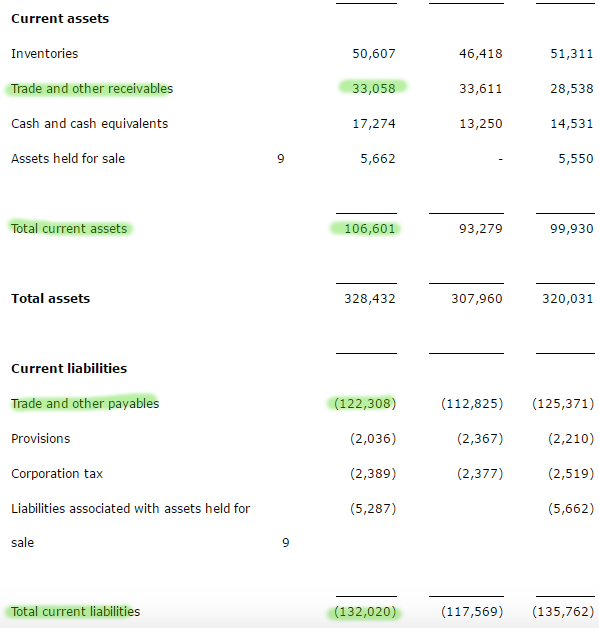 Negative working capital would be a warning flag with many businesses, but it is the norm for big food retailers. What happens is that stock is sold to customers before the retailer has to pay its suppliers. Effectively, the business is run on free credit from its suppliers!
Questions over quality?
We’ve seen that McColl’s is cheap, but are there any underlying quality problems which could be a concern for the future?
The stock’s QualityRank of 77 suggests few serious concerns, but there are a couple of points I’d like to consider.
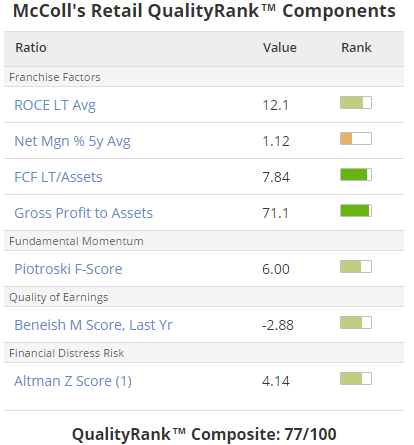
The Piotroski F-Score is heavily weighted in the QualityRank algorithm, because it’s a useful indicator of a company’s fundamental health. McColl’s F-Score of 6/9 suggests there’s room for improvement. The group has ‘fails’ in three areas:
- Profitability: return on assets has fallen from 6.5% to 5.6% over the last year.
- Rising long-term debt: The leverage ratio of long-term debt to average assets has risen from 14.8 to 17.9 over the last year.
- Productivity has fallen: The F-Score measures this using asset turnover, or the value of sales generated relative to assets. McColl’s asset turnover ratio has fallen from 3.17 last year to 2.87 during the current year.
An F-Score of 6 is the minimum required to qualify for the SIF screen. I think it’s worth watching for any further deterioration, as the next set of accounts will reflect the impact of the Co-op convenience store acquisition. McColl’s used £104.3m of debt to fund this deal, alongside £12.7m from a placing. Management expects the net debt/EBITDA ratio to rise to 2.2x next year, before falling back to 1.3x by 2020.
Net debt was £42.3m before the acquisition. So it should now be about £146m, less anything the group has managed to repay so far. This equates to nine times forecast net profit for the current year. This debt level would disqualify McColl’s from the SIF screen, which has an upper limit of five times net profit.
Concerns over debt naturally lead to questions about the safety of the group’s dividend. McColl’s has indicated that the payout ratio will fall from 60% to 50% following the acquisition. The upshot is that the dividend is expected to be flat this year, at 10.2p.
The company has already flagged up the potential to speed up debt reduction with a sale-and-leaseback programme. This would certainly be effective in the short term. But as Tesco shareholders have found out, it can have a downside in terms of future liabilities.
Overall, my view is that it would have been safer for McColl’s to have used less debt and more equity to fund the Co-op acquisition. This might have entailed a dividend cut, but would have kept debt down and protected future cash flows.
Is momentum wavering?
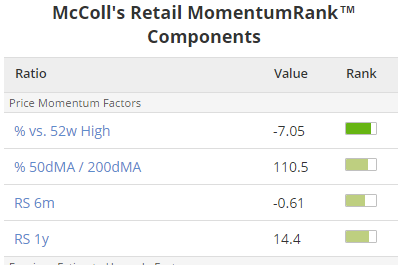
The final element of the jigsaw is momentum. McColl’s scores well, with a MomentumRank of 84. The group’s share price is within 10% of its 52-week high and other price momentum indicators are also positive.
The picture is less certain in terms of earnings upgrades. Broker consensus forecasts for the current year have fallen by nearly 6% over the last three months:
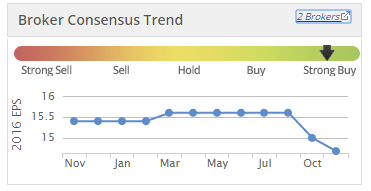
This is presumably due to the 2.0% fall in like-for-like sales reported for the first nine months of this year. McColl’s low margins and high fixed costs mean that profits are very sensitive to movements in sales.
My view
I have mixed views about the outlook for McColl’s. But the concerns I’ve highlighted are mostly subjective and predictive, whereas the positive aspects of this stock are factual and quantifiable.
In a systematic portfolio such as this one, these quantifiable factors have to take priority. McColl’s qualifies for the SIF Portfolio and helps to fulfil the portfolio’s need for defensive stocks. I’ll be adding to the portfolio some time on Wednesday, in the aftermath of the US election results!
As always, I look forward to hearing what you think in the comments below.
Disclosure: Roland owns shares of Tesco.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Hello Roland,
I see Carnival (LON:CCL) comes up in your screen, any reason why this has not been added to your selection?
Yes I agree defensives are out of favour and many have fallen back, I was looking at some the other day.
Hi Roland,
If the recent performance (post US election) of my many 'bond proxies' are anything to go by, both in individual stocks and sector specific ETFs, then the best quality defensive stocks are rapidly becoming a lot cheaper!
How do you square the decision to add the share with your observation that the debt level would disqualify it?
Hi psyche100,
Good question. The main point here is that I'm projecting (guessing!) that the debt level, when it's next reported, will disqualify McColl's Retail (LON:MCLS) from my screen. But I don't know this for certain -- cash generation might be better than expected, for example.
The rules for the SIF portfolio are that stocks are bought and sold based on meeting a fixed set of statistical rules, based on historical financial data. This process deliberately excludes human guesswork about the future. My hope is that by reducing the human element, and relying more heavily on quantitative factors, I'll be able to beat the market.
I hope this makes sense!
Roland
Many thanks for the reply - I see what you mean now. I'm tempted to buy as I also have very few defensives in my portfolio. However, I'm put off by the asset growth effect http://wwwdocs.fce.unsw.edu.au/banking/seminar/2008/ExplainingBooktoMarketandAssetGrowthEffects.pdf
- given the recent acquisition which will bump total assets up significantly.
Are there any other defensives which meet your criteria?
Defensives are thin on the ground in my screen results, hence my enthusiasm when they do become available.
http://www.stockopedia.com/screens/stock-in-focus-screen-113218/
My view is that many of the best quality defensive stocks are too expensive to buy at the moment. Such companies have benefited from becoming so-called bond proxies -- investors have bought them for their supposedly safe yield, pushing prices up to record levels.
Regards, Roland
My impression of McColl's Retail (LON:MCLS) is that those of their stores I've visited have been very poorly maintained so I'd be analytical about whether "shock horror" the former PE owners had skimped on this area, at first sight It concerns me as my local store is great example of property neglect, peeling Lino gaffer taped to the floor and suspended ceilings that are stained and wonky,
looking at the interim numbers they appear to be reporting lower capex from 2014 to 2015
http://www.mccolls.co.uk/media/18745984/2016hy_investor_presentation_final.pdf
...while store numbers were increasing and new formats being rolled out? so given how wafer thin margins are and how many are leased dilapidations could be an iceberg, a bit like Moss Bros perhaps?
Anyway not for me as margins too low and debt way too high
Hi rhomboid1,
Thanks for your comment. Personally, I agree that future lease liabilities and capex could prove to be higher than expected. I have a suspicion that sale-and-leaseback has already been used fairly generously to help fund growth. I can't be sure of this without further investigation, but it's interesting that the Property/Plant/Equipment line of the balance sheet has hardly risen since 2011, despite a significant rise in store numbers.
However, as I've said before (!), this portfolio is about relying on the Stockopedia data, rather than our own projections or opinions. Time will tell if I'm able to make a success of this approach.
Regards,
Roland
The receivables appear to be more interesting than you note.
Firstly - why does McColl's have any receivables? In the circumstances £33m seems remarkably high.
But then, using the Stockreport, look at the year end balances, they are a fraction of the interim balances. It is the sort of thing which sends me off to the actual annual report.
Aislabie,
Interesting question! I've had a look at last year's annual report and it seems that as with the big supermarkets, the bulk of receivables are supplier rebates. There's also a decent chunk of prepayments/accrued income. I'm not sure what this is, perhaps it relates to the Post Office branches?
I can't see anything here that concerns me, but I'm happy to be corrected if I've missed something.
Regards,
Roland