SIF Portfolio: I'd like to bend the rules for Carr's Group

A more experienced and successful investor than me once said that he didn’t like to look too hard for new stock ideas. If they didn’t come onto his radar, they probably weren’t worth pursuing.
That’s not an approach that will work for everyone, but it has worked quite well for me over the years. I think another way of looking at it is that it is often best to restrict your investments to stocks and situations with which you’re familiar. Hunting down obscure ‘opportunities’ outside your normal investment universe can end badly.
One company that’s appeared on my investment radar over the last few months is agricultural feed and engineering conglomerate Carr’s Group.
The stock fell by 15% in one day in March after a profit warning. But the shares have bounced back nicely and are now pretty much flat on a year-to-date basis. The firm’s interim results in April didn’t reveal any nasty surprises, and nor did July’s trading statement.
In the meantime, Carr’s has come within a whisker of qualifying for the Stock in Focus screen. As things stand, the stock falls short in just one area:

Earnings yield (EBIT/EV) is one of the most important metrics in my screen. My bias as a value investor means that I like to buy stocks where the company’s earnings are going cheap. Comparing operating profit with enterprise value (market cap + net debt) is a neat and effective way to do this, in my view.
However, I estimate that the share price would only have to fall from the last-seen level of 145p to 139p to qualify for my screen. Arguably that’s too small a gap to worry about, especially as the spread on this stock varies widely, and can be significant. Minimising the spread could be more profitable than waiting for the price to fall, in terms of future returns.
My challenge this week is to decide whether to bend my rules slightly and add Carr’s to the SIF portfolio.
Is Carr’s really a Super Stock?
As regular readers will know, the SIF portfolio is a rules-based portfolio. So if a stock passes all my screening tests and meets my diversification requirements, it’s likely to end up in the portfolio.
I don’t choose stocks based on their StockRank, but as it happens, Stockopedia’s computers also like this stock. Carr’s is currently ranked as a Super Stock, with a StockRank of 92. Statistically, a basket of shares which are ranked in this way have a better-than-average chance of outperforming the market.
What about the story?
I’m learning not to worry too much about each stock’s underlying story when picking stocks for the portfolio. But in this case I think it’s worth mentioning why Carr’s could offer some upside.
In his review of July’s trading update, small-cap editor Paul Scott described the Carr’s as “a boring, ex-growth, low margin business”.
I can see this version of the story. The group’s agricultural feed business can only really grow by acquisition and sector consolidation. Carr’s engineering business is going through a difficult patch.
However, I see this as something of a contrarian opportunity. The engineering division has considerable exposure to the nuclear and oil and gas sectors. Several of the company’s businesses manufacture parts and equipment for oil and gas firms.
In July, the company said that “pressures in the oil and gas market … are predominantly impacting margins”. No surprise there. What may surprise you is that the group also reported “high” factory throughput with “a steady pipeline of opportunities building”. A delayed contract has now been signed and will deliver over the next two years.
Earlier this week, Carr’s also announced the acquisition of a nuclear engineering firm in the US. Management expects this to open up access to the US market and create cross-selling opportunities.
Let’s stick to the facts
My bullish view of the outlook for Carr’s engineering business may be incorrect. But what’s more certain is that the group’s financials score highly across a range of metrics:
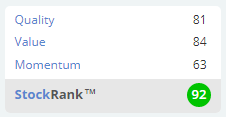
With Quality and Value scores of more than 80, I believe shareholders are likely to be reasonably well protected if business conditions remain tough. Let’s take a closer look.
Quality: One of the most heavily-weighted factors in the QualityRank calculation is the Piotroski F-Score. This fundamental health score compares nine ratios with the prior year period to measure changes to profitability, leverage and efficiency. A high score eliminates many of the more common risks which can result in a loss of shareholder value.
Carr’s scores highly, with an F-Score of seven out of a possible nine:
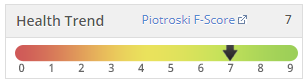
It’s worth noting that the loss of two points is due to marginal worsening of the company’s current ratio and gross margin over the last year. I don’t see this as a serious concern.
The group’s other attraction, in my view, is that its return on capital employed (ROCE) has averaged a respectable 11.2% over the last six years. Although this isn’t outstanding, the group’s net gearing is low, at just 12%. So improvements to profitability should feed through directly to shareholder returns, rather than being absorbed by debt liabilities.
Value: I wouldn’t want to pay too much for a conglomerate business like this. Investors focusing on the forward P/E of 17 and 2.7% yield may argue that these shares are already too expensive. However, a look at the ValueRank breakdown suggests a more balanced view, with some attractive qualities:
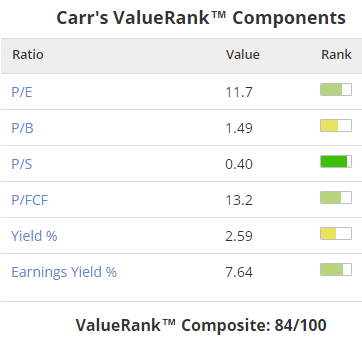
I’ve already mentioned the appeal of Carr’s earnings yield, which is close to my threshold of 8%.
What I also like above these figures is the trailing price/free cash flow ratio of 13.2. This is reasonable in itself and also closely matched to the trailing P/E of 11.7. Although the lumpy nature of capital expenditure means that free cash flow won’t always match earnings, I see it as a sign of quality when the two are closely matched.
Momentum: Carr’s MomentumRank of 63 is the weakest of the three scores, but it’s hardly a disaster. Earnings forecasts for 2017/18 have edged higher over the last month, and the decline in 2017 forecast earnings appears to have been halted following July’s in-line trading statement.
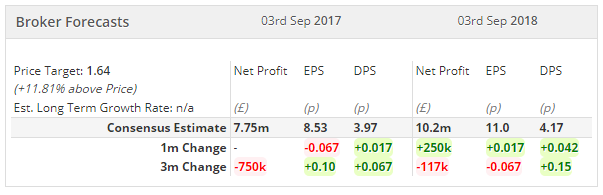
I don’t see any major cause for concern in terms of the stock’s momentum.
My decision
I’ve decided to bend the rules slightly and add Carr’s Group to the SIF portfolio.
I hope my decision hasn’t been influenced too highly by my personal view on the stock. But if you think otherwise, feel free to let me know in the comments below!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Many thanks Roland
John
I see the Screen for this offers 177 companies. I am new to this but what other criteria are you using to cut the choice of portfolio down to such a small selection?
Hi John,
The screen I am using is my own Stock in Focus screen. You can see the current results and the criteria I use here:
http://www.stockopedia.com/screens/stock-in-focus-screen-113218/
26 stocks qualify at the moment, many of which you will see are in the SIF portfolio:
http://www.stockopedia.com/fantasy-funds/stock-in-focus-portfolio-6449/
Regards,
Roland
I don't really understand the attraction, not sure why you are bending the rules to include Carr's (LON:CARR). If you exclude the Earning Yield rule you will get many new companies, that's why most of the ones I tested failed on. I'm with Paul on this one, low margin, already had 1 profit warning this year, I can see things could go wrong again, animal feed is a fickle business. Carr's (LON:CARR) also fails on spread today.
How about Synthomer (LON:SYNT) that has Earn Yd of 7.98%
I can't get my head round the logic of combining an animal feed business and a nuclear / petrochemicals engineering business. At the least it makes valuation difficult and probably means the whole is valued at less than the sum of the parts.
From Technical Analysis point of view: rising Higher Los since April.
Support 144p.
Do not want to pay more. May have to because of spread.
I think the nterested to see how Carr's works out for you. I was a holder but was already considering selling when the profit warning happened in March so I ditched them then. I got sceptical basically with the levels of capex combined with a fairly lacklustre ROCE and margins and also the fact that the dividend always looked well covered by earnings but not by free cashflow, so there wasn't much prospect of it growing. It looked like a business that required a lot of cash investment but didn't generate great returns.
They have made some acquisitions in the robotics space so there could be some upside if that is successful.
Hi Hot Socks,
Definitely agree that there are downside as well as upside risks with Carr's (LON:CARR).
Capex seems to have fallen in recent years while free cash flow has improved. It will be interesting to see whether this has any apparent effect on the outlook for growth. I'm broadly positive on the firm's strategy of making small, targeted acquisitions, but it's not without risk.
We'll have to see what happens..
Regards,
Roland