SIF Portfolio January review: IGR, TOT, CAMB & PAF

My Stock in Focus screen is throwing up slim pickings at the moment. All five of the qualifying shares at the time of writing are already in the portfolio. I’m hoping for more choices next week. As this will be the last SIF portfolio article published in January, this week’s focus will be the portfolio’s monthly review.
There are four stocks up for review this month, each of which has spent at least six months in the portfolio. (Each company name is linked to my original article on the stock):
- Gift packaging and greetings firm IG Design
- Fresh producer group Total Produce
- UK car dealership group Cambria Automobiles
- African gold miner Pan African Resources
IG Design, Total Produce and Cambria Automobiles have now been in the portfolio for six months, so are due for review. Pan African Resources has been held for longer, so is kept under review each month.
IG Design
Giftware group IG Design had a StockRank of 97 when it joined the portfolio in July. It also qualified for the Jim Slater ZULU Principle, Naked Trader-esque and Value Momentum screens. All three of these have delivered annualised returns in excess of 20% since their inception, so my hopes were high for a solid performance.
IG Design hasn’t disappointed and trading has remained strong. The shares have risen by almost 50% following in-line trading updates in August and January, and upgraded guidance with the interim results in November. Paul Scott was impressed on both occasions and commented that the group might continue to grow into its valuation.
I share Paul’s view that this is a good company with good management, but this stock has now been in the portfolio six months and dropped out of the SIF screen. As a result, I’ll be selling it from the portfolio this week, in accordance with my rules.
One interesting point is that IG Design’s StockRank has fallen to 75 since it joined the portfolio. The shares now trade on 16.9 times current year earnings and the yield has dropped below 2%. Is the StockRank forewarning us that the value is already in the price? It will be interesting to see how the shares perform over the next six months.
IG’s share share price has risen by 48.5% since it joined the portfolio. Shareholders would also have received dividends totalling £470 in December, which adds an extra 1% to the total return.
Verdict: Sell
Total return: +49.5%
Total Produce
It’s fair to say that fruit, veg and flower producer Total Produce wasn’t my most popular pick when it joined the SIF Portfolio in July. This £500m Irish company has its main listing on the Irish stock exchange. The group’s LSE dual listing is on the AIM index, so it doesn’t get much coverage in the UK.
Interestingly, Total Produce was the first dual-listed stock I purchased after deciding to lift my blanket ban on stocks without primary UK listings. I’ve extended this policy recently with two Russian stocks. I’m hoping they perform as well as Total Produce has done!
Total Produce has proved to be a stealth performer during its time in the portfolio. The shares have risen fairly consistently and are now worth 27.4% more than they were six months ago:
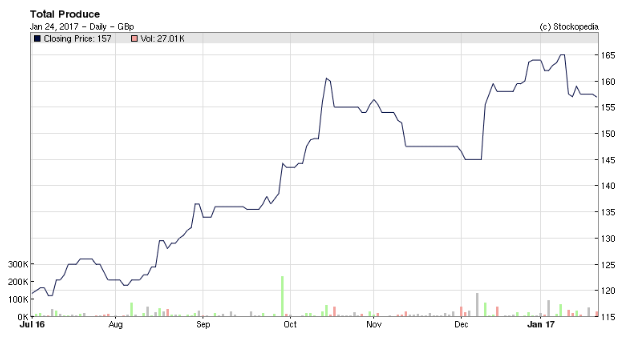
The only update we’ve had on trading during this period was Total Produce’s interim results in August. These showed a 10.4% rise in sales and a 15.1% increase in adjusted pre-tax profit. Full-year earnings guidance was upgraded slightly to the “top end of the previously announced range”.
Total Produce impressed me with its high earnings yield, 10% average ROCE and strong free cash flow. All of this is achieved in a business with an operating margin of less than 2%, proving that profit margins do not always equate to returns.
As a matter of interest, this stock has fallen out of my screen for two reasons. The first is that the rising share price has pushed Total Produce’s earnings yield slightly below my 8% threshold. The second is that eps growth is expected to fall to just 2.9% this year.
Verdict: Sell
Total return: +28%
Cambria Automobiles
Car dealership group Cambria Automobiles joined the SIF Portfolio in the wake of the Brexit selloff. So I was reasonably hopeful that it would benefit from a gradual recovery over the six months that followed.
That hasn’t happened and the outlook has deteriorated recently. Cambria’s StockRank of 92 has fallen to 59 over the last six months, and the group’s recent AGM trading update warned of tougher conditions this year.
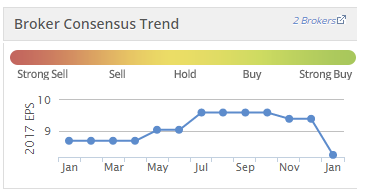
Brokers covering Cambria took this message as a cue to cut their forecasts for the current year. Consensus eps forecasts have fallen 12% this month:
Personally, I’m in two minds about car dealerships at the moment.
Cambria appears to be a well-run, cash-generative business that’s trading well. The shares look cheap on a P/E of 7, and chief executive Mark Lavery owns about 40% of the stock. It’s probably fair to assume his interests are well aligned with those of shareholders -- with one exception.
I’m willing to bet that Mr Lavery’s outlook is rather more long term than most investors. After all, Cambria is his day job, and pays him a (very) handsome salary. For him, it’s worth taking a 5 year view and riding out any possible downturn.
However, the new car boom has been fuelled by cheap credit and now appears to be slowing. On this basis, I’m not sure the long view makes so much sense for the rest of us.
Cambria has fallen out of my screen and is now due to be sold. The portfolio’s holding in Cambria is currently showing a small loss, which is partially offset by £535 of dividend income.
Verdict: Sell
Total return: -4.1%
Pan African Resources
Gold miner Pan African Resources has won several stays of execution. Originally purchased in May, this AIM-listed South African group is currently the longest-serving stock in the portfolio.
As I suggested might happen, gold and gold miners have enjoyed a modest rebound in recent weeks. This has lifted the portfolio’s holding of Pan African back into profit. The stock has also contributed a healthy £2,957 of dividends during its stay in the portfolio, doubling the stock’s total return.
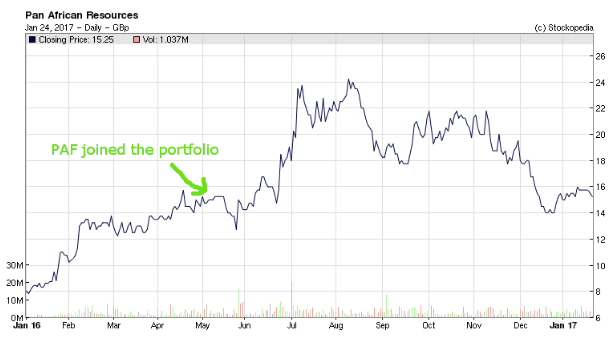
Pan African failed to hold onto the big gains seen in July and October.
I personally have no view on where the gold market is heading. But the complex mix of currency and speculative factors which drive the price leaves me feeling uncertain.
Pan African still looks cheap on current forecasts, with a forward P/E of 6.2 and a prospective yield of 5.6%. But Stockopedia’s computers are cooling on the firm, whose StockRank has fallen from 98 in May to 70 today.
Verdict: Sell
Total return: +10.4%
I’ll be back next week, hopefully with a new stock to add to the SIF portfolio. Until then, I look forward to your comments on this week’s disposals!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Re: PAF
The style of PAF announcements is akin to someone telling you in funereal tones you have won the Lottery. You're not sure if you have been told good news or bad!?
I suppose it makes change from AIM hype.
It seemed to me that PAF announced positives in increased production, currency gains, share reduction, and gold price received during the period. Muted reaction maybe a result of the lack of PR hurrah in the RNS and a wary look by the market at the forward price of Gold. But I can't help feeling the market has missed something substantially positive
Sorry Student - meant to hit the up button but slipped/missed
I hold Cambria Automobiles (LON:CAMB) as I think it's a well run business at a very reasonable valuation. I think there's some protection to the downside due to the after sales profit and tangible asset backing. The impact that cheap credit has had on the market in recent years is interesting and I feel there's too many variables to model the impact the unwinding of this will have on dealers. I do feel that the impact of the predicted slowdown will hit manufacturers harder than dealers though as even in a reduced market, the dealers will continue to perform an essential service on behalf of the manufacturers.
I'm interested in what has driven the reduction in the Stockrank over the last 6 months?
A little harsh on timing of trading update, the August update was at the same time - I think this more likely to SA listing. As already mention the content of the update looks strong and the recent coal purchase encouraging.
Pan African Resources (LON:PAF) just issued an "in hours" trading update, so some might have missed it.
http://www.investegate.co.uk/pan-african-resources-plc/paf/trading-statement/20170127103000P7304/?fe=1&utm_source=FE%20Investegate%20Alerts&utm_medium=Email&utm_content=Announcement%20Alert%20Mail&utm_campaign=Pan%20African%20Resources%20PLC%20Alert
It's usually a bad sign when this happens although the key indicators all seem to be well up. However, the commentary/significance of the ZAR/£ currency movements leaves me a bit perplexed, echoing Roland's point above about the import of this factor.
Gus.
Yes thanks for that, i missed it. Why is it late? Not good. Actually the figures look ok but could have been expressed better I feel.