SIF Portfolio: Lessons learned and a new stock (XLM, PLUS)

StockRanks 1, stock picking 0.
At least that’s the lesson so far from my decision in May not to add XLMedia to the SIF portfolio, despite its then StockRank of 99.
If I’d accepted the wisdom of the Stockopedia algorithms and hit the buy button, I’d have enjoyed a 32% return before dividends in less than five months. But I thought I knew better! Ironically, it was my understanding of XLMedia’s business model that left me sceptical about the durability and quality of its earnings.
Tuesday’s interim results from XLMedia prompted me to take a fresh look at this stock. Revenue rose by 39% to $51.2m during the first half, while pre-tax profits were 20% higher at $15.8m. Net cash and short-term investments were flat at about $42m, enabling the group to increase the interim dividend by 47% to 3.82 cents per share.
Organic expansion into new territories (mainly the US) and acquisitions have enabled XLMedia to deliver significant growth. Management are “extremely confident of meeting profit expectations for the full year”. These put the stock on a forecast P/E of about 11.8, with a yield of around 4%. Stripping out net cash reduces the effective P/E to just 9.7.
So was I right to ignore my screen results and avoid XLMedia? In the short term, obviously not. Over a longer period, I would still argue that XLMedia’s earnings and margins may be vulnerable to external changes.
But the SIF Portfolio isn’t a long-term buy and hold portfolio. Stocks are selected based on a set of screening criteria, and all holdings are reviewed after six months. Within this framework, I should have bought XLMedia.
A psychological risk?
I don’t feel too bad about missing out on XLMedia. As an experienced investor once told me, it’s important to remember that there’s always another stock that’s about to rise.
I hope I’ve learned from this mistake -- but I’m wondering if my decision to avoid XLMedia could affect my future decisions. Will I end up overcompensating for this missed opportunity by taking more risk in the future?
It’s a relevant question for me this week, as the stock I’m going to add to the SIF Portfolio is CFD provider Plus500. In my view this company is cast from exactly the same mould as XLMedia. Both are:
- AIM-listed Israeli tech stocks
- Still cheap despite strong financials and proven cash generation
- Exceptionally profitable marketing businesses
- Dependent on attracting high numbers of new users
- Controlled by insider shareholders
- Both have put themselves up for sale at much lower share prices
Can Plus500 continue to deliver?
Plus500 has become far bigger and more profitable than most investors expected.
Even the firm’s board may be surprised. In June 2015, Plus500’s controlling shareholders were happy to accept an offer of 400p per share from Playtech. That bid failed to gain regulatory approval, but the shares have since doubled.
Founding shareholders don’t usually undervalue their businesses to this extent when cashing out. I’d like to know why Plus500’s board was so keen to accept this apparently modest offer.
One man who doesn’t seem to have been troubled by this question is hedge fund heavyweight Crispin Odey. Odey Asset Management built up a 25% stake in Plus500 following the firm’s regulatory troubles in 2015. Although Odey has recently taken some profits, the firm’s stake is still over 19%.
Stockopedia’s computers also remain keen on this stock. Plus500 has a StockRank of 99 and qualifies for no fewer than seven of Stockopedia’s Guru Screens. Among these are the Dreman Low Price to Cash Flow Screen and the Value Momentum Screen. Both of these have delivered annualised returns of about 18% since inception.
The weight of statistical evidence suggests Plus500 could have more to offer. Let’s see how the numbers shape up.
What’s changed?
The last time I wrote about Plus500 was in November 2015, shortly after Playtech’s offer for the firm failed due to regulatory concerns. Back then, Plus500 had a StockRank of 91. Today’s it’s 99. But what’s more interesting is how the firm’s scoring profile has changed over the same period:
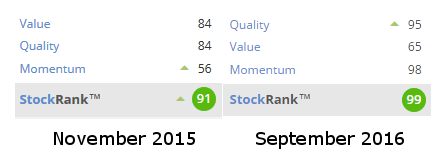
Last year, Plus500 had high value and quality ranks and a lower momentum rank. This is the classic profile of a contrarian stock.
Fast forward to today, and the picture has changed. Plus500 has high quality and momentum but a lower value rank. This is the profile of a high flyer. These are stocks that can deliver terrific multi-year gains, but can also crash horribly if things start to go wrong.
However, while most high flyers become very expensive as they grow, Plus500 hasn’t. Its value rank of 65 is only low relative to its very high quality and momentum scores.
Plus500’s StockRank of 99 suggests to me that Stockopedia’s algorithms rate Plus500 as more of a super stock than a high flyer. A company that’s good, cheap and improving, with the potential for big gains.
Strong trading?
Comparing Plus500’s interim figures with those I’d have looked at last year seems to support this view. The group’s operating cash flow rose by 40% to $36.8m during the first half, while earnings per share rose by 11% to $0.39.
Net cash has fallen from $156m to $96m since the end of last year, but that’s only because the group paid out $96m in dividends during this period. Free cash flow was $35.4m during the first half, representing 79% of post-tax profits for the period. That’s pretty healthy.
Operationally, the picture is slightly more mixed. Average revenue per user (ARPU) rose by 12% to $1,525, but the average user acquisition cost (AUAC) rose by 28% to $1,328. Plus500 says this is a result of the firm attracting higher value customers. The firm says this is helping to increase market share. This is a sensible goal, as higher value customers should help drive medium-term ARPU growth and reduce Plus500’s dependency on new customers.
Strong outlook
Plus500 reported good third quarter trading in its interim results and expects “strong growth in 2016”. The latest broker forecasts suggest this should equate to earnings per share of $0.94, 12% more than last year. The total dividend payout for the year is expected to be 27% higher, at $0.65 per share.
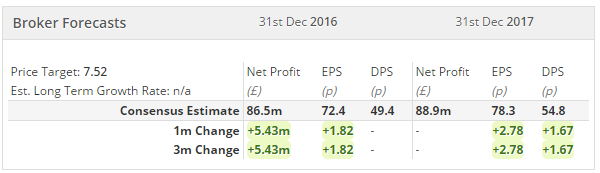
These forecasts give Plus500 stock a forecast P/E of 10.4 and a prospective yield of 6.5%. Further growth is expected next year.
This modest valuation is too tempting for me to ignore, so Plus500 will join the SIF Portfolio this week.
If you bought Plus500 after the Playtech bid fell through and are now sitting on big gains, what are your plans? Are you letting this one run, or do you feel it’s time to take profits? I’d love to hear your thoughts.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
XLM up ten per cent since Roland's original post a couple of weeks ago, hitting 100p yesterday. The interims warranted it. Next issue is the tricky transition that seems to happen when a share price has to move over a pound level, though, and stay there.
Most people have concentrated on Plus500 in their comments, but I'm more interested in XLMedia.
Like Roland I've watched XLMedia for a while, two months in my case, before, unlike Roland, finally buying last week and I added again a couple of days before the interim results. Only about a grand's worth which is nothing for most people on here, I know but for me it's a top-end buy.
The concern I had holding me back before was not the niche it was trading in or how susceptible it was to regulatory change or pricing events, or that less than 50% of shares are held by outside investors but the fact it was a foreign company listed on AIM. It seems to be negotiating forementioned risks of regulation and pricing pretty well and I don't mind the founders being highly invested in the share-price. I prefer that to them not holding any shares and gifting themselves a ton of ridiculously cheap options which they will collect on later.
I've held shares in Paysafe, GVC and Safecharge and in comparison XLM looks seriously under-valued - or perhaps more accurately, unloved. It's so hard to find cheap growth shares! For various reasons the market is clearly not interested. By any reasonable assessment of the financials the price is and has been very low. It has to be said, it may always remain comparatively low as the factors that scare people off probably won't be changing. I'm hoping despite the low valuation great results will just keep inching the price up anyway and in the meantime there's a fast rising, decent dividend.
As for AIM-FoF (fear-of-fraud), who knows? For me the decision to put money in was made after watching several online videos of CEO Ory Weihs pitching the company (what it does and how it does it) - he just didn't strike me as a crook. I may even be developing a bit of a man-crush. (I've stopped watching them now.)
Berenberg initiated coverage today with a target of 130p, while Liberium reiterated 111p two days ago.
That's a cool bit of top slicing by the founders today at £100M, good for them. Also a good time to buy on the dip since the company remains trading just the same.There has been some big purchases all ready.The other thing is that it will be more undervalued today than yesterday.
I am surprised that you were not delighted to go in today and buy at a healthy discount Rowland.
I don't think that anyone doubts the ability of Plus500 (LON:PLUS) to generate strong results in the short term, what the debate is over is how sustainable that business is in the long term. The founders certainly seem to have hedge their bets somewhat with yesterday's placing.
You have to either believe that they are more technically brilliant than the competition hence their ability to grow revenue and profits very rapidly and at higher margins or they are not hedging client positions and are better at finding inexperienced clients who are willing to trade losing products. (Competitors like IG Group (LON:IGG) are very keen to point out that they don't trade against client positions.) If the latter is closer to the reality then there are two potential problems:
1. They need an ever greater stream of losing clients to maintain their growth.
2. Their products where customers are much more likely to lose risk facing increasing regulatory scrutiny, particularly when they are based in a jurisdiction that has a problem with poor quality providers of these products.
Understanding these issues is key to understanding the value of Plus500 (LON:PLUS) not just looking at the accounting figures.
dangersimpson,
Thanks for your comment. You've exactly reflected my own reservations about Plus500 (LON:PLUS). How can it be so much more successful than IG Group (LON:IGG) without adopting a more risky/short term approach to the business?
I'm not sure many people outside the business know the answer to this question. But to date, the company's financial performance has been impressive, hence my numbers-based decision to add the stock to the SIF portfolio (which is not a long-term buy and hold portfolio).
It's not a stock I'd buy as a long-term investment, but I'm not overly concerned by yesterday's placing.
Founder placings are fairly normal (think £JE, Moneysupermarket.Com (LON:MONY), etc) and don't necessarily indicate impending doom. If I was the founder of a company whose value has risen by more than 400% since its flotation three years ago, I'd want to lock in some of those gains too!
Regards,
Roland
Interestingly, they did a very similar share placing on 27th February 2014, only this time there were more shares, 20 million shares sold at 500, a discount of 11.5% to the previous share price of 565p. This represented 17.4% of the issued share capital.
Thereafter, for the next year every update was ahead of expectation (2.4.14, 1.7.14, 22.10.14) or in line with expectations (13.8.14)with strong results 25.2.15.
Then two NEDs bought small share holdings above the 500 placing 22.12.14 at 565 and 27.10.14 518.
This placing represents less sale of capital 13% leaving them with 22%.
It looks a similar desire to liquidate some cash from the business. You can't buy bread and wine ... or nice cars with shares.
I just thought this history helpful, and relevant.
Equally, historically the comparatives were easier to exceed. They are now paying more for customer acquisition. So going forward the picture may not be so rosy ... unless they develop the new markets they mention in the last RNS.
Large placings needn't always spell disaster - the accesso Technology (LON:ACSO) Directors placed 9% of their company at a discount of just 3.4% back in April.
Conversely however it took a discount greater than 8% to shift a Director share sale of 5% of SuperGroup (LON:SGP) in February.
The problem for Berenburg/Liberum in placing 13% of Plus500 (LON:PLUS) is the company's narrow shareholder list - just four large shareholders: JP Morgan, Brighttech, Odey & Morgan Stanley.
Likely these four will demand a 10% discount (675p)... guess we'll find out tomorrow morning. Could be an opportunity for us private investors.
PJ,
Looks like the discount required was slightly larger -- this morning's RNS shows that the Plus500 (LON:PLUS) shares were placed at 650p. That's a fairly hefty 13% discount to last night's close.
http://www.investegate.co.uk/plus500-ltd--plus-/rns/completion-of-placing/201609290700111455L/
It will be interesting to see the next trading update. Based on last year's reporting schedule, Plus500 should issue a Q3 update in mid-October.
Regards,
Roland
Well I think this illustrates more that Stockrank are sometimes right and sometimes wrong, it's just a case of is it right more often than the human stockpicker.
Take Mitie for example Stockrank on 7th March of 81 and increasing, and increasing Momentum and pretty good quality rank of 79, share price approx 296p. At the time of writing this Mitie has now fallen to a Stockrank of 56 and falling, with Momentum 4 and falling following a profit warning, share price 183p. That's a drop of 38%
In that particular case the Stockrank algorithms were not able to detect that the financial performance was not on solid foundations. The company seems to be laying the blame at the door of a squeeze on the business with the public sector. I think that we all could have looked at it and taken the view that there was a strong headwind for this stock due to the pressure on public sector budgets. Some would have taken the view that the company had been living perfectly happily with the headwinds and invested, others not, but the Stockrank could not know either way.
Hi Graham,
My comments about StockRanks versus stock picking were a little tongue-in-cheek, really. The StockRank system is intended to highlight baskets of shares that are statistically likely to outperform as a group.
StockRanks aren't intended as a tool for individual stock picking -- individual stocks with high ranks may underperform, just as lowly-ranked stocks may outperform.
Regards,
Roland
Hi Roland.
Looks like you're going in the door just as the founders are heading the other way. After hours RNS just released to the effect that they are placing 37% of their 35% overall holding (about 15.5m shares) into the market to "allow them to diversify their investment portfolios".
http://www.investegate.co.uk/plus500-ltd--plus-/rns/proposed-placing/201609281646581297L/
Possibly telling us something about the insiders' view on the prospects for the share price from here? Interested to see how the share price reacts tomorrow morning.
Best,
Gus.
Gus,
I've just seen the placing RNS too. Great timing! Obviously I didn't know this would happen, but it does tend to confirm my gut instinct -- I wouldn't personally invest in Plus500 (LON:PLUS) at this point. However, the point of this virtual portfolio trade was to ignore gut instinct and take a quantitative approach.
The diversification argument is (probably) also a valid one. After such strong gains, Plus500 (LON:PLUS) may well account for a very high proportion of these gentlemen's net worth. They will still be heavily invested in the stock.
Finally, it's also worth noting that given the valuation and yield, Plus500 doesn't need to deliver outstanding growth to be a profitable investment. The dividend yield plus modest earnings growth would be enough.
Agree that it will be interesting to see what the market makes of this.
Regards,
Roland
Fortunately Plus 500 has delivered an abundance of good consistent rising dividends with more to come this November for me over the last few years. These can be re invested of course giving the magical compound interest effect in a Sip.
However the annuity rates for pensions right now are the worst since I can remember. From Money Observer this October has an article showing BAE Systems pension had liabilities worth more than 180% of it's market cap at 2015 year - end.
The largest FTSE 100 company deficits top 3 are BT with £7583 billion, Tesco £4,842billion & BA Systems with £4,522.
Also another article shows that to produce an income of £1,000 per month would take a fund pot of £350,000 @ a yield of 3.5%, £300,000 @ a yield of 4%, and £260,000 @ 4.7%..
The easy way to compare XLM with PLUS 500 is to simply hit the chart button above for XLM and compare it with plus 500 or any other share.
You have made a wise choice Rowland.Well done for your article.