SIF Portfolio: Should I put on a show with Avesco?

Small cap audio visual presentation group Avesco has risen by nearly 150% over the last year. It might have made an appearance in the SIF portfolio before now, were it not for the group’s small size.
However, the shares have surged higher since 1 September, when Avesco said profits were likely to be “comfortably ahead” of expectations this year. This has pushed Avesco’s market cap up to £53m, above my screen’s £50m threshold.
Despite these gains, the shares still look attractively valued to me. Avesco has been trading well and Stockopedia’s computers are keen, too. Avesco has a StockRank of 99.
What’s the story?
Avesco has four main operating companies. These provide audio-visual services and equipment for live events, corporate presentations and broadcasters. The main source of both revenue and profit is the Creative Technology or CT division. This provides audio-visual solutions and technical staging for major events all over the world, such as Wimbledon, the Olympics and major music tours.
The big screens, clever lighting and computer-generated effects you see used on live television and stage sets may well be provided by Avesco’s CT division. This is an area where I’d imagine long-term growth potential is strong. The scale and complexity of this kind of thing seems to increase every year.
CT generated 80% of revenue and virtually all of the group’s profit last year. This may cause you to wonder whether Avesco’s other businesses are pulling their weight or merely dragging down the group’s return on capital.
In at least one case, the answer is that it’s a drag -- and it’s going. You might expect Fountain Studios at Wembley -- which hosts the X Factor among other primetime glories -- to be a profitable business. But Fountain made a trading loss of £0.1m in 2015 and only broken even in 2014.
Avesco rightly decided that this business was generating an unacceptably low return on capital, especially when compared to the freehold value of the land and buildings it owned on the site. The good news for shareholders is that these assets were sold for £16m earlier this year, generating £13m of cash and a profit of £6m. The cash was used to reduce debt and Fountain Studios Wembley is now due to close early in 2017. Although I feel sympathy for the employees affected by this closure, this looks like a sensible decision.
Avesco’s two other businesses are Presteigne Broadcast Hire and mclcreate. Presteigne provides hire equipment to broadcasters, while mclcreate provides full service solutions for exhibitions and other such events. Trading has been poor at both firms but Avesco is -- for now at least -- redoubling its efforts to attract new clients and improve profitability.
Value: A sea of green?
As Paul Scott commented in his report on 2 September, the StockReport for Avesco is a sea of green:
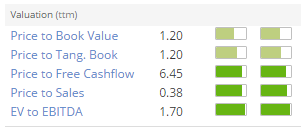
This translates into an outstanding ValueRank of 95:
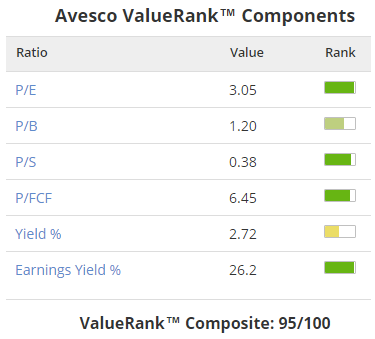
However, all is not quite as it seems. These trailing figures appear to include the benefit of the £16m sale of Avesco’s Fountain Studios site, which was included in the group’s interim results. This is clearly an exceptional item that’s big enough to distort the figures.
To get a clearer picture, I’ve stripped this out to calculate underlying trailing figures:
- P/E: 15.2
- P/FCF: 6.9
- Earnings yield: 11.6%
These figures aren’t quite so outstanding, but they’re still very attractive, in my view. Note how strong free cash flow has been over the last year.
I’m also encouraged by the asset backing on offer here. Avesco reported net assets of 230p per share in its interim results. That gives a price/book value of 1.2, which suggests that the group’s assets could provide some downside protection during periods of weaker trading.
Finally, Avesco’s trailing dividend yield of 2.7% is respectable for a small cap. The payout has grown by an average of 22% over the last five years and the interim dividend rose by 25% this year. Given the group’s strong balance sheet, what’s not to like?
A display of quality
Avesco’s QualityRank of 87 is less likely to have been distorted by the one-off gain from the Fountain Studios disposal. The main highlights here are the group’s high Piotroski F-Score and the profitability of its assets. This shows up both in terms of gross profit and free cash flow:
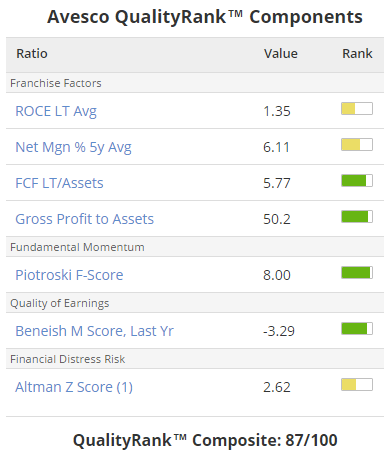
The one question mark here is Avesco’s return on capital employed, which has averaged just 1.35% over the last five years. Looking at the StockReport, the group’s historic profitability has been quite inconsistent:
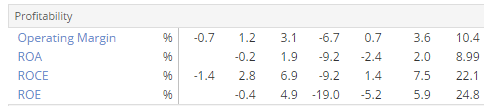
However, the growth of Avesco’s CT business and the sale of Fountain Studios gives me confidence that future returns will be more consistent.
This should be made easier by Avesco’s balance sheet, which looks very strong following the Fountain Studios sale. Cash from the sale was used to reduce long-term debt from £14.8m to £9.5m, and lift the group’s cash balance from £12.7m to £22.7m. As a result of these changes, net debt fell from £17.5m in October 2015 to £3.3m at the end of March.
Judging from the number of high profile events at which it works, Avesco has a fairly strong reputation in its key markets. The increasing scale and sophistication of the technology involved in such work suggests to me that the biggest players will be able to take market share from smaller competitors over the next few years. I’d expect Avesco should be a net beneficiary of such changes.
Rising momentum
Avesco has a MomentumRank of 95. The stars seem to have aligned for the firm recently, and there’s nothing to dislike here:
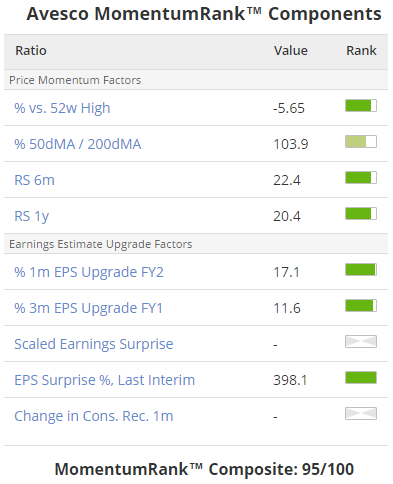
Avesco shares are performing well and earnings guidance for the year ending 30 September has risen by a whopping 49% since January.
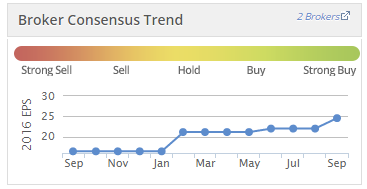
Although this partly the result of the Fountain Studios sale, this isn’t the only reason. Note the series of smaller upgrades since May. Further gains are expected next year, suggesting that analysts covering the firm believe underlying earnings growth will remain strong.
Avesco shares trade on 11 times 2016 forecast earnings. With less than three weeks until the end of the firm’s financial year, these forecasts should be pretty reliable. Current guidance for next year is for earnings of about 27p per share, which equates to a P/E of 10.
Avesco offers a modest valuation, rising dividend, strong asset backing and almost no debt. This stock looks very good value to me and will shortly become the smallest company to join the SIF portfolio.
As always, my comments are my opinion only. Please DYOR -- and if you’ve bought, sold or rejected Avesco, then let me know what you think in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Dear Roland, I do not normally comment, only avidly read, but WELL DONE!
I am going to be holding for now - 40p below the bid price if we sell out according to my HL account.
In any account - I have 100% trust in the directors at AVS - the bid is a high premium but its with someone who has worked closely with AVS for a while now so they would know the company very well as well as the directors.
Not quite, I was offered 635p on a dummy sell on HL so only 15p, which was tempting.
Aren't the irrevocable undertakings on the part of Avesco rather than NEP though? Couldn't NEP withdraw still?
From reading the RNS there are 'irrevocable' undertakings representing 58.9 per cent of the shares even in the event of a higher offer. The only question is how irrevocable is irrevocable?
A very good result.
I would be extremely interested on hearing peoples views as to what to do when a massive gain happens in a day like this. This was already one of my largest positions however after this rise it is massive.
Given it is a cash offer for 650p unless a 2nd offer comes in there would presumably be very limited further upside from the now 630p (and potentially a significant downside should the deal collapse) would it not make most sense to sell and say thanks very much - cash on the table and all that.
A very happy day for me!
No chance of this one collapsing IMO. Just wait for the cash which looks like coming by year end. All directors & some v large shareholders have agreed it, it's going to happen.
Hi pgs501,
Always a risk a bid might not go through especially if it's in a contentious sector (e.g. defence), it's in a closely regulated business (e.g. a utility) or there are material competition issues due to the combined entity attaining a dominant market share etc.. None of those seem to apply here. Likewise also an issue as to whether the putative buyer has the funds to complete but by the stage this bid seems to have reached with a recommendation and >50% acceptances all parties must be pretty comfortable on this point.
It does seem unlikely there will be a higher offer given the very high premium being paid, so it looks like you have the choice of waiting a few weeks for the full 650p offer or take the market bid and benefit from slightly less cash today but with the certainty of completion if for some reason the bid falls away. Wisdom of Solomon might be to sell half and run the other half for the extra 20p per share. Nice position to be in either way ...
Best,
Gus.
If this were bridge this would be called a shut out bid I would of thought but who knows? It is an incredible premium. I hold, now 13.5% of my ex-cash portfolio. At least I have this evening to work out what to do.
Amazing!
Edit Have started reading the RNS and this states:
"NEP has therefore received irrevocable undertakings to vote in favour of the Scheme at the Court Meeting and the Special Resolution to be proposed at the General Meeting in respect of, in aggregate, 11,238,928 Avesco Shares representing, in aggregate, approximately 58.9 per cent. of the issued share capital of Avesco on 16 November 2016 (being the last Business Day prior to the date of this announcement)."
So I think this is a done deal unless I don't understand correctly, which is entirely possible.
Think I will sell tomorrow and move on.
Wow ^64.
Not sure I've ever seen a 125% bid premium before. Do you think they'll get a counter offer?
Gus.
!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!
http://www.investegate.co.uk/avesco-group-plc--avs-/rns/offer-for-avesco-group-plc/201611171559525027P/
WOW!
Avesco (LON:AVS) :US subsidiary, Creative Technologies, alone is almost certainly worth considerably more than the current market cap and more recently CT made this non-RNS announcement: http://www.ct-group.com/eu/en/posts/expanding-operations-in-the-uk-spain-the-middle-east which says that... reflecting increasing business demand, CT is rapidly expanding its operations in the UK, Barcelona and Dubai.
In the September trading update http://www.investegate.co.uk/avesco-group-plc--avs-/rns/trading-update/201609011246257191I/ they said "...anticipate that results for the year to 30 September 2016 will be comfortably ahead of their previous expectations." yet the Stockopedia reported EPS forecasts have fallen(!) prior to that RNS from 22p to 21.5p.. Note that Edison research note, post the above RNS has EPS at 24.6p which, to my mind, is possibly on the low side.
Carcosa
RNS just now that Avesco (LON:AVS) has disposed of Preteigne to management for consideration of approximately £5m.
http://www.investegate.co.uk/avesco-group-plc--avs-/rns/disposal-of-presteigne-limited/201609301332093718L/
Goes some way to tidying up the company and focusing management on the profit making core. Good outcome all round IMO.
Best,
Gus.
Avesco has popped up on my radar quite a bit recently as a potential quality/value buy. However I am unable to trade the company's shares through my current online broker. One comment I would make is in respect of the net assets per share quoted at 230p per share. Having been involved in this type of business in the past I know that the high end, high tech equipment a company like this must employ carries a huge premium for "early adopters". They have to constantly upgrade to the latest "cutting edge" technology in order to preserve their lead in the market. The depreciation on this type of equipment is massive. How "tangible" should we regard these types of assets? Personally I would heavily discount the quoted figures before crunching the numbers and coming up with meaningful ratios.
Hi Rupe60,
Thanks for flagging up this risk regarding net asset value. I would tend to agree with you, but I don't have the expert knowledge needed to estimate this so have taken the company's figures at face value for the purposes of this article.
However, I haven't looked into Avesco (LON:AVS) depreciation policy, either. It may be that such equipment is rapidly depreciated to reflect its resale potential. I'm not sure without further work, but for me the primary appeal here is the potential for earnings growth. Asset backing is more of a secondary appeal, so I'm not overly concerned.
Regards,
Roland
Rupe60,
You're correct that a lot of the kit which Avesco hires out depreciates rapidly. This is reflected in the large depreciation charge of about £16m p.a.. Net book value was about £46m, so it looks as if the average depreciation rate on NBV is about 3 years - which seems pretty conservative to me (see note 15).
The 2015 Annual Report is here. The accounting policies note on page 37 shows that the depreciation policy on hire equipment is between 2-10 years, depending on the nature of each item.
The company and its auditors review the appropriateness of depreciation policy as a routine thing. So you really shouldn't need to make any manual adjustments to the accounts to make them more conservative, as it's already been done by the company.
Note also that the EBITDA figures are spectacular, since the depreciation charge is high.
Regards, Paul.
Really excellent dissection of the stock ranks Roland. I know Paul Scott and others have rightly made the point that if CT were standalone, it would attract a much higher valuation than 10* next year earnings. The other two divisions are adding little or no profit, and the market cap would almost certainly be much higher without them. The Sale of Fountain shows the Group will take action in time if they cannot get these two parts of the business to perform.
While the Dividend payout has been ok without being exceptional, there must be scope for this to make a "step change". The net debt has been reduced to only c£3m, and as you rightly say, strong cash generation is a real feature of this business.
I think that step change just happened!! At a decent premium over trading price too!