SIF Portfolio: Should I sell Plus500 after FCA spread betting crackdown?

Shares in SIF Portfolio holding Plus500 closed down by 28% on Tuesday, after the FCA announced plans to restrict leverage for retail investors.
In this week’s article, I’ll consider the potential impact of this news on profits. Should I sell Plus500 now to avoid the risk of further losses?
I’ll also take a passing look at Plus500’s more upmarket UK peers, IG Group and CMC Markets. Both companies fell by more than 35% on the news, but are seen as higher-quality operators. Are they now cheap enough to deserve a closer look?
What’s happened?
The FCA has analysed trading data from spread betting/CFD firms and found that 82% of these firms’ retail clients lose money. A particular concern is that investors with little experience are able to access very high levels of leverage.
The FCA found that some products allow clients to trade positions worth 200 times more than the deposit they’ve placed. The regulator is now proposing a leverage limit of 25 times for investors in their first year of CFD trading, and 50 times thereafter.
In my experience, the leverage levels available on indices and FX are much higher than those on equities. For example, IG currently allows customers to trade the FTSE 100 with a margin of just 0.5% for positions of up to 155 points. That’s equivalent to leverage of 200 times on positions worth up to about £1m. It means that a 5% fall in the value of the FTSE will result in a loss of ten times your initial deposit.
The FCA has decided that the best way to protect retail punters is to reduce the differential between deposit size and potential losses. This is expected to put a dent in the profits of CFD firms, especially at the lower quality end of the market.
The impact on Plus500
Here’s what I said about Plus500 when I added it to the SIF portfolio in September:
“Plus500 has high quality and momentum but a lower value rank. This is the profile of a high flyer. These are stocks that can deliver terrific multi-year gains, but can also crash horribly if things start to go wrong.”
Plus500 shares have fallen by almost 40% in the last week! Tuesday’s 28% fall was preceded by a 10% drop last week when the Cypriot regulator (CySec) announced plans to tighten regulation of CFD firms. The SIF Portfolio’s holding of Plus500 is now down by more than 50%.
Plus500 said last week that it did not believe the changes proposed by CySec would have “a material operational or financial impact”. But the firm was unable to dismiss Tuesday’s announcement by the FCA. In a RNS statement issued mid-morning, Plus500 said:
“The company believes that the topics covered in the note will have a material operational and financial impact on the UK regulated subsidiary which represents approximately 20% of the Groups [sic] revenues.”
What we don’t know is what proportion of Plus500’s profits come from the group’s UK-regulated activities. I’ve not been able to find a geographic breakdown of revenue and profit for Plus500. So in the absence of any better information, I’ve deducted 20% from 2016 broker forecasts to see how earnings might look if the FCA changes go ahead.
The result is that at 370p, Plus500 shares trade on a forecast P/E of 7. That may look cheap, but it’s a crude estimate which ignores the other potential risks in this situation. I believe these are considerable:
- Plus500’s exceptional profitability might be dependent on its customers using very high levels of leverage;
- The FCA’s plans might be copied by regulators in other jurisdictions;
- Attracting new customers may become harder. The FCA also plans to ban some marketing offers, such as new customer bonuses;
- Today’s headlines mainly relate to the losses suffered by inexperienced CFD traders. But more experienced traders also have their gripes with these companies. For example, I’ve seen criticisms regarding margin calls and the pricing of stopped out positions. Last year, I waited nine months for the funds from a winning short position on a delisted stock to be made available to me. Even though all of these practices may be above board, they provide a boost to both cash flow and margins. More rigorous regulation could force CFD firms to be more even-handed.
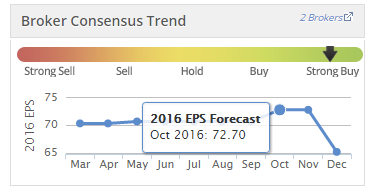
Broker forecasts for Plus500 were already falling before Tuesday’s FCA announcement.
Plus500 is out
In my opinion, the outlook for CFD and spread betting firms is highly uncertain following Tuesday’s news. Plus500 could rebound from here. But it may equally fall further. The investment story has changed and there’s no way to know how things will pan out.
On that basis, I’m going to exercise my right to close the SIF portfolio’s position ahead of schedule. This will mean a 50% loss, but I feel it’s the right thing to do. I wouldn’t touch Plus500 shares were they to appear in my screen today.
What about IG and CMC?
The view among analysts quoted in the FT on Tuesday seemed to be that IG Group and CMC Markets are the unintended victims of the proposed changes by the FCA. The general feeling is that these firms have higher value and more experienced clients, who will be less affected by the proposed changes.
Despite this, shares of both firms fell by more than 35% on Tuesday. One reason for this may be that both stocks were more highly rated than Plus500, so experienced a more brutal derating. A second reason may be that we do have some idea what to expect from the proposed changes. When Japanese regulators introduced a similar leverage restriction in 2010, IG Group’s Japanese revenue fell by 32%.
The UK is a far bigger market than Japan for IG. UK clients generated 49.3% of IG’s operating profit last year. In my opinion, it’s easy to imagine that the changes proposed for next year could knock 20% off IG’s profits. If that happened, IG’s earnings could return to 2013 levels. Interestingly enough, Tuesday’s share price fall took IG’s valuation back to levels last seen at the start of 2013.
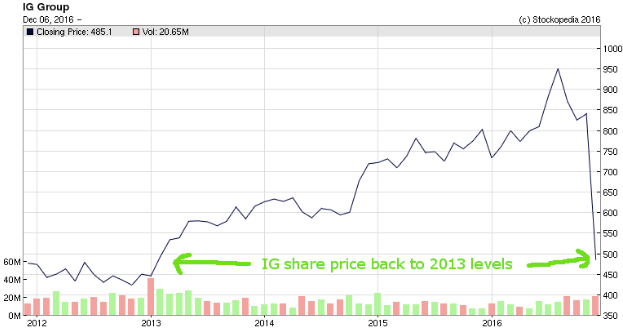
IG would be my pick of the stocks in this sector. But I’d want more information, or a much lower price, before buying.
Remember that as always, these are only my opinions, not advice. Please DYOR and let me know what you think in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
There's definite value emerging in this sub-sector.
I was working through the CMC Markets (LON:CMCX) numbers this afternoon on the back of an enveope.
For y/e March 2016, the company had current assets of £205m & total liabilities of £55m
i.e. net current assets of £150m.
Subtracting this number from the market cap of £273m gives an adjusted market cap of £123m.
This compares with a net profit of £42.5m i.e a historic p/e of 2.9x
Sure, the regulatory climate may be more hostile in the future compared to the past, but a degree of pessimism appears to be embedded in the share price.
Who knows maybe Peter Cruddas, the majority shareholder, may take the company private again, 10 months after IPOing it at 240p/share.
t
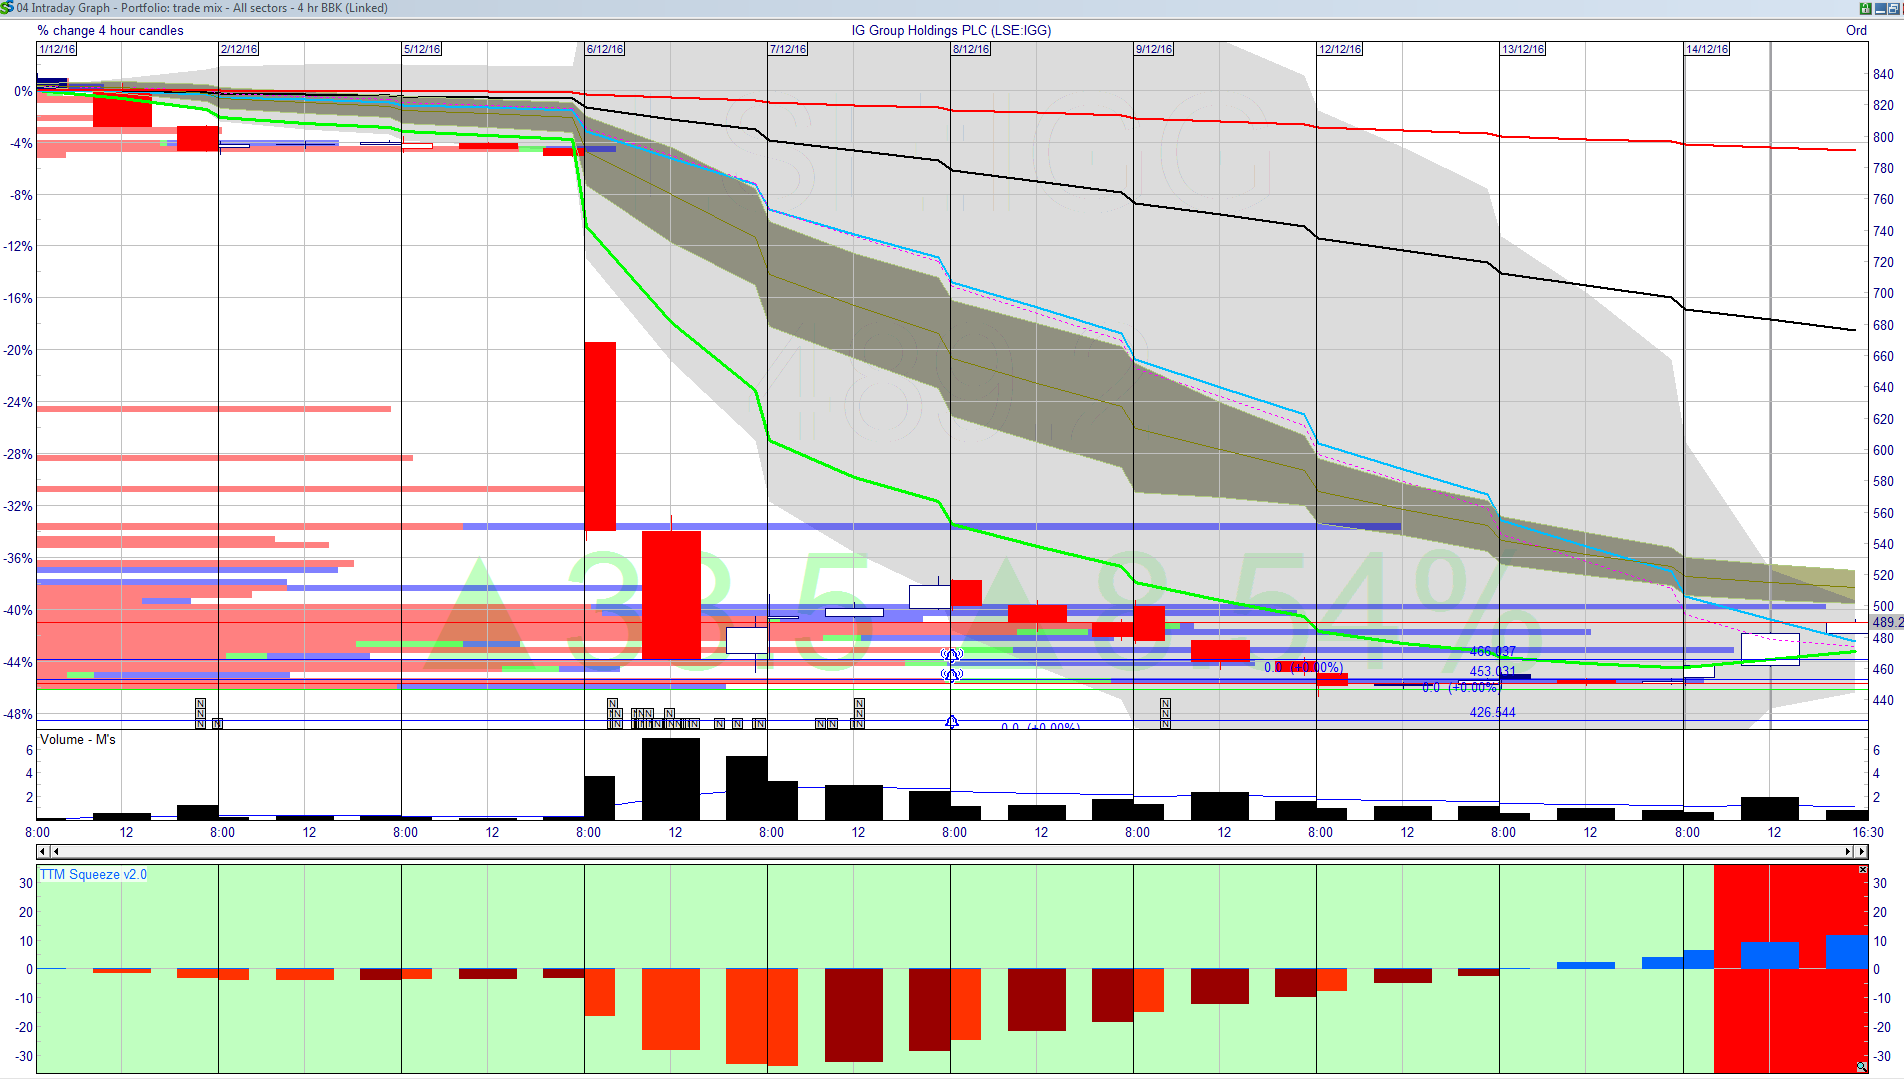
took a trading position in this from 453p - nice pop today up 9%. Never a good thing to try and pick bottoms but this move looked well overdone and the technicals started to stack up with accumulation around the 452p. Would like some more volume to confirm the move but looks encouraging
Close eye and a stop loss in play
Its ironic that 80% OF PLUS 500 retail customer lose money I would expect 80% of their retail investors now lose money as the large institutions dump their stock. I wouldn't be surprised if this fell below £3
Yes.
had a look at IG Group (LON:IGG) over the past couple of days : I have used their services for a few years though mainly to trade US instruments and the odd commodity play. I have found them to be very professional, providing a lot of additional services to inform and educate retail investors. Especially compared to some others who are much less reliable comprehensive not to mention ethical.
In a pool of sharks, they are probably one of the least predatory
Went through IG Group (LON:IGG) numbers and financial report which has a good risk assessment and some dialogue on regulatory impacts
Went through the FCA ruling: seem sensible especially the control of binary bets (which made up £48M in IGG revenues last year ). Buying shares in any company comes with risk : controlling the amplification of risk with CFD leverage is again eminently sensible especially for inexperienced clients
I wonder if the FCA looked at data for investors who buy shares without leverage - I suspect many of those lose money too. Reducing the gearing ratios may save money but it won't make better investors of these retail clients
Many of the analysts have reiterated their buy recommendation with 950p target SPs
There is good technical support around the 450-460p level
I'll wait for a bit of stabilisation in price, but at 465p this looks like a reasonable buy ...albeit risky to further downside slides potential to the 420-430 levels. In the medium term I'd expect a good rally in the SP.
For my mind, IGG's moat is its differentiation to others in this space, it may even gain market share as a result of a shake down in the longer term
Germany has just published that it intends to introduce restrictions on CFDs. The below is from a trading statement put out by IG group at close of trading today:
"The BaFin announcement proposes that the marketing, distribution and sale of CFDs to retail clients in Germany can only be undertaken if the client is not at risk of losing more than the value of their account."
This suggests to me that there is still significant pain to come in this sector and we are likely to see more regulators introducing limits.
Another view point is that the FCA restrictions and clampdowns will provide further barriers of entries for new entrants to what is and was already a very profitable sector - which will only result in further consolidation in the sector.
Lets not forget that Plus500 is a very innovative company, and over the next 12 months will likely find new ways to commercialize their business model. They have been through some s**tstorms before - but most importantly have some how overcome all of these issues in the past.
This is currently an external factor that has come into play and so far (in this issue) have not been found to doing anything wrong. So far.
Regardless of Odeys YTD performance, I think it is always positive when a hedge fund knows, or is showing faith in a company that others will not touch with a bargepole. 20%+ ownership is certainly not just a punt for anyone.
I consider myself to have been very lucky to have baled out of PLUS500 on the back of the Cyprus news. VERY LUCKY!. Personally I feel that the FCA are in full investigative mode ( LIBOR F/X etc) and they smell a decent fine coming for miss-selling or some such apparent breach of the rules . To some punters spread betting is the same as 50 quid on the nose of the favourite for the 3;30 at Kempton Park.I think the fun with this sector is over for the medium term. What on earth Crispin Odey knows is another matter but he now owns 21% of Plus500. I must admit, he is significantly richer than me so good luck to him but.......
Roland, thanks for your article.
Re the risk that other countries could copy the FCA, I think I saw somewhere that leverage restrictions already exist in many countries, so this would reduce the downside risk there. Also, the proposals may be watered down. Also, IG (which I now have a position in) has other profit streams eg share trading and I believe they want to diversify into asset management. Also, even if people trade smaller amounts due to the lower leverage they can increase profits by increasing spreads or other fees. And there will likely be fewer competitors as some smaller ones will be driven out of the market. They are a well-run company and surely will find ways of keeping their profits going. So it seems highly unlikely profits would fall by more than 25%. Consensus eps for 2017 was previously 47.5p and it had a pe of 16.5. So say eps becomes 35.6p and give just a slightly lower pe of 15 (as potential future rate of growth of profits isn't affected) and you get a fair price of 534p. (Of course if you factor in their net cash that increases the value). Maybe that is the rationale behind today's price increase of 5.85%.
Hi dgold,
While I think the likes of IG are plenty smart enough to figure out new ways to make money from the retail punter and could well benefit from the impact of tougher regulation on some of the smaller more marginal new entrants, I think the real "bear case" for the sector is perhaps predicated on a regulatory prosecution of alleged historic malpractices (I.e retrospective fines and compensation claims).
Look at the impact of the PPI mis-selling scandal on the UK high street banks (among others). While there is the sense that many spread betters are mugs who don't know what they've got into, I suspect the same people will be quite receptive to jumping on a free lunch, gravy train (horrible mixed metaphor!) to claim they have been abused, especially if there are some enterprising ambulance chasing lawyers sniffing another game to chase. I accept the duty of supervisory care from the FCA should perhaps be higher to retail high street borrowers than online punters so there is less imperative to make an example of them but these things sometimes take on a life of their own.
Good luck!
Gus.
Gus, thanks for your reply. You make an interesting point by suggesting the main worry is compensation claims for past misconduct. I would point out though that this concern could have been raised previously and is not really directly connected (as far as I can see) with the FCA's consultation.or more likely because of it. The FCA doesn't seem to be saying that companies have acted unlawfully. Also, even if some had, in the specific case of IG I think the risk is smaller as they do have a good reputation for treating customers fairly. Although as you say there could be something of a "gravy train" effect. But speculation on claims is still somewhat speculative in my opinion.
Hi, Roland. From memory (not very good) I believe this is a fantasy portfolio, so hopefully no real financial loss has been incurred.
From your SIF post on Nov 30th (my memory just about goes back that far) you wrote "When the portfolio reaches its first anniversary, I may consider extending the six-month minimum holding period, but for now, I’m sticking to the rules. After all, there’s no point in running a rules-based portfolio if you keep changing the rules. Frequent changes make it impossible to say whether any of the rules actually work."
Obviously if there's real money involved any deviation from the rules is totally understandable, but as a theoretcial exercise I would have thought it more valid to keep it in.
Interesting post yesterday from arch bear, Simon Cawkwell, aka Evil Knievil, on his daily Master Investor blog.
https://masterinvestor.co.uk/evil-diaries/fcas-spreadbetting-shake-long-overdue/
The gist of the commentary is that there may well be an ice berg of complaints just below the surface of the spread betting industry and should the FCA wish to investigate and prosecute there may be further for many of the players to fall. Salutary reading ...
Gus,
Back in mid May 2015 Paul did warn about this & similar companies, but specifically where there were problems with Client Money & laundering claims. At that time it had a Rating of +98 ; V= 67; Q=91 ; M=95. which clearly underlines the DYOR warning particularly with stocks of such high rating; not just a case of piling in.
Having read the background yesterday I did take a small punt on IG yesterday. Agree that this drop is a little overdone on something yet to materialise and though it will obviously have an impact I'm only in it for the short term recovery.
One can only make sweeping assumptions in a situation like this. However, is it too sweeping an assumption to assume that 20% of PLUS profit will disappear because of this FCA investigation, based on the fact that UK represents 20% of the Group Turnover. The FCA is not outlawing all UK trading, just curbing excesses in it, so a proportion of the UK Turnover will disappear. Perhaps a quarter...perhaps even half...and this would represent 5% or 10% of the group respectively.
A bullish view might be that a smallish proportion of UK punters are affected, and perhaps those at the lower quality end...who currently cost to recruit yet their churn rate is high. If I was sure the FCA statement was the end of it, then I might take this view. However, the risk is more about whether the FCA is only the start of it, and other countries follow its lead.
Hi Alan,
Thanks for your comment. I agree with you completely -- my biggest concern is that yesterday's news is the start of the disruption to this ultra-profitable sector, not the end of it.
My arbitrary decision to project a 20% reduction in profits was based on the feeling that the disruptive impact of even just the FCA changes could be greater than is currently apparent. I'd rather be too cautious than the opposite!
Regards,
Roland
Alan,
"A bullish view might be that a smallish proportion of UK punters are affected, and perhaps those at the lower quality end...who currently cost to recruit yet their churn rate is high"
Perhaps one argument may be that PLUS's customers are more generally skewed to the lower quality end of the spectrum of users of leveraged products and as Roland notes, IG by contrast, is likely to attract and retain higher quality and more experienced customers. I would therefore challenge your view that only a smallish number of UK customers are affected at the lower quality end, as whilst you could be right in aggregate across the market, this group could be disproportionately skewed towards being a large proportion of PLUS customers.
On this basis, I would be very wary of PLUS at the current time, going so far as to suggest it's a bargepole stock.
I think the P/E is more reasonably 5.7 at the moment (based on today's Stockopedia report), as below.
2015 net profit: $96.6m;
Discount the net profit by 20%: $77.2m
Current enterprise value: $439.9m (used instead of market cap as there is considerable net cash on the balance sheet of $96.2m);
Hence 439.9 / 77.2 = 5.70. If you include the cash then the P/E is 6.94. I know this is not a standard adjustment but you cannot ignore such high net cash in a business with such a high margin.
ODEY ASSET MANAGEMENT LLP increased their stake today in plus500
ODEY ASSET MANAGEMENT LLP increased their stake today in plus500
Given that ODEY EUROPEAN is the worst performing hedge fund YTD November with -46.71% and that is before the recent Plus500 (LON:PLUS) drop then I don't think them increasing their stake is positive for Plus500 (LON:PLUS). Both from a judgement point of view and the fact that very few funds survive those kind of draw downs when in benign markets so if they end up liquidating they would be forced Plus500 (LON:PLUS) sellers.
I've just finished reading Benjamin Graham's "Intelligent Investor". Applying his analysis would I think result in the conclusion that buying spread betting firms relied on a continuing flow of good news/results and was therefore vulnerable to unpredictable events, so it lacked his required margin of safety (interestingly your analysis of Plus500 was spot on in that you saw the risk very clearly but your decision was different to what Graham's would have been). Would Graham now see a buying opportunity? Based on your analysis of the likely impact on earnings I think not as what you are saying is that the shares will essentially have the same rating in p/e terms once the impact of FCA regulation feeds through into earnings, so buying now would be a bet on whether the market is accurately assessing the impact on earnings but again without the required margin of safety.
This is a long winded way of getting to a question which is why are you making a different decision now to the one you made previously and whether applying the same approach when you bought would actually result in a decision to hold now and not to sell? Another way of putting it is do you think you made a bad decision when you bought which you are now having the courage to correct or do you think you made the right decision which just happened on this occasion to turn out badly?
Sorry that's not meant in any way to be awkward or critical I'm just interested in the psychology of it and in your opinion?
This portfolio and your commentary on it continues to be informative and interesting, thanks for the work!
Hi Hot Socks,
My decision to add Plus500 (LON:PLUS) to the SIF Portfolio in September was made before anyone knew about the FCA's plans to tighten up regulation of CFD firms.
As you say, I was suspicious of the firm's extreme high margins and cash generation, but decided to accept these as the stock satisfied all of the portfolio's screening criteria. My purchase was based on the premise that the external environment in which Plus500 operates would remain unchanged.
The decision to sell was made because this external environment has now changed. The FCA's proposal will disrupt Plus500's business model, but we don't yet know what the full impact of these changes will be. Holding onto the shares is too speculative for my liking.
I don't think I'm being inconsistent. I'm a fan of Ben Graham too, but the original purchase was never intended to satisfy serious value criteria. The criteria I use to select stocks for the SIF portfolio are rather different -- you can see the screen here: http://www.stockopedia.com/screens/stock-in-focus-screen-113218/
Hope this helps, thanks for your comment.
Regards,
Roland
Thanks for the reply Roland, helpful as always. I get the point you're making.