Small Cap Report (11 Apr) - NXR, XAR, SRT, PLA, VLX

Pre 8 a.m. comments
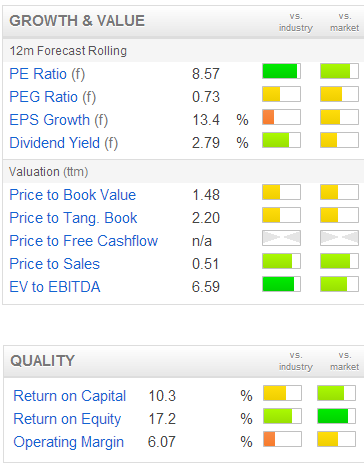
Good morning! The year end (31 Mar) trading statement from Norcros (LON:NXR) has been issued, and doesn't seem to contain any surprises. This is an interesting company which looks significantly under-valued to me, since its peers are typically on a PER of about 17 (pricing in some economic recovery/growth), whereas Norcros has languished on a single digit PER for a long time, although the shares have risen nicely they still look good value to me.
Norcros manufacture and distribute Norcros showers, Johnson Tiles, Norcros Adhesives, and following a very recent acquisition, Vado taps & fittings. They operate mainly in the UK and S.Africa - interestingly Southern Africa being a good growth area at the moment apparently.
Group turnover rose to £210m (up 5% vs prior year, and up 10% on a constant currency basis), and this is all organic growth because Vado was only acquired on the last day of the financial year.
Underlying operating profit is a creditable £13.0m (versus £12.1m for 2011/12). I am impressed with how Norcros makes a fairly steady 5-6% operating margin, having done its restructuring a few years ago after the credit crunch saw it get into hot water (geddit?!!) loaded up with too much debt after a disastrously ill-timed IPO in July 2007.
Bear in mind that NXR has quite a large depreciation charge, so the underlying EBITDA is c.£20m. This should enable it to repay debt fairly rapidly, although in the short term net debt has risen to £31m (well within newly enlarged £70m bank facilities (some of which will be for Letters of Credit, Forex hedging purposes, but I don't know the breakdown).
However, they also own freehold property with a net book value of £28.2m at 31 Mar 2012, so I tend to offset that against debt in my calculations. One should also consider the large pension fund, but this was 94% funded as at 30 Sep 2012, so a relatively small £22.3m deficit. That will be a volatile figure, but QE has exaggerated all final salary pension scheme deficits, so the likelihood is that it will reduce or disappear altogether once bond yields normalise (as that affects the present value of how liabilities are calculated). It's also a mature scheme, so will dwindle in size over time.
The pension scheme doesn't worry me, and only requires overpayments of just over £1m p.a. at the moment, which is likely to rise to just over £2m at the next valuation, by my estimates. So an irritant, but not something that affects the long term valuation of the business.

The awaited planning consent for land at Tunstall has been announced in today's statement. The outlook statement looks fine, so all in all as a shareholder in NXR I'm pleased with this trading statement, all looks fine. I cannot understand why these shares are under 25p, which looks the right sort of price to me (and would only be a PER of 12), and coincides with the price target mentioned in an outstandingly good Charles Stanley note written by Peter Ashworth dated 15 Mar 2013.
Given that we have been in subdued economic times now for five year, there must be a backlog of demand for new bathrooms building up, as electric showers for example have an average life of 7 years. Therefore I could see Norcros delivering much better EPS once the economy is recovering more strongly, don't forget the operational gearing that cyclical companies have. In time therefore I'm wondering if EPS might not rise to say 3p, put it on a PER of say 12-15, and you're looking at a much higher share price. I'm thinking 1-2 years ahead here.
Oh, the dividend isn't bad either - about a 2.8% yield.
Post 8 a.m. comments
A muted market reaction to the Norcros statement so far, but on negligible volume. I'm tempted to buy some more if they come down to 17p Offer (currently 17.25p with a 0.5p spread - I only like to buy when the spread has narrowed to 0.25p). Broker consensus does not appear to have been updated for the Vado acquisition, so I reckon we should be looking at 2.2p EPS for the current (new) financial year, so that means the PER sits at just 7.7 based on the current 17p share price.
As the Charles Stanley note sets out, comparable companies are on an average PER of 17. Anyway, there we are.
Shareholders in inkjet head manufacturer Xaar (LON:XAR) will be delighted with a terrific Q1 trading update today.
I've always liked this company, but got enthusiastic about it about 8 years too early, so sadly don't hold any. The statement today says that Q1 has been strong, and that management have increased their expectations for the year.
Cash generation has been pretty astonishingly good in Q1, with net cash rising from £28.9m at 31 Dec 2012 to £41.7m at 31 Mar 2013, although some of that is due to favourable working capital movements.
Unsurprisingly, the shares have risen 14% to 480p today. Forecast EPS is currently around 23p for 2013, so we might now be looking at 25-30p EPS possibly for this year, therefore at 480p and with that kind of strong growth happening, the PER of 16-19 doesn't look outrageous at all. If I owned them, I'd probably sit tight, although it's far too late for me to join the party now.
As always, it depends what factors are driving the growth, and whether that growth is sustainable?
Software Radio Technology (LON:SRT) announce a contract win from the Middle East for 500 of its vessel tracking transceivers. I'm not sure how material that is? (they say that it is small, but signifies the start of the region's roll out). Please could someone who is more familliar with the company add some colour to this in the comments section below (incidentally, you do not have to pay a premium subscription to comment here, you just need to be a registered with a free Stockopedia account - there's an option to "join the discussion" in the sign-up page). Would be good to get a bit more discussion going, as these are intended as interactive reports, not just monologues from me!
Plastics Capital (LON:PLA) has issued a trading update for the year ended 31 Mar 2013, saying that revenue, profit margins and cashflow are expected to be broadly in line with market expectations. So slightly below then.
Some more detail is then given about new products & accounts have offset demand weakness in Europe. Their Chinese production line will open in Q2 of this year (Jul-Sep). Recent sterling depreciation has been helpful to them.
I've always thought that patient holders would do well on PLA with a long term view, as it gradually repays debt, and seems to have solid, niche operating businesses.
Electrical cables maker Volex (LON:VLX) has issued a trading statement, which appears to have displeased the market, as their shares are down 6% to 97p, for a market cap of about £60m.
They say that revenues & operating profits for year ended 31 Mar 2013 are anticipated to meet market expectations, and helpfully they mention the average forecast is $473m revenue, and $11m operating profit.
On the downside, net cash has turned into net debt of $20m, and there is another restructuring with exceptionals of $7m planned. It's too low margin, and accident prone for me, so I'll pass on this one.
OK, I have to dash for the train to an investment lunch later. Have a good day & see you same time tomorrow.
Regards, Paul.
(of the shares mentioned today, Paul has a long position in NXR, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Thanks djp. This is really useful and interesting. I am just never sure whether in a recession consumers buy on price or quality. My mum always used to say 'only rich people can afford to buy cheap clothes'.
Interesting post beginner.
For what is worth, i used to make Mira electric showers during my summery holidays - dad was the MD.
Yes, the quality is fat superior and that does carry a suitable Mark up do budget conscious people may look to the cheaper norcros options.
Paul is spot on though about the effect of limescale. Some units were solid. It really affects the performance and of course is very costly as it takes a lot more electricity to heat the water. Boiler owners take note.
Installing a water softener is very very sensible for anyone, especially if you have hard our even "normal" water.
Rant/lecture over.
D
Just to bring a bit of a debate element along, while I think Norcros (LON:NXR) will do well as a share, I would like to say that the Triton showers they produce are far from the best on the market. Mira (manufactured by Kohler) seem to me to be a far superior product (though I have admittedly fitted few of these appliances at all). Mira have integral filter elements which cut down on clogging, and are easily replaced. Their general construction is also more robust. As for the Johnson tiles side, the recent contract to supply materials to B&Q is not really a great recommendation. Perhaps more store should be put by the fact that Homebase (Home Retail) seem to be stopping stocking them (or at least my local branch is). The recent acquisition seems to be a bit more upmarket, but I am not familiar with them at all. It seems to me Norcros may be taking a lower position in the UK market, sacrificing quality for quantity. That may not help in the long run. This could in turn push them back on their South African operations for profits, something that I personally would look upon with a little unease. Perhaps this is a case of the figures being better than the story.
RE: NXR , one of the big builders I'm subbying on at the mo is all NXRs wall and floor tiles probably around 1500m² - 2000m² per site plus they specced some of the their adhesive as well. The house bashing side of the industry certainly seems to be motoring from where I see it at the moment , don't know how long it will last tho'.
Cheers
DbD
Paul, the competitive situation for SRT is very benign. That's not to say it cannot change of course but there are a number of reasons to be fairly relaxed about this. Firstly, SRT have very up to date products, in fact one, the AtoN (Aid to Navigation) which fixes to market buoys to warn of a reef or wreck is brand new and about to go on sale. It uses 50% less power than the next most efficient unit currently available which gives it a big competitive advantage.
SRT have based their new product releases on a new core architecture using a processor board the size of a credit card. This reduces cost and allows considerable customisation of function since the S in SRT stands for Software i.e. they control the radio functionality by software not hardware. One example recently was to customise units to use the Russian GPS system GLONASS as required by Russian users. This took weeks rather than years.
SRT also have a network of 90 or so customers with sales outlets around the world with almost all of the major brand names selling units which use SRT made components or in many cases SRT boxes with a name badge change only. In Class A, the type of device used by large vessels, they claim a 90% market share. This dominance is based on having built up relationships with resellers over several years, often with exclusivity. Competitors would have to break this down in order to build their own sales and given the cost of developing the underlying technology, the pay back period may deter them from trying.
AIS is a heavily prescribed technology that limits competing technologies so anyone trying to gain a large market share must compete on price or functionality or both. Unlike sales of consumer technology where production runs of a few million are common, AIS is not large volume on that scale. Development costs are high because cheap and cheerful will not pass the exacting specification conformity tests. Just as an example, SRT built some test decks to test their kit and each one costs several hundred thousand pounds - I think they needed six. That costs has to be recovered by selling lots of kit so this is not a market where you are likely to see lots of major players. More likely it will remain a niche, a very profitable niche, for a few at most and since SRT have gained the initial lead, it's theirs to lose; a fact which they are acutely aware of. I am sure R&D will remain a key part of their business strategy.
So far as the niche and it's profitability is concerned, just consider that the USA alone spends something like $27m a year of AtoN hardware. The worldwide market is estimated at £200m. SRT's market cap is about the same as the potential annual revenue from the USA for this one product.
My personal view is that any serious minded competitor would find it cheaper and quicker to buy SRT than to try to out-develop them.
Paul - I know you like good communication from Companies to Investors
todays web-cast already up for those that missed it this morning
http://srt-marine.com/investors/corporate-media-centre
regards
John
Thanks John,
I shall peruse that with interest. SRT does seem to be coming good. I was sceptical a while ago, but recent newsflow has been much better.
It was also great to see you tonight at the ED evening!
Cheers, Paul.
Northbridge Industrial Services (LON:NBI) reported 2012 prelims this morning.
http://www.investegate.co.uk/northbridge-ind-serv--nbi-/rns/2012-preliminary-results/201304110700220663C/
Revenue (with acquisition) up 23.7%.
Revenue (without acquisitions) up 14.9%.
Basic earnings per share based on the average shares in issue during the period was 24.0 pence (2011: 15.1 pence). Net cash generated from operating activities amounted to £8.4 million (2011: £4.8 million)... At 31 December the Group had net gearing, defined as the ratio of all short and long-term financial liabilities less cash held to net assets, of 44.2% (2011: 39.5%). Excluding the investment in the new freehold property, which was acquired during the year, net gearing was 39.9%.
That new freehold property, I understand, was a steal.
Final dividend up 10%, meaning the payout for the year at 5.425p is up 8.5%. For 2007, it was 2.9p.
Outlook:
The first quarter of 2013 has started well with a number of large contracts continuing to run on from last year. In addition further new contracts have been won which should commence in the first half of 2013. We are still experiencing delays in the projected start dates of certain contracts, but with increased demand we are better able to manage our utilisation. Further hire fleet investment is planned for this year and we expect that our additional production capacity and additional marketing activity will lead to continued growth.
Stockopedia this morning has a 2013 estimate of 31.5p. Shares are currently 328p to buy.
Asagi (no position)
Paul - as always I enjoy your daily wrute up. Just one point.
You say that the average life of a bathroom suite is 7 years. This is because many people have replaced perfectly good suites with new ones out of vanity and fashion - fueled by the supply of easy and cheap credit. Left to its own devices a bathroom suite could last for 30 years or so.
I doubt whether we will see a return to such wasteful living in the near future.
Hi Intuitive,
Good point about bathrooms generally, but electric showers which is a big chunk of Norcros's business do "fur up" internally in hard water areas, so have to be replaced.
P.
SRT is clearly turning the corner into increasing sales and profits. This year alone SRT has announced $7m dollar orders from USA as well as a tie up with a major USA company to launch SRT's full suite of AIS products under the Hummingbird label. Also as mentioned above India and now the Middle East will soon be ordering significant amounts of ais products from SRT. Over the last year or so SRT has been accused of Jam tomorrow but tomorrow now looks like it is arriving this year. Other big markets on the go for SRT are EU fisheries, Russia and china.
Paul, regarding the SRT RNS, the Identifier product is unique to SRT. It is a low cost, rechargeable, battery powered, demountable unit designed to provide basic AIS functionality for small boats, like fishing vessels. It's major selling point is that the location of the boat, and crucially the identity of the boat, can be tracked by the local authority.
In India, the government has built a coastal AIS monitoring network in the wake of the Mumbai attacks which were seaborne and plan to require all small boats to be fitted with an Identifier. Currently, 500 units are being trialled there to finalise any customisation that may be required before placing bulk orders.
In Mexico, the government with backing (and no doubt some financial incentives) from the USA has begun to roll out a mandate for boats to be fitted with the Identifier to counter people and drug smuggling across the US border. SRT have already received the first sizeable order here.
No detail has been given about the underlying mandate for this latest Middle East order but the inference is that further bulk orders will follow, hence the RNS.
The Identifier has multiple uses. It has been fitted to Icebergs for tracking and used to locate fishing nets/pots. It is however, just a small part of the range of products sold by SRT so in itself is not a "company maker". The more significant point here is that AIS is being deployed around the globe in ever increasing numbers for a variety of reasons, safety, national security, piracy prevention, hazard identification, vessel movement management, port logistics, etc, etc.
SRT have spent several years developing a family of products to suit all pockets and all applications. Their products are world leading in terms of performance and price. As a shareholder, I'm expecting to see the reward for their efforts unfolding over the next year or two with a succession of sizeable orders to add to the growing day to day core business, which is believed to be in the region of £10m revenue per year. With profit margins targeted at 50%, I expect the market cap to adjust significantly north over the coming months. All IMO of cousre DYOR as ever.
Thanks Alterego. I am warming to Software Radio Technology (LON:SRT), as they do seem to be delivering now, after some false starts. I wonder what the competitive landscape is like? The technology sounds fairly basic, so is there not a risk that it will plummet in price as competitors join in?
P.
Hi Paul, SRT claim that competition is way behind and that their software is encrypted and not copiable. SRT also claim to have an 80% market share for the class A and Class B products and 100% re their Identifier. The sp is very cheap and this current year they could do £20m turnover (broker forecast light at £15m I reckon). With 50% margins the profits will climb fast.
Paul
This RNS from 31-May-11 seems to provide the most recent uodate re the 3 leases mentioned in todays RNS
http://www.investegate.co.uk/Article.aspx?id=201105310700224865H
Hopefully NXR can provide details on the duration of these leases and the associated potential for future exceptionals. Hopefully the positive activity on other property assets will at least net out with the negatives here.
Cheers, Martin
Paul
If you do speak with anybody at NXR, or its detailed in the broker note you referred to, it would be interesting to know how long the leases on the two empty properties have to run.
Thank you, Martin
and the £3m charge will continue until these leases can be got rid off and then there is further pain in the form of generous reverse premiums paid to the incoming tenants.
Good point about the leases at Norcros (LON:NXR), I'll do some more digging on that.
I tend to disregard factors which do not affect the long term earnings potential of the business, this might warrant a say £3-6m adj to mkt cap, depending on the terms of the leases.
P.
SP is down probably due to the £3m charge taken because they have not been able to shift three leased properties. Also £1.5m costs while buying Vado. I hold.
Otherwise OK.