Small Cap Value Report (14 Feb 2014) - CFYN, VP., KADA

Good morning! Last call for any donations to my spring charity fundraising - I'm abstaining from alcohol for three months (not had a drop since NYE!), and am also running the Brighton Half Marathon this Sunday. It's going to be a disaster, as the weather has been so awful that I've only managed to get out for 4 training runs. Having a stinking cold for the last fortnight hasn't helped either. So realistically, I'm just aiming to beat last year's time of 2:23, which is quite slow, and probably won't get anywhere near the 2:09 I managed in the autumn London Parks half marathon.
Anyway, all donations to my chosen charities (75% going to MacMillan cancer care, and 25% to the run organisers, local charity Sussex Beacon) are very much appreciated. I'm still a fair distance away from target, so anything you can spare would be brilliant. Here is my fundraising page. Thanks to everyone who has kindly made a donation so far, I'm very grateful for your support.
Caffyns (LON:CFYN)
This is a small chain of car dealershps, with a market cap of around £15m at 527p per share. The company has issued an IMS this morning covering the period from 1 Oct 2013 to 12 Feb 2014. It sounds very good, with new car unit sales up 9.8% against the equivalent period last year. They point out this is on top of 20.6% growth achieved last year, confirming that the new car market is in rude health - as has been reported by other market participants for a while now.
Used car sales growth was even stronger, with 21% growth, although aftersales (servicing, etc), was only up 2.6%. The margins on new cars are wafer thin, so it can be the aftersales that is the most lucrative part of this sector. No indication is given of profitability against forecast, which is a rather glaring omission from a trading statement. This might be because, as they point out, the full year result is heavily dependent on the "crucial month" of March.
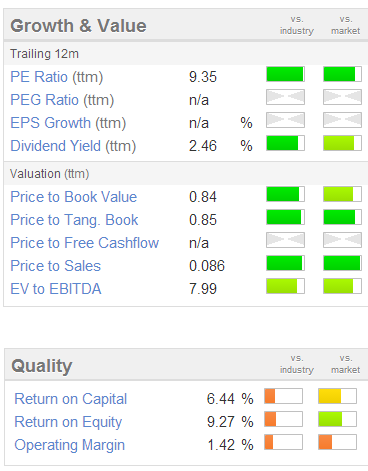 The Stockopedia graphics show a lot of green, although one needs to be careful about net debt, as companies in this sector tend to heavily rely on bank debt, and that can make them appear cheap on a PER basis, but also makes them potentially higher risk.
The other thing to consider with debt is that the interest bill will rise significantly (to the detriment of earnings) once rates go up. Everyone seems sanguine about when rates will rise, but I wouldn't be so sure about that. All calculations should really now be factoring in normalised interest rates, as it's only a matter of time.
I completely missed the boat on car dealerships, failing to predict how strongly the car market would recover. Certainly in the USA new car sales are seen as a key economic confidence barometer, so maybe is here too? Together with the latest Bank of England forecast pushing up UK economic growth to over 3% this year, this appears to be a decent recovery now underway, which should feed through to higher wages & higher consumer spending in the not too distant future. So you can see why shares are buoyant right now, as the Stock Market has correctly anticipated a strong recovery.
IPO Fever
IPOs (i.e. companies Listing on the Stock Market for the first time) have been extremely buoyant in the last year, with lots of companies joining the market, most of which have risen quickly to a significant premium. Therefore this area is attracting a lot more attention.
I feel that there is an information gap - i.e. most of us only hear about IPOs after they have happened, and the rapid initial gains have already been made. There is definitely an opportunity here for innovative brokers or other companies in the financial sector to create some sort of platform to better inform private investors about forthcoming IPOs. Maybe IC and Shares magazine could create new sections to highlight forthcoming IPOs, and how we can go about buying into them?
A friend flagged up Actual Experience (ACT) to me as an interesting IPO, so I tried to buy yesterday morning as soon as the shares Listed at 54p, but the price raced away so fast that it proved impossible to buy any. Guess where it ended its first day's trading? At 245p per share! So it was a four and a half bagger on the first day! This is a technology company which is a spin-out from a University, with some revolutionary new way of diagnosing bottlenecks in IT systems. There are clearly high hopes for the company's technology, as it has gone from £17m market cap to about £75m just in its first day! This is real bull market stuff, and the market now hasn't felt this bullish to me since about 1998 to 1999. That all ended in tears of course, so I think caution is needed right now - it's a difficult balancing act between making money from speculative opportunities, without taking ridiculous risks that could end badly.
I've been talking to a number of brokers recently about getting involved more in IPOs, so if I spot anything sensible and reasonably priced, then I'll flag it up here in these morning reports. Although caveat emptor always applies with new issues - I'm generally very sceptical about the people who know the business best selling or accepting dilution - as it usually means the price is favourable to them, not the person buying! Having said that, as with the Actual Experience (ACT) IPO yesterday, the free float can be very small, so the IPO is really about getting the market to set the price.
My approach is to be flexible according to market circumstances, and in a bull market I'm very happy to make money from IPOs, if there is money to be made. It's a window of opportunity during a period of market buoyancy in my view. Whilst keeping a close eye on the exit of course, as nobody wants to be left holding over-priced junk at the end of a bull run. That said, the brokers I've talked to are saying that junk is being turned away at present, so we're certainly not into the indiscriminate late stage of this IPO boom - yet!
The party will be over when IPOs start flopping, which can happen quite suddenly, and the appetite for IPOs could dry up quickly if sentiment changes - because I think a lot of people are buying them because they generally rise. Take that away, and demand could disappear overnight. In the meantime it's a potentially lucrative area.
VP (LON:VP.)
This niche equipment hire group has issued an IMS today covering the period from 26 Nov 2013 to date. It has continued to trade in line with expectations (not bad considering the bad weather), and as regards the year ending 31 Mar 2014;
The Board expects to report full year profits in line with market expectations.
The valuation looks pretty full now, on a forward PER of 17.1 times, and a forecast dividend yield of a whisker over 2%. As with so many shares at the moment, I think the smart money has been made for the time being. I can see a case for earnings continue to rise (maybe accelerate) in an economic recovery, but competition will also increase, and staff will want higher wages.
Is there really much immediate upside on the chart below, at a PER of 17? I suspect not. It might be worth a look if there is a sharp correction, but personally I wouldn't be interested above about 500p.

Kada Technology Holdings (LON:KADA)
I don't like overseas companies Listed on AIM, and very rarely touch any of them, especially Chinese and Indian companies - they are fraught with risk, and you cannot rely on the figures being what they seem, in my opinion. There are so many differences in custom & business practices, that it's a huge mistake to apply Western analysis onto the figures from overseas companies, on the mistaken assumption that everything is comparable, again just in my opinion.
I am looking forward to a fascinating Mello investor evening on Monday coming, in Beckenham, when no less than three Chinese AIM companies are presenting. Or I assume their UK representatives will be presenting anyway. Should be fascinating.
However, one of many disastrous AIM Listed Chinese companies has reported a troubling-sounding trading update today. Kada today has reported;
...working capital has continued to be an issue for the business and the Group has felt the force of an increasingly difficult debt market in China during the final months of 2013 and the beginning of 2014. Each of KADA's major lenders has sought to re-negotiate its lending terms with the Company. This is a similar situation to those being experienced by a number of our competitors. This uncertainty over the Company's future availability of debt has materially affected the Company's results in 2013
That sounds pretty nasty to me, and certainly makes these shares uninvestable for me, at any price. Although they were already in that bracket for me before today's statement! The share price is down 53% today to 17.5p - just look at the chart, to see the destruction of shareholder value here;

So the general points they make about Chinese banks pulling in lending should ring alarm bells for all Chinese stocks which have bank debt. Cash-rich ones might still be OK though perhaps, who knows?
I think it won't be long until these things virtually all de-List from AIM, and then you'll be looking at a virtual wipe-out of shareholder value. Who would want to hold shares in an unListed Chinese company? So enormous risk lurking here, although also potentially big returns if you can find one that is genuine, but has been tarred with the same brush as the bad ones? That's not a game I want to play, but good luck to those of you who do.
That's it for now, have a smashing weekend, and thanks again for all the kind donations for my charity run this Sunday, much appreciated!
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
Following on from the comments about bank debt being renegotiated in China, by Kada Technology Holdings (LON:KADA) in their trading statement today, there is an interesting article in today's Telegraph which indicates further problems are escalating in China - it very much sounds as if their enormous credit bubble is about to burst.
That could affect the demand from China for luxury Western goods, and might affect Western banks that have bought a lot of Chinese assets? Anyone know more about this issue?
This article in the Guardian about Harry Dent and his methods also forecasts a China meltdown. I dont generally have a lot of time for economists. I am sure that they are on the right track but predicting the exact date of a crash is very difficult. Bubbles can go on long after rational analysis says they should have burst.
For those investors with a more down to earth approach, an early indictor of a China slowdown might be their consumption of iron ore. China consume about half the worlds production of iron ore which of course is used for the production of steel. Its a big difficult figure to hide in a slowdown and for me it is an early stage indictator of problems
.
Paul,
As you know Equity Development's "Pre Registered" Investors all had the opportunity to participate in December in the Benchmark (BMK) IPO. The IPO price was 64p: the shares (7 weeks later) are 124p, up 95%. Over 50 of our (private) investors came in and made money. Private investors looking to participate in selected future IPOs should contact Equity Development for more details. email: hannah@equitydevelopment.co.uk for details
Hi Gilbert,
Thanks for that. Can anyone register interest in your IPOs, or is it restricted to investors with over a certain amount invested, or certain experience? Also do you have access to IPOs from various sources? How many more are planned?
Regards, Paul.
Hi Paul,
I know Caffyns quite well, I bought my Volvo from them and they service it. I have enjoyed better relationships/experiences with other car dealerships in the past. Caffyns are just OK, nothing special.
In fact I used to have drink with one of their branch managers at our local pub as he lived in the next village, he was quite a guy, very individual and eccentric, but very capable. All his staff loved working for him, he motivated them and lifted their spirits daily, he was the life and soul of our local pub.
I am a paraplegic, so I am not supposed to pay VAT on a new car or demonstrator if it is adapted for my disability before I take delivery. I bought a demonstrator and they charged me the VAT, six months latert I found out from the Spinal Injuries Association that I should not pay the VAT on a demonstrator. When I took it up with the sales team, they all told me that I was wrong, so I had a meeting with the eccentric and capable branch manager (who had been briefed by their own accountants that I was not entitled to the VAT back) He said it would take a bit of time but he personally would look into it as he loved a challenge. About six weeks he wrote to me with a cheque for the VAT that I should not of been charged.
Well the story ends with the fact that a year later Caffyns got rid of this very likeable and capable manager, who motivated his staff who loved him.
Good luck on Sunday Paul, if the predicted 80 mph winds are blowing from behind you should do a good time.
Best Wishes Neville
VP (LON:VP.)
Hi Paul, I think, given VP portfolio of divisions and the current weather, they could do well. In particular Torrent trackside should benefit from the 5year National rail programme starting in April 14 and the dameaged caused by the weather. TPA temporary roads and bridges, definatly will be needed given that the ground will remain wet for months. Hire station will know doubt benefit from people trying to dry out and repair buildings.
The point about CFYN is their huge discount to the rest of the sector 9 car dealwers)...generally these are trading on PE ratios of 12-15 whereas CFYN is likely to be around 6-8 based on earnings of 75 to 100p. On the other hand the shares are not very liquid!
Paul
Thanks for the report which is essential reading.
Good luck with the 1/2 marathon. Particularly if you are struggling with fitness can I suggest you take regular walking breaks from early on. A regime of 10 min running then 1 or 1:30 walking will lower your heart rate and increase your fat metabolism thereby keeping you running for much longer than if you run from the outset until you run out of puff.
Jon
Morning Paul,
I bought some Caffyn last year. The pension deficit looked manageable, but if you do look into them any further I would be interested in your take on that. But the thing that I was just a bit discomforted by, was the controlling interest held by the family, which can be thought of as - good, they share our interest in the progress of the company, or bad - they can effectively do what they want. They are afaics an old family company, so I assumed it's the "good", but would be interested in your opinion. In terms of the lack of profit forecast, I'm not aware of any that have been given, so it might be that saying they would beat or equal forecast was not an available option.
Regards, and good luck on Sunday!
Another bull market indicator imo is what happens when companies announce takeovers. Normally the price of the acquiring company drops slightly due to the risk of overpaying or the execution risk of integrating the acquired company - not every acquisition is in the best interests of shareholders although almost all are in the best interests of the company management. At the moment an acquisition usually ends up with the acquirers share price rising strongly e.g. Alternative Networks (LON:AN.) or Kentz (LON:KENZ). The statement that an acquisition is 'earnings enhancing' is meaningless when cash in the bank earns 1% - an acquisition for cash at 99 P/E would be earnings enhancing! A sign that the bull market is coming to an end imo will be when acquisitions are viewed more skeptically again.
Morning Paul
Given what happened with ACT, and your comments above, maybe Vince Cable isn't as big a numpty as people have implied?
(Take zinc tablets with vitamin C).
(Do I have to declare the interests that I once voted Liberal, and I have a cold too?)
Hi Paul
Re. ACT. We really are in crazy territory. The company revenues were £444k and a loss of around £700k in 14 months to 2013. A market cap of around £75m??? I had a good look at their admission document and not convinced that they have a great proposition. Certainly not an economic moat.
Regards, Ram
Good morning Paul,
Re IPO's would it be possible for Stockopedia to have a section that signals forthcoming new floats?
Also, if Actual Experience gained a listing yesterday is there a reason why it does not show up on Stockopedia today?
Hope the cold gets better soon, I find heavy doses of vitamin C (the effervescent kind) help a speedy recovery.
Andrew