Small Cap Value Report (20 Apr 2015) - MAR, WOR, TRI, TRK

Good morning!
UK Investor Show
I thoroughly enjoyed the UK Investor Show on Saturday. As always, Mark Slater's insights were absolutely superb, he talks unadulterated common sense. Another highlight for me was the recorded video from Nigel Wray, who was unable to attend in person unfortunately. He is another brilliant investor who is full of wisdom & experience.
I enjoyed the perspectives from the "bear pit" too. Bears don't always get it right, but if they turn on a company where I hold a long position, then I sit up and take notice. They're more often right than wrong, and bears are usually the most experienced & thorough (in their research) investors, so fighting them on bulletin boards is a pointless exercise, when we should instead be listening carefully to what they say.
The Stockopedia session with Ed was so popular that four rooms had to be amalgamated into one, and even then there were people standing & sitting on the floor! A few people got up to leave when I took over, but thankfully not too many lol!
Dozens of readers of this blog chatted to me, as I was wandering around the venue. Almost every conversation started with the words, "Hello Paul, I read your blog every day..."! I was thrilled to get such positive feedback, with lots of people saying how useful they find these reports.
One chap made a good point, he said that to save time, he skips to the "My opinion" paragraph in every section, and if I sound positive on a stock, then and only then does he read the rest of that section. What a good time-saving idea, for those of you that are very busy, so thought I would pass that idea on to you here.
It's such a pity the investing world is so male-dominated. I wonder what we can do to encourage more ladies to get involved too? Females apparently make better investors, due to being a bit more cautious than men, and less prone to taking a gung-ho attitude towards risk, that is the undoing of many of us from time to time. A friend was trying to point out someone they knew in the crowd to me, saying "He's the older gentleman over there, with grey hair". I responded, "That doesn't narrow it down much! Everyone in the room fits that description!"
I thought the bearish comments against Tungsten (LON:TUNG) were overdone, but contain an element of truth. Hence why I changed my bullish stance a few months ago, sold most of my shares around 240p, and am now neutral to mildly bearish on the stock, due to concerns over the high valuation, cash position, cash burn, and the over-hyped nature of their business model - which is not unique at all either - other einvoicing companies are doing the same thing by linking with finance providers to offer early payment options.
The next big event is David Stredder's latest initiative, Mello Workshops. Myself and the Stockopedia team will be there too. I'm looking forward to doing two presentations, one about balance sheet analysis (and how it de-risks your investing), and the other will be an explanation of my disastrous mistakes with gearing & illiquidity in 2008, and how my spread betting accounts blew up in the financial crisis. By telling other people about my own disastrous mistakes, hopefully I can forewarn others of the dangers of leverage. I've certainly learned my lessons the hard way! So I'm very careful about managing gearing & liquidity now.
Mar City (LON:MAR)
Shares suspended - it looks as if the NOMAD has resigned, which is a pretty poor show in my view. If a company gets into difficulty, then it needs its advisers to stick by it, not walk away. The problems with related party transactions are not new, everyone involved with the company knew, and had approved of the incestuous relationships between the listed company and other companies controlled by the Directors.
The cynic in me also wonders whether suspending the shares might not have been fortuitous, in that the share price was getting perilously close to the 34p level, which was the trigger point for HSBC to potentially call in the £10m loan to Directors, which had been advanced to them, secured on 43% of the entire company's shares being pledged as collateral.
Personally I ditched my shares in this company within 10 minutes of the profit warning, thus exiting at about 68p, thankfully. My personal rule is that if a profit warning contains serious accounting issues, likely to involve restating the accounts, etc, then it's an automatic sell - as things are always far worse than the company at first admits. So more bad news tends to follow.
That said, I don't think MAR is going bust. It has a sound balance sheet, but the net asset value of 62p (after restatements for the problems reported on 20 Feb 2015) is likely to be reduced again, in my opinion. The big debtor balances due from management are also questionable I imagine.
On the positive side, the company's modular housing does look very interesting, and perhaps with new management, it might make a viable concern. I couldn't invest with the current management still in situ though.
Existing shareholders are probably very worried, but I think the shares will come back from suspension fairly soon, when a new NOMAD is appointed. The Non-Exec Chairman has accelerated his departure too.
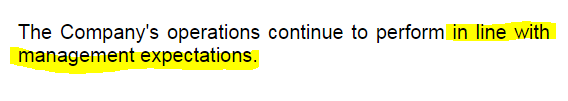
Also, note that the company reassures (for what it's worth, which is very little!) on current trading today, saying;
World Careers Network (LON:WOR)
Share price: 293p (down 19% today)
No. shares: 7.6m
Market Cap: £22.3m
(at the time of writing, I hold shares in this company)
Interim results - no wonder the shares are down 19% today, these are very disappointing figures. As you can see from the Stockopedia graphs below, this company has an excellent track record of growing sale & profits;
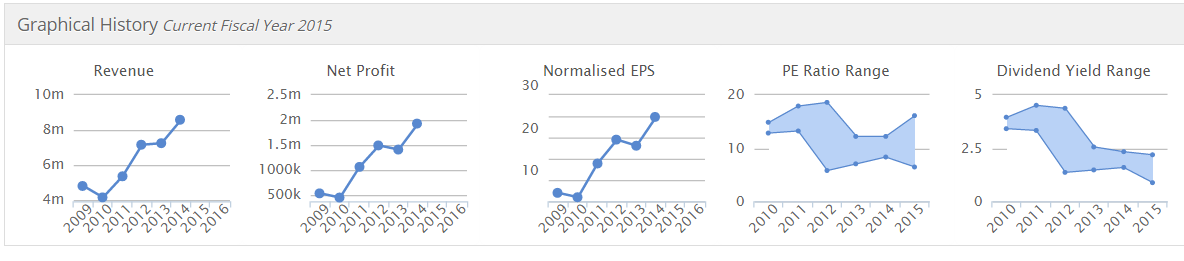
That good track record has collapsed this morning, with interim figures showing turnover down from £4.2m to £3.5m, and operating profits all but collapsing from £1,003k last time for H1, to just £287k this year's H1 (6 months to 31 Jan 2015).
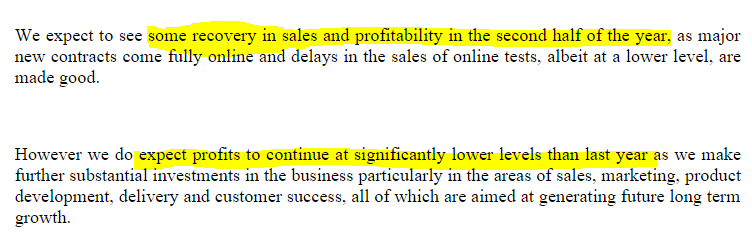
I was about to launch into a rant about how terrible it is that the company has not updated shareholders since the last full year results were published on 3 Nov 2014. However, on re-reading those results, the outlook section made it clear that things were going to be more difficult in the short term.
Outlook - some glimmer of hope in here, but it's hardly exciting;
Lack of liquidity - Lucian Mears made the very good point at the UK Investor Show, that one of AIM's main failings is that companies are allowed to list their shares with virtually no free float. This means that share prices in such companies can become completely detached from reality, and are extremely easy for people with bad intentions to manipulate - which is why there are so many "pump and dump" operations which happen on AIM stocks. It's the hapless private punter who ends up losing money on such scams, which are depressingly regular events on AIM, I'm afraid.
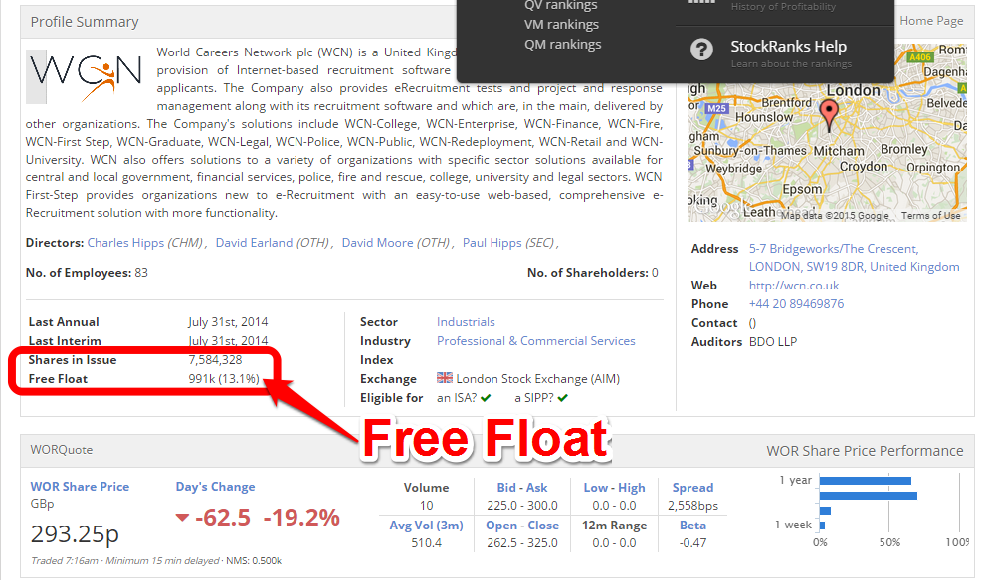
I don't think anyone is manipulating this share price, but the bid/offer spread is ludicrously wide, and the free float is so small that you can only buy or sell tiny scraps of shares, making it almost impossible to deal in. This is because nearly all the shares are owned by management & connected parties. Which makes you wonder why they want to have all the costs & hassle of a stock market listing?
My opinion - I am weighing up whether to sell my holding in this company or not. Probably the main reason that I haven't already hit the sell button is that the company reports net cash of £8.3m, which is more than a third of the current market cap.
Certainly I can't see any compelling reason to buy the shares now, which probably means I should sell up and move on. Trouble is, the price is currently 225p Bid, 300p Offer! A grand total of 10 shares have changed hands today. How ridiculous!
UPDATE: I've been pondering this some more, and have decided to chuck out these shares. Luckily, as I experienced severe illiquidity when trying to buy, it turns out that I only have 500 shares in my portfolio anyway, which was all I could get at the time! So I've sold them for 235p, and booked a small profit overall, so not a disaster. Memo to self: don't bother with highly illiquid shares in future, they're a waste of time.
For anyone not aware of where to find the free float figures on StockReports, I have highlighted where to find them on the screen shot below, near the bottom left of the StockReport. The figures are calculated by data provider Thomson Reuters:
Trifast (LON:TRI)
Share price: 108p (up 4% today)
No. shares: 116.2m
Market Cap: £125.5m
Trading update - there's a positive announcement today from this fastenings company;
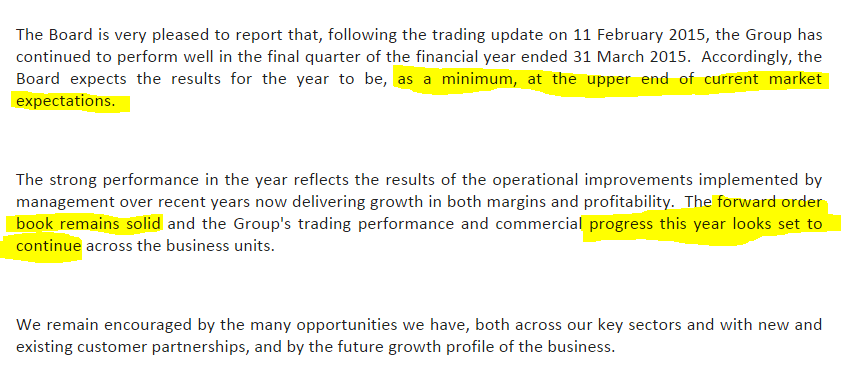
That all sounds really good to me.
Valuation - it's starting to look tempting. With forecasts of 8.06p for 2014/15 now in the bag, possibly a little higher too, and a strong outlook statement, then I am guessing that 9-10p EPS is possible for 2015/16. Therefore at 108p, the PER is probably about 11-12, which looks about right to me, although there is scope for the market to take it higher perhaps?
My opinion - this company has been doing well for several years now, and is a good turnaround. The valuation seems reasonable, although the divi yield isn't great, at only 1.7%.
My main reservations are that I'm not sure how much growth potential there is? After all, industrial fastenings must be a highly competitive sector. What is driving the current strong performance? It might be the buoyant European car manufacturing sector perhaps? How might the group be affected by exchange rate volatility?
Overall, it's probably more likely to go up than down, from this point, but the upside isn't quite clear enough to persuade me to buy any. But I'm leaning towards picking up some, just need to do a bit more research into the questions above.
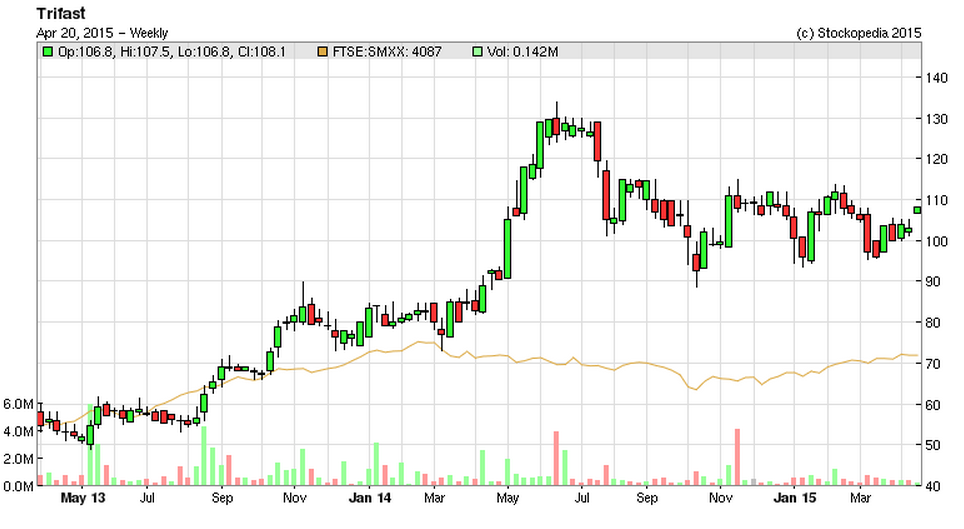
The chart is perhaps showing that sentiment might be turning more positive too? Note the three higher lows in recent months, which is usually a good sign;
Torotrak (LON:TRK)
Share price: 8.9p (down 2.8% today)
No. shares: 276.3m
Market Cap: £24.6m
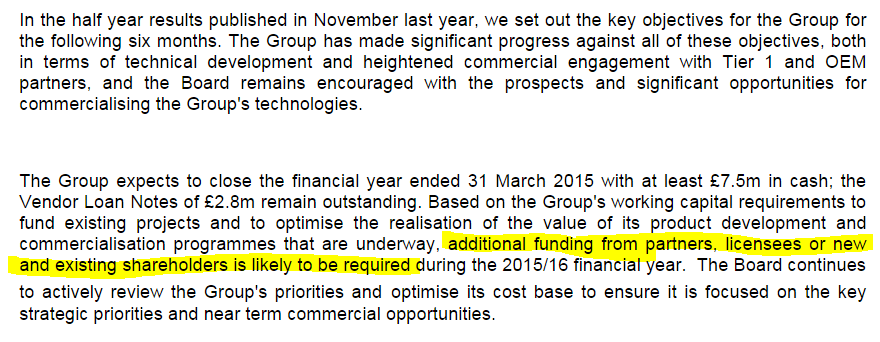
Trading update - regular readers here will know that this is one of my least favourite jam tomorrow stocks. It's been trying to commercialise various automotive technologies for what seems like forever, and every couple of years it comes back to the market for more money.
Also, as the existing technologies get nowhere of any commercial significance, they branch out into other areas, which also seemingly get nowhere. Yet there are always deals with tier 1 manufacturers in the pipeline, partnerships, etc, but never any profits. Sorry, there was a £390k profit in 2010, amongst a sea of losses every other year.
The StockRank is only 4, and after hearing Ed's talk on Saturday, I am increasingly coming round to the view that I should only allow myself say 10% of my portfolio maximum, in all shares which have a StockRank under about 75. I think that would be a good discipline.
I was chatting to the Stockopedia guys after Saturday's show, and we agreed that Stockopedia should do our own investing show. We could extend an open invite to all companies with a StockRank of over 75 to attend, and bar everyone else! OK, we would probably lose money on it, as the poor quality companies are usually the ones who want to get in front of investors to talk up their share price, but you never know.
So going back to Torotrak, basically everything is going great, except that they're going to run out of cash again this year!
My opinion - it's just more of the same from this company, I'm afraid. Maybe one day shareholders will get lucky, who knows? It remains uninvestable as far as I'm concerned. I would never buy into such a serial disappointer.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Hi Paul
No Paul, that must have been a different David Talbot, although I did manage to grab a quick word, with others, when you were surrounded at the UK Investor Show.
I totally agree with your assessment of the usefulness of the many superior features Stockopedia has (I wonder now how I ever managed without it) and your other ideas.
Best wishes
David Talbot
Hi David,
Yes, I was pretty sure we'd chatted on Saturday, so my apologies for forgetting the exact subject matter, I was rather inundated, as you alluded to! Still, it's great to meet readers of the blog, I really enjoy it, and everyone is so nice in person - even people I've crossed swords with online are always charming in person - and there's usually mutual embarrassment, wracking our brains to try to remember how rude we'd actually been to each other online, and apologising!
I can only recall one person who was obnoxious in person, as well as online, and that was about 10 years ago at a Motley Fool social. I just smiled & said nice to meet you, and walked off. No idea who he was.
Regards, Paul.
I wholeheartedly concur with PP's wanting to see more female investors. I bought my first shares at the age of 12, encouraged by my father, after a modest premium bond win & continued to invest in equities for the next 30 years.
I now have 3 children & have started equity portfolios for all 3 with modest monthly contributions. All 3 look at their portfolios & discuss the companies with me; hopefully I am starting them off on a successful interest which will empower them through their lives. I believe that financial education & encouragement of girls (& boys) in secondary school will be vital to empower the next generation & produce successful investors.
As to attending trade shows/ investor forums, I would very much like to go but with school age children& full-time work, this is very hard to arrange so please keep up the updates
I am apparently the only member who thought mikehunt's comments were appropriate. They attracted useful clarification from Paul on his frequency of trading in some circumstances and the temporary nature of opinions. However, I thought some of the comments in this space on mikehunt's comments were not constructive.
(I wonder whether the country might run better if politicians were allowed to admit to changing their minds when facts change.)
Hi Splode,
It's absolutely fine for any reader to ask me to clarify particular points.
What is NOT fine is to open the questioning by accusing me of lying, on the basis of taking 2 + 2 = 5, which is basically what the reader above did today.
He wouldn't have phrased it like that if asking me in person, so why is it OK to adopt such an approach when hiding behind a fake name, and the safety of an internet connection?
As you know, I'm always happy to clarify anything, so people only need to ask. It makes life a lot more pleasant however, if people ask first, rather than shooting me down with false accusations, sprinkling in some completely invented statements of their own about my portfolio, quoting selectively from two reports here, whilst conveniently ignoring the report in the middle which disproved their accusations.
If everyone behaved like that I wouldn't bother writing any more reports. Thankfully however, the vast majority don't take that approach.
Regards, Paul.
Re TRIFAST which is a big holding for me - good media interview with Executive Chairman which is even more positive than the RNS. Encouraging (to me anyway).
http://www.lse.co.uk/share-media.asp?shareprice=TRI&share=trifast
What minimum free float % will you be using going forward?
Hi Paul,
'I wonder what we can do to encourage more ladies to get involved too? Females apparently make better investors' !
Sadly from my bitter experience they do tend to spend the money!, as I watch the estranged walking off into the sunset with her 300 pairs of shoes and her 19 suitcases packed for her next cruise.
Paul I do remember your wonderful words of wisdom to me, "don't worry Neville, think of divorce in the same way as CAPEX, you will be better off in the end"
I have been a bit reclusive lately, but I am looking forward to catching up with you Paul and all my investor friends at the various events.
Cheers
Hi Neville,
Good to hear from you & sorry about your problems.
I've been thinking about this a bit more, and in my view perhaps it's best to regard divorce as a major restructuring, with a large one-off exceptional charge to the P&L. Whilst painful, this kitchen sinking will leave your organisation more efficient, and with much lower cash burn in future years! ;-)
Regards, Paul.
Absolutely Paul,
I am very positive, and I am seeing this as a fantastic new opportunity to create the life that I want to live. I can now really focus on several long term ambitious projects that were fading away from me.
So the portfolio will be much smaller, but like you proved starting all over again after 2008, I will not give up either.
Kind regards, Neville
Well done Neville, and as I've said to you before, your positive outlook on life is inspiring to people who know you.
In my experience, the key to rebuilding a portfolio is keeping living costs low. My portfolio is still nowhere near the size it was in 2008, but I hardly have to withdraw anything for day-to-day living costs, having built up other sources of income.
Also, living a more normal life, rather than an extravagant/flamboyant lifestyle is actually more peaceful and pleasant in some ways, I've found. You don't have to worry about impressing anyone, and if the bills are only a small amount each month, then you can sit back & relax knowing that there's ample money to cover outgoings, even if the portfolio is not huge.
In that set of circumstances, I think it's easier to make mostly good investing decisions too. Whereas if you have humungous monthly outgoings, then the pressure is on to make a profit all the time from the stock market, which of course eventually tends to go wrong.
Regards, Paul.
Reading Paul's comments on Tungsten (LON:TUNG) reminds me of the comments attributed to JM Keynes: "When the facts change, I change my mind. What do you do, sir?" I would prefer to see Paul change his views based on new evidence, rather than trying to massage the facts to fit the unchanged opinion.
Hi Paul
I have just seen on twitter you are thinking about shorting Mitie (LON:MTO) . A relative works for them, and some time ago told me the company had massively underbid in order to get some large contracts. They are now running these at a loss, and may seek to exit them. Additionally they seem to have got rid of most of the 'low value' work they did, such as cleaning and security, in favour of higher margin engineering and maintenance work. The problem is, I am told, the management are not up to the job. 'Omnishambles' is one prhrase being touted about! Good lluck with it if you decide to have a go.
Hi Beginner,
That's very interesting scuttlebutt about Mitie (LON:MTO) thank you.
I shouldn't really talk about it here, as I did open a short today.
Regards, Paul.
Hi Paul
Further to your comments about MITIE " I shouldn't really talk about it here, as I did open a short today", I also refer to my earlier comment above about your daily report "In my view, this daily report has only one shortcoming and that is that he is not allowed to comment on shares in which he is short. Note to Ed Croft: address this issue, please."
Unless Ed has some moral objection to shorting (and, if so, why are there short screens on Stockopedia?) I really do not see the reason why you are not allowed to comment on shares in which you are short. Of course, this ban does lead to gaps in your reporting on Stockopedia which persons who do not know the situation could misconstrue. For example your unavoidable, intermittent past history on commenting on Quindell here, according to whether or not you are short at the time.
You are allowed to comment positively on shares in which you are long, and you are allowed to comment negatively or positively on shares in which you do not have a position. What is the logic, therefore, on your not being allowed to comment on shares in which you have a short position?
Clearly, these are rhetorical questions as far as you are concerned: they are addressed to Ed.
Best wishes
David Talbot
Hi David,
I take on board your points, but it's down to basic economics - there are I'm afraid a relatively small number of very naive subscribers who have threatened to cancel their subs here when I used to mention stocks that I was short of. They tried to get me sacked too - obviously there was never any chance of that happening, as I'm totally fabulous!
So we had to be commercial about it, and after all, I don't want to undermine the site by driving away subscribers. I could have just not disclosed when I was short of a stock, but I don't do things that way - everything always has to be 100% transparent - even if, as today, I might get the detail/timings slightly wrong on disclosures relating to past transactions (as done from memory to save time), the broad thrust will always be correct.
So a balance was agreed whereby I agreed to not talk about stocks where I have short positions. Instead, I just talk about them on Twitter, where of course I'm free to say anything I like.
Ed has to strike a balance between letting writers say what they want (and he's brilliant at that, I'm given complete editorial freedom, which is wonderful!), but also being commercial about the site, by not having writers drive away subscribers.
Generally I think people totally understand that the reservations I express about many stocks are usually correct. But once I actually short them, I have to stop discussing them here. That's fine, I can live with that. But I do fully appreciate your point that, for more sophisticated investors, it's annoying that things have to be done this way to appease the type of novice investors who only ever want to hear positive opinions on their favourite stocks, and actively try to shut down negative views from commentators.
Regards, Paul.
Hi Paul
Thank you for the explanation, although I still think it a great pity that a few small-minded subscribers are allowed to circumscribe your comments on Stockopedia, to the detriment of what I am sure are the overwhelming majority who want your unfettered opinions at all times.
I quite agree that you are "totally fabulous", although it is a good job I did not add modesty, when describing your qualities in an earlier post.
Keep up your excellent work; it is very much appreciated.
Best wishes
David Talbot
Thanks David,
I recognise your name - are you the same David Talbot that I was chatting to about my plans to do a Cheshire investor evening, at the investor show on Sat afternoon? If so, it was good to meet you.
These investor shows are becoming very social, especially around the Stockopedia stand & presentations. Many, maybe most (?) of the people who gather & interact with us at these events are already subscribers, and are very keen to hear Ed explaining features of the site, and how best to use it. I know you can get much of the data elsewhere, sometimes free, but in my view the real value of this site is that it presents things in such a way that you can very quickly home in on good stocks.
Mark Slater used Company REFS to illustrate his points, and I couldn't believe how old fashioned and user-unfriendly it looked in comparison. Company REFS is only good if you have used it for a long time, and know where to look for everything, but in my view Stockopedia is far better - the colour-coded graphics just leap out at me when I find a good stock, as my subconscious knows exactly what to look for (in a nutshell, high quality scores, with low valuation scores, especially PER and divi yield), plus a good progression of divi payments, low debt or net cash, little to no new shares issued in last 6 years, positive current ratio, reasonable PTBV, decent liquidity, and a few other things. Then I can check the Annual Report and RNS for the other things I look for, e.g. hopefully no pension deficit, reasonable mgt shareholdings, sensible Insti shareholders with >3% holdings, reasonable share options, strong outlook statements, a track record of delivering in line or above market expectations, etc.
Maybe Stockopedia and Mello could join forces, to create the Rolls Royce, or maybe the Jaguar, of small cap investor shows in future, to supplement the existing offerings? The more the merrier, in my view. With investor shows, I usually listen to the key talks, do a talk or two of my own if I'm invited to do so, then slope off to the pub with one or two other reprobates by mid-afternoon!
Regards, Paul.
I just wanted to add my criticism of MikeHunt's completely unnecessary comment. Please Mr Hunt go elsewhere. Paul's blog is without value or equivalent and an amazing resource for all who read it. I read it EVERY day and I can say that about nothing else.
The blog is an education to newbies like me and it has definitely saved me from making huge mistakes and I have learnt so much from it. Not least that investing in the likes of Tungsten (LON:TUNG) is not for me!!
Paul thank you, thank you, thank you. Please don't let the Hunts of this world get you down or derail you.
Michael Broom Smith
The Torotrak – SFTV
The Torotrak system has evolved from work done by the British government shortly after the second world war. One of the individuals involved was Forbes Perry a British engineer who was the motivating force behind this work and developed the Perbury Variator in parallel with this work.
Says it all. When exactly will the profits arrive?
hi
I don't understand the comment!:-)
Anyone who takes his username from the 1982 teen comedy film, Porky's has to be viewed with suspicion.
If you have been investing for more than a few years you will have had your fair proportion of losers as well as winners. It is how you deal with the losers that will likely determine your chances of success. To be fair to Paul he is usually quick to admit his investment mistakes and update readers accordingly. I think that takes considerable courage given that this is a public forum.
I couldn't agree more with your comment, 'I thought the bearish comments against Tungsten (LON:TUNG) were overdone'
After enjoying informative and interesting talks from Yourself, Ed Croft, Luke Johnson, Paul Jourdan, Mark Slater and so on, from which I learned a lot from. It seemed a shame to hear such an unbalanced view, one of them describing Tung as 'S***' just made me switch off. Even though I'm sure there's some truth to their points would of been a lot more useful to hear about these 'estimates via Cenkos' you mention, something with substance. Rather than just 'why did they buy a bank' which seems to be countered by the deposits drive and ability to operate in various countries.
I don't recall anyone at the UK investor show calling Tungsten "S***". What I do know is that, although neither is clearly infallible, both Matt Earl and Lucian Myers have a good record on shorting and that if both is negative Tungsten, then that is a concern to me. My own notes show Lucian thought Tungsten would implode: there was no cash generation and that the business model was taken out of "Alice in Wonderland". Clearly, at the end of the day, make up your own mind.
With regard to Paul Scott, anyone who has met him knows that he is infinitely generous with his time and infinitely polite, helpful, straightforward and honest. I am another who would not miss his daily report here. In my view, this daily report has only one shortcoming and that is that he is not allowed to comment on shares in which he is short. Note to Ed Croft: address this issue, please.
https://www.youtube.com/watch?v=lbkAQLD8-lY
23.59: "It's a piece of sh**, isn't it?"
Ed / Paul
Organising a show for companies above 75 stockopedia ranking sounds like a great idea!
Can I strongly recommend that you don't use Edison Investment Research to help you - they are really cynical bunch of so-and-so's. I did some work for them and they never paid me, because they felt that "I didn't fit their culture"...which I think was code for I questioned the revaluation gains in the balance sheet one of their corporate clients wanted me to uncritically cheer lead. I could have taken them to court - instead I just tell anyone who will listen what they are like. I also think you should remove their research from your website.
Not sure what point MikeHunt is trying to make but as Paul suggests the appropriate course of action for him to take is not to read what is a very useful and FREE blog. It beggers belief that somebody can criticise something that is both free and useful.
Hi Andrewdb,
"How do I - or others see this note?"
With varying degrees of difficulty, I'm afraid.
Under the existing rules, PIs are deemed too stupid to be able to receive broker notes, therefore most PIs are blocked from receiving them. You can receive broker notes if you are classified as a professional investor, and/or high net worth. We really should be lobbying Govt hard to have this rule changed, as access to broker notes would greatly improve the information available to PIs.
The brokers who write research notes do so partly as a value added service to their clients, so if you're not a client of theirs, then it can be difficult to get hold of notes.
In practice, PIs tend to form networks, who distribute broker notes amongst themselves by email, to get around these restrictions, but it means that access to research is patchy & often not very timely.
Some companies help by publishing broker research on their websites, I really wish all companies would do this.
Regards, Paul.
Good afternoon
"In the case of TUNG, the company drastically lowered its earnings estimates via Cenkos, but didn't flag this up to the market at all...."
How do I - or others see this note?
I've been following Paul's blogs/tweets for some time and more recently the SCVR.
I far from agree with all of it, but some of his research often acts as a 2nd opinion on some of my research which I find invaluable, almost like an imaginary investing friend,and I like the fact, like me he makes mistakes and isn't afraid to come on here and say so. I suspect most of us probably don't even admit them to ourselves.
It's sad there seems a determined element who want to bash anyone who is successful.
To put yourself in the firing line day in day out takes a certain type of person that regardless if this sounds like I am blowing smoke up his **** you can't help but have a certain admiration for in this horrible world where the anonymous feel they have to rule over the rest with their nastly words. Having been on the end of similar abuse I for one is glad PP doesn't let them get him down as I wasn't that lucky.
Keep up the (mostly) good work Paul.
Thank you for your comments on Trifast (LON:TRI). I am a holder. They comment in their statement of 11/02/2015 that:
This trend is expected to improve further over the short to medium term as we focus on converting the opportunities to extend our 'preferred supplier' partnership status outside the traditional European OEM plants into numerous sister plants in Asia and the USA.
Their big industrial customers such as car plants will only buy from approved suppliers. So it looks like a good way to grow sales by attempting to get such approval from the existing customer's sister plants.
I too noticed the lack of female PIs at the event - I had assumed that this was to be expected, but maybe it was greater than you had expected, perhaps because the strong bearish theme can come across as negative and overly aggressive in some minds.
With a female population that is living longer than the male one, with pension reforms giving greater independence to the individual, and women feeling less likely to defer financial decision making to their menfolk than in previous times now is clearly an opportunity to the PI advisor/market leader who can most effectively reach out the female investing population.
Much as the libertarian PI (TW I may mean you) may dislike the basic idea or appealing to women in different terms to men, and may criticise it as a form of left-wing tokenism, there is also a strong theme in marketing (which not known for its left leaning credentials) that states that you need to approach each market segment in its own way, and using language that most effectively resonates with that segment. It is a logical conclusion that in order to bring out this language that women need to have a platform upon which they are encouraged to stand and talk about share valuation and share dealing. and I mean platform in a real sense - a session at next years UKIS show, a share blogger on here - that kind of thing.
I am pleased that you have raised this issue and look forward to a bit of serious discussion on Stockopedia on the subject.
By the way I am not a woman, but felt somewhat uncomfortable about the female investors at the show being outnumbered by the 'trolley dollies' who were paid for by one of the exhibiting companies to be scanning people into the main hall. I had thought that in 2015, in Britian, we might have got beyond such stereotyping.
Paul you claim to have "mostly" sold out of TUNG at 240p (which he didn't, he capitulated at 160p at which point he sold, then bought back, then sold again) yet this is what he was saying last time TUNG was 240p:
"...why I've made this about my 2nd or 3rd largest long position in the market."
http://www.stockopedia.com/content/small-cap-value-report-14-jan-2015-tung-gmd-90266/
Didn't sound like he planned to sell that exact same day did it? Now he's a Hindsight Harry seller at 240p?
At 160p:
"... I have sold all my shares, for a loss unfortunately".
http://www.stockopedia.com/content/small-cap-value-report-24-feb-2015-tung-mar-craw-vp-dotd-92834/
and yet:
GBO
paulypilot - 11 Apr 2015 - 08:14:50 - 22188 of 22197
TUNG - I got it wrong. Breakeven for me personally.
and today
"..sold most of my shares around 240p".
http://www.stockopedia.com/content/small-cap-value-report-20-apr-2015-mar-wor-tri-97035/
(in contrast to his own blog dated 14th Jan).
A disappointing transparency from Paul as shareprophets continue to adversely influence him imo.
Mikehunt,
I think I know my portfolio better than you do!
I traded Tungsten (LON:TUNG) shares numerous times, and as it's a difficult company to value, my feelings about the company ebbed & flowed, it's what happens with speculative shares unfortunately.
As the shares were falling, I remained bullish, but then as the losses mounted, I trimmed my position back, then sometimes added to it when the shares seemed to be bouncing, etc.
Changed my mind on it numerous times, but I remained broadly bullish, but not happy to hold a large position in it, as the share price was falling too much for everything to be OK. You have to listen to what the market is telling you sometimes.
However, by about 240p I had reduced what was previously a very large position, to a modest one, but remained bullish, but unhappy to hold a share that was constantly falling. Without checking my records, there may have been some left at 240p, but I know for certain that I'd sold out completely by 200p.
I bought about 150p for a bounce, then sold out around breakeven a few days later.
Disappointing to read your unpleasant post. Might I suggest your stop reading my posts if you don't like what I say.
As regards transparency, you couldn't be more wrong. I'm a completely open book, always have been, always will be. I tell the truth as I see it at any point in time. It was very difficult to tell readers that I'd turned bearish on Tungsten (LON:TUNG), but that was the truth as I saw it, and remains so.
Paul.
Re Tungsten (LON:TUNG) I've checked back on my trading records, and I began trimming back my position on 19 Jan 2015, due to the share price continuing to fall.
I then sold in various tranches over the next few weeks, as my confidence in the company was further undermined by bearish articles written by Matt Earl, an analyst who I have lots of time for.
That is entirely consistent with my blog posts here. You highlight that I was bullish on TUNG on 14 Jan 2015, which I was, and it was indeed one of my biggest holdings at that point in time. Facts which were reflected in my blog post here of that day.
However, in my report dated 16 Feb 2015 I stated very clearly that "I have gone wobbly on this share in recent weeks", and sounded a clearly worried message about the shares to readers here, when the share price was 212p. I see that you have conveniently ignored that fact in your post here, presumably since it disproves your narrative?
My concern continued to build, and I sold my last TUNG shares at 208p. Again, entirely consistent with my posts here throughout.
Maybe I wasn't mostly out by 240p, perhaps it was 237p or 229p, but it was in that ballpark anyway. I don't have time to check the precise accuracy of every comment when writing these posts, I'll just give a ballpark figure which from memory will be reasonably accurate.
It's extremely disappointing to have a reader with an agenda, trying to pick through previous posts, to uncover discrepancies which you have imagined. All my posts here are truthful, in terms of how I see a share at a particular point in time. Those views are subject to change. I state in every article whether I own a share or not. That is the only disclosure required, as none of my posts are recommendations at all. This is an opinions-only blog. Again you know all of that.
Yes I was influenced by bearish posts on ShareProphets by Matt Earl. He made some good points, and made me question the valuation on TUNG, and its business model.
There are no prizes for doggedly sticking to a bullish point of view, when the bull story is actually unravelling. Being able to change your mind when the facts change, is a key strength in the investing sphere, as is also the case with many other spheres.
In the case of TUNG, the company drastically lowered its earnings estimates via Cenkos, but didn't flag this up to the market at all. So only people who managed to get hold of the updated Cenkos note realised that actually the original business plan was not working out anything like it was forecast to do. So the reason the share price was falling heavily was because Institutions were probably selling up, before us lot were made aware that things had deteriorated. Usual story I'm afraid.
I do recall some of my more switched on investor friends starting to go wobbly on TUNG in Jan-Feb, which is what made me think again, and flag up my concerns here on 16 Feb 2015 at 208p per share.
Paul.
maybe it would be good if "MikeHunt" posted under his real name and provided full transparency of his own, rather than masquerading under a pseudonym and trolling under anonymity hiding behind his internet connection.
@belly,
quite often they are tiny companies trading on the PLUS market(formally the OFEX market).
CMCL.L for instance has a market cap of about £22M, and trades on the PLUS market I think.
Regards
"Note the three higher lows in recent months, which is usually a good sign"
Check out the chartist! You'll be talking about moving averages before you know it....
@Belly,
when you ask for a "quote" through a trading account is would tell you then, possibly by having to route an order to be executed etc on a matched bargain premis.
Or you may not be given a quote online, phone your broker and they would inform you.
Regards
Cheers, I'll take a look next time I trade.
@mrwhits: Re liquidity
How do you get information on whether a share is only being traded as "matched bargain"?
It would be a useful thing to add to the "buy" checklist.
Hi Paul,
Re liquidity, I also pass on companies that you cant buy in decent quantities in one go(usually more than say £10K worth) AND more importantly "matched bargain" shares, as I find that you can get quoted any old tosh price which if you don't like you cannot trade in them.
I've recently passed on CMCL.L for this reason, matched bargain trading only, ripe for unscrupulous directors dumping, or hoovering up expensive/cheap shares in an almost unregulated way!
Good to hear you enjoyed the UK investor show. Would it be possible for you to share some/all of your session with the stocko crowd?
As another side, do you still record a Sunday audiocast with Dave Stredder? and if so where can I find it please.
Regards
mrwhits.
Re. Free Float data.
I agree it is very easy to overlook this important factor especially for AIM traded shares. The StockReport page does show this figure but it is buried way down the report page and easy to miss.
A request for Ed C to move this item further up the StockReport page? One for the 'nice to have' list, I would suggest.
Thanks
Please , please, please get your tickets for this weeks Thursday and Friday workshops as quickly as possible if you do not have them already as the popular workshops which include Paul and Ed and a few other very well known investors are getting very heavily booked. www.melloevents.com/mello-workshop/ and use the STOCKDISC discount code to get vastly reduced tickets at just £20 for one day and £30 for two days. The full programme and company presentations are all available to see on the website
David
Morning Paul.
Re Tungsten (LON:TUNG) I agree there are lots of competing offerings in it's market pIace however it is unique in being the only electronic network that has a bank and has opted to be regulated as one. This gives it access to markets such as Germany where Invoice discounters are required to have a banking licence. I believe this will give Tungsten an edge going forward.
Although hard to value I suggest it's valuation is attractive compared to competitor Taulia which is eyeing a $1 billion IPO yet has an inferior offering. Certainly the CEO seems to think so having spent circa £4.7m on shares since the IPO.
Very much looking forward to hearing your talks at Mello especially the spreadbetting one!
Jon
Good Morning Paul - can you provide any insight into any of Mark Slater's recent purchases? Thanks,
David