Small Cap Value Report (21 Apr 2017) - REC, CAY, IDH, PEB

Good morning,
It's Paul's day off today, so I'm planning to cover 3-4 of today's stories in his absence. First up is Record (LON:REC):
Record (LON:REC)
Share price: 42.375p
No. shares: 221.4m
Market cap: £94m
This is an unusual type of asset manager, as it is focused on currencies rather than equity/fixed income.
One might ask: when clients want hedging or currency-derived returns, shouldn't banks be the go-to provider? How can a smaller institution compete with them?
On the hedging side, it doesn't surprise me that there is space for a smaller, independent player. After all, there are plenty of currency brokers dealing with the retail market, providing individuals with advice and better rates on their FX needs when they expatriate/repatriate, buy foreign property, etc. Think of Record as a large, institutional version of this!
And on the currency-derived return side, Record acts similarly to any other independent asset manager or hedge fund.
So, in principle, I'm very comfortable with the idea that there is space for an independent currency specialist, focusing on institutional clients.
The track record of profitability isn't bad either: profits were reset lower during the 2008-2012 period, but have been stable since then.
Which brings us to today's update:
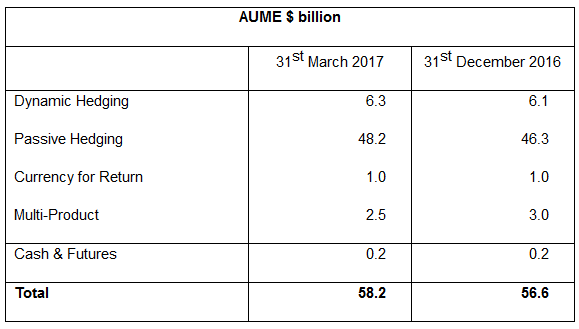
So it's a 2.8% gain in USD terms, and also a 1.7% gain in GBP terms.
My opinion
I'm kicking myself a little bit when I look at the share price chart - even after today's slide, the shares are higher than they've generally been over the last couple of years.
Admittedly, it's not the easiest investment thesis.
On the positive side:
- The company has always been financially strong. At the last interim results (for Sep 2016), it had a tangible and liquid balance sheet which included cash and short-term instruments worth some £36 million.
- In the absence of strong growth, dividends have at least been generous relative to earnings (1.7p divis in 2016 versus 2.5p EPS).
On the negative side:
- The client base is not too well-diversified. According to today's update, the number of clients has reduced from 64 to 59 (this time last year, it had 58 clients).
Note that today's update shows AUME up by $1.6 billion, but $2.1 billion of increase was due to movements in global stock markets and exchange rate movements. So the underlying client flow was marginally negative. And another client will be terminating a $1.2 billion mandate during the current quarter.
Today's outlook statement mentions "good engagement" with clients in the current environment, without suggesting that performance is about to dramatically improve.
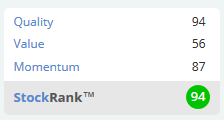
So I'll probably continue watching this from the sidelines, despite the excellent StockRank.
Charles Stanley (LON:CAY)
Share price: 315.5pNo. shares: 50.7m
Market cap: £160m
Trading Update and Notice of Results
Includes the magic words: in line.
The Group is maintaining positive momentum across all divisions and trading is in line with management expectations.
Charles Stanley has a March year-end, so (like Record's statement today) this is a Q4 trading update.
The broad movement seems very good:
Total Funds under Management and Administration ("FuMA") at 31 March 2017 were £24.0 billion representing an increase of 5.7% against £22.7 billion at 31 December 2016 and 17.1% compared to £20.5 billion at 31 March 2016.
And the outlook statement tells us that "conditions remain favourable" as the company works on a range of objectives - improving net flows, productivity, operating performance and the balance sheet.
On balance, it looks a reasonable proposition at a PE multiple of 15x and a dividend yield of 3.4%.
Immunodiagnostic Systems Holdings (LON:IDH)
Share price: 297.5p (+1.7%)
No. shares: 29.4m
Market cap: £87m
This swung to a huge loss last year, but the shares have now more than doubled from their low as the market has apparently decided that whatever problems exist here aren't terminal!
Immunodiagnostic Systems ("IDS") produces "manual and automated diagnostic testing kits and instruments for the clinical market".
Today's update tells us that revenues for the year are expected down 8% at constant exchange rates (CER), or up 4% at reported exchange rates.
I can't find many bright spots in the statement, unfortunately. And I wonder about the quality of company's IP portfolio, given the weakness in several income streams.
There is definitely a lot of value in the balance sheet. Cash increased to £31.5 million.
Might be worth keeping an eye on, as it does have the financial flexibility (and therefore the time) to attempt a turnaround.
Pebble Beach Systems (LON:PEB)
Share price: 5.125p (+1.7%)
No. shares: 124.6m
Market cap: £6m
I thought I'd mention this in passing, even though it's below the traditional £10 million cut-off, as it's often been mentioned on these pages.
The group's bank debt was reduced from £17 million to £12 million by the sale of Vislink, and today it's announced that there has been some progress in relation to a $2 million Vislink debtor (where Pebble Beach expects to collect the money with the help of the US company which purchased Vislink).
The bank are said "remain supportive" despite the company's forecast (31 March) that it will be "in breach of its banking covenants for the foreseeable future".
The best case scenario looks to me like a substantial equity raise, to clear the bank debt, if shareholders can be convinced.
That's it for today - have a good weekend!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Record (LON:REC) As the last trade was 10% of day's trade what means a second price monitoring extension at the close?
I have to commend Immunodiagnostic Systems Holdings (LON:IDH) on their shareholder communications. They are remarkably clear and unusually frank for a small company. I wish more companies let you see the equation for revenue rather than just the result. The annual letter from the Chairman gives a comprehensive overview.
You have to imagine that Vitamin D testing revenues (particularly for the automated assays) are at risk of approaching zero eventually as the continued shift of Vitamin D testing to the large diagnostic companies continues (with Bioventix (LON:BVXP) being a beneficiary of this shift with double digit licensees). I guess the good news is that they managed positive net placements and expanded their testing menu (though by less than their stated intention). If memory serves they also have a deal in place for allergies with Omega Diagnostics (LON:ODX) which could prove an interesting catalyst.
On Record (LON:REC), I was a holder when it was below 30p, and I'm kicking myself for cashing out at 30p.
The reason why I cashed out was the concentration risk in a few big investors, as well as the fact that for many quarters (and including this one) they didn't earn any performance fees, which means they're not delivering great returns for their investors. As an investment fund, if you're not delivering great returns for your investors, they're going to pull out their AUM and go elsewhere in the long run.
For me, that is the main reason why I don't hold REC.
Quite a drop on Record today. Im surprised but possibly because no mention of the special dividend which some holders myself included may be holding for.
ONS data on Q1 2017 retail sales released today looks interesting. Clothing sales are up by a respectable amount which is promising for the likes of Next (LON:NXT) which has received some attention on this report recently. Costs might be going up too of course but part of the worry around Next (LON:NXT) and clothing retailers was the potential for lower sales as higher costs get passed on.
re Record (LON:REC) I don't like the fact that free float is only 32.6% (Stockopedia data) the majority share holder being a Neil Record at 32.06% (Morningstar data)
Thanks for the update on Record Graham. It is a share I have held for some time. I was pulled in by the good cash flow and strong dividends, which are supported by Employee purchases and should continue to grow. I have heard ex share holders complain about the company's attitude to share holders but given their own holdings have always been a little cynical about this claim. Divi seems covered well enough at this stage. I used to work in the Institutional business so understand the clients pretty well. It is unlikely a group of clients would work in unison to leave ( Local Authority more likely to leave together) but not got the breakdown of clients. Investment Consultants can be a risk as they are quite concentrated Mercers, Towers Watson which Myners highlighted all that time ago.But all in all with increasing world upheaval there should be demand for a good currency hedger like this. I would like to see them develop a higher margin product but everyone can see consistent active returns in currency are a tall order. That said their operating margin is high which is something I always look for as it provides good defence against dropping demand. Well that's my tuppence appenny for what it is worth.
Thanks for the insights camtab.
Anyone Know why COG have suddenly taken off?
Simon Thompson article in this weeks Investors Chronicle. He concludes:
"Having considered all the risks, I still feel that Cambridge Cognition’s shares represent a good investment at the current share price, on the proviso of course that management hit their budgets and deliver on finnCap’s earnings estimates. If they do then I feel a cash-adjusted rating of 25 times 2018 EPS estimates is a much fairer valuation, implying a target price of 130p, in-line with finnCap’s own objective."
Denis,
Cambridge Cognition Holdings (LON:COG) are up on a Simon Thompson article in the IC
Edit - you wait 30 minutes for a reply and two come along within 30 seconds!
thanks guys