Small Cap Value Report (24 May 2016) - TPT, ACSO, PTCM

Good morning!
Topps Tiles (LON:TPT)
Share price: 136.4p (up 3.9% today)
No. shares: 193.1m
Market cap: £263.4m
Interim results, 26 wks to 2 Apr 2016 - the numbers look solid. Here are the KPIs, with my comments on the highlighted items below:
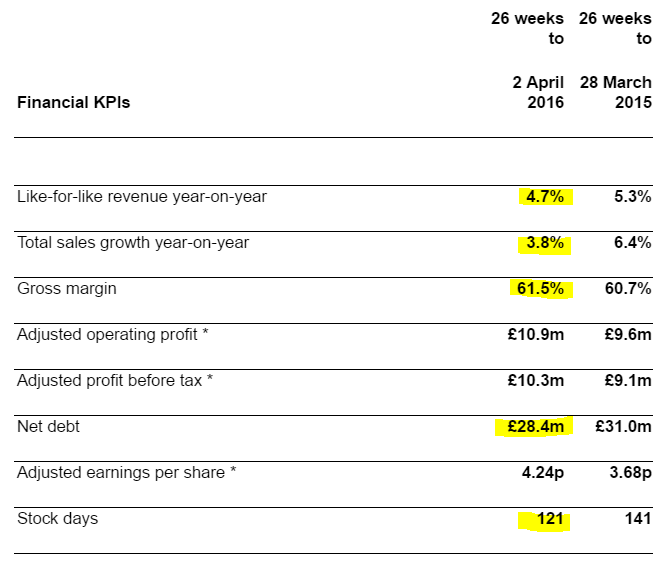
Note that total sales growth of 3.8% in H1 is actually lower than the LFL sales growth of 4.7%. This must mean that the number of stores actually declined. The narrative confirms this is due to the closure of their Topps Clearance format.
This looks to me like a company which is becoming mature. So it looks to have taken a bit of a breather from expanding the number of stores, and instead focussed on profitability. That makes a lot of sense, it's not a criticism.
Gross margin of 61.5% is outstanding. You can't really fail to make money with that kind of profit margin. Although it will of course attract competition.
Net debt of £28.4m isn't a problem, given the strong profitability, which should be in the £20m ballpark for the full year. The Naked Trader suggests a simple reasonableness check, that net debt shouldn't be more than 2-3 times profit. Something like that anyway. I think that's an excellent & very simple way to double-check that debt is not excessive.
I think you could tweak that idea, by looking at the volatility of historic profits, and thinking about how cyclical the company is. So you might tolerate more debt, if the company is not particularly cyclical, and has churned our reliable profits every year, even in recessions.
Also, I always offset freehold property against net debt, because banks are very relaxed about debt where they hold freeholds as security. Also, in the worst case scenario, freeholds can be sold to raise cash, in order to reduce bank debt. In this case, TPT says today:
The Group currently owns eight freehold or long leasehold sites (2015: eight), including one warehouse and distribution facility, with a total net book value of £16.3 million (2015: £16.6 million).
So that makes me even more relaxed about the £28.4m net debt.
Interest cost has reduced considerably on the P&L in H1, which is handy.
Dividends - the downside of companies with bank debt, is that the divis can sometimes be a bit constrained. That's certainly been the case with TPT in the past. The history is that it (rather foolishly) geared up to pay out massive dividends, just before the financial crash.
So debt reduction has been a key priority over the last few years. That has now been achieved to a large extent, so I imagine divis are likely to grow quite strongly now that the company has the financial flexibility to do so.
This year's forecast yield is about 2.6%, set to rise to 3.1% next year. It's good to identify shares where the divis are rising quite rapidly, in my view. This can often be a catalyst to drive the share price up, as income seekers spot the improving yield and buy the shares.
Stock days - has improved significantly, falling from 141 to 121. The lower this figure, then the faster the stock is turning. So 121 days means that the company has enough stock to feed sales for about 4 months. That's actually quite high still. However, that's probably because of the nature of the product - I imagine the lead times on ordering batches of tiles would be quite long. So the company would have to order, and stock lots of different ranges. The clever bit is if you can persuade suppliers to hold the stock for you, and only draw off what you want, and pay for it 30-60 days later, but suppliers hate doing that, for obvious reasons.
If retailers try to squeeze stock levels too low, then it harms the business because they don't have the right products in stock when needed to make a sale. So there's a balance to be had - having enough stock availability, but not tying up too much capital, especially with slow-moving lines.
Outlook - things seem to be humming along nicely so far in H2 too:
We have delivered a strong first half performance and are benefitting from a well-executed and consistent strategy supported by continued investments in our business to lay the foundations for future growth.
We have made an encouraging start to the second half with acceleration in like-for-like sales growth in the initial seven weeks. We are confident our plans to extend the appeal of the Topps brand have significant further potential and are excited about the opportunities ahead.
The LFL sales growth is given as +8.4% in the 7 weeks to 21 May 2016, which is excellent. Although footnote 5 indicates that this figure is flatted by about 1.1% due to the timing of Easter. Even so, adjusting that to +7.3%, it is still excellent.
Broker upgrades - I see that Liberum has this morning increased its forecast earnings for this full year by 3.4%. That's roughly what the shares are up today too, which makes sense.
My opinion - I really like it. This looks a well-managed, successful business.
The valuation is probably about right for now, as growth is only modest at the moment. However, I suspect there could be another move upwards in the shares once the store opening programme resumes in future. Although with existing 345 stores, I'm not sure how much scope there is for many more? I seem to recall reading somewhere that Topps think there is scope for a further 100 UK stores, but can't remember where I read that. Do any readers have any info on the scope for further store openings?
I can see quite good potential upside on this share in the medium to long term. So it gets a thumbs up from me.
accesso Technology (LON:ACSO)
Share price: 1212p (down 3.8% today)
No. shares: 22.2m
Market cap: £269.1m
AGM trading statement & board changes - there's a positive-sounding update today:
"I am pleased to report that the first part of this financial year has got off to a strong start, with pleasing organic growth across all divisions of our business. Moreover, eighteen new contract wins have been secured, and in total 51 new installations of our various solutions have been completed. Every part of our business has continued to show encouraging levels of customer engagement and opportunity. Taken together, these signs reflect continuing momentum across our Group, and show us to be executing well against the opportunity we pointed to at the time of our preliminary results in March.
More detail is given, which I will skip over, to get to the conclusion, which says:
...Whilst it is of course still early in the season with, as is normal, less than 20% of the year traded to date, the encouragingly strong start means we are increasingly confident about our likely performance for the year."
Of course, with the shares on arguably a sky-high rating, then performance has to remain good, in order to let the numbers catch up with the valuation.
The wobble in share price today is possibly due to disappointment that the dynamic CEO, Tom Burnet, is now becoming Executive Chairman. So still in charge, but with a less hands-on role:
The first of these changes will see Tom Burnet move from the role of Chief Executive Officer to become the Group's Executive Chairman. Having led accesso's significant growth and internationalisation since becoming CEO in 2010, Tom will continue in his new role to lead accesso's medium and long-term growth plans. He will have particular responsibility for Group strategy, Investor Relations, and M&A activity.
As a reminder, here is my audio interview with him, which covers a huge amount of ground about the business. I just let him talk, as it was helping me better understand the business.
My opinion - this is a fantastic business, dominating a niche globally. So I think in all likelihood it will probably be a much bigger business in a few years' time.
However, there's no doubt that the shares have had a terrific run. There is still considerable institutional demand too, I hear. However, everything has a price, and for me I also pay close attention to Director selling. Follow the money, as the saying goes.
Therefore, after big Director sales recently, to Institutions, my policy is to almost always follow Directors out of a share, regardless of what reasons are given. Therefore I'm currently out of this share, and watching from the sidelines, purely on valuation grounds - it looks a bit toppy for now, in my view.
There again, niche technology companies like this, with a big moat, can carry on going up & up, far higher than anyone believed possible. So it wouldn't surprise me at all to be kicking myself later at having sold too early. The trouble is, when you can't really justify a valuation on fundamentals any more, then it's really passing from investing into speculating, which makes me uneasy.
Porta Communications (LON:PTCM)
Share price: 5.75p (down 6.2% today)
No. shares: 279.1m
Market cap: £16.0m
Results y/e 31 Dec 2015 - I always complain about the way in which this company reports it numbers, and today is no exception.
The headline figures create the impression that this is a successful & profitable business:
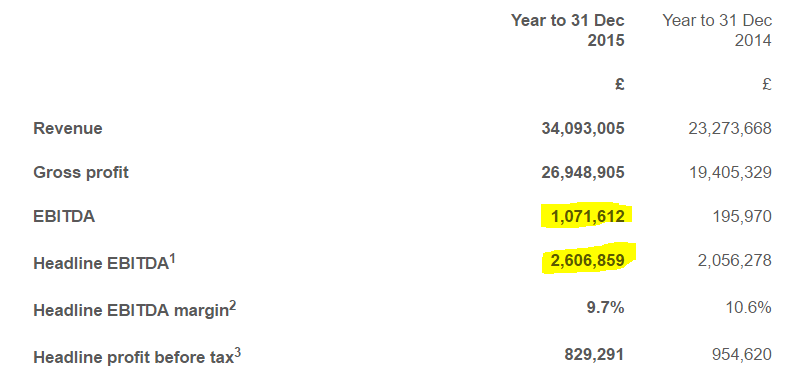
The trouble is, as I've been consistently saying for several years now, these figures are massaged so heavily as to give (in my view) a highly misleading impression.
When you look at all the adjustments below, then I think we can safely ignore "Headline EBITDA" as being fantasy:
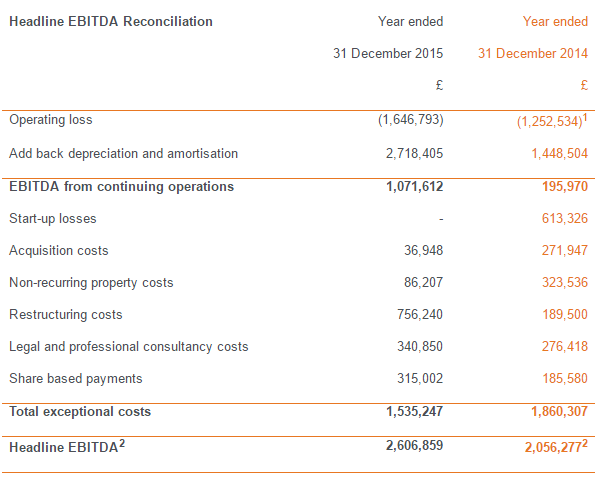
The £1,071k EBITDA figure is a bit more sensible. However, the elephant in the room are the enormous interest charges on the P&L, which cancels out all the EBITDA.
I had a half hour chat with management this morning, who pointed out that the interest charge rolls up, so the cash impact is less than the P&L charge. That's true, but of course compounding interest is creating a bigger problem in the future.
The intention is to seek cheaper financing as the group grows. So it's a bit chicken & egg - debt is needed to expand, but is expensive at the moment.
Debt arrangements - whilst this has been fully disclosed before, I am concerned at the related party loans from the Chairman, Bob Morton. He is living up to his reputation of being a shrewd investor, by loaning the company funds at 12% p.a. interest.
You could argue that this is a fair rate for a smaller company, which has been building up subsidiaries as start-ups. That's not an area where banks tend to want to get involved. However, it represents a big drain on Porta's P&L, and I think calls into question the value of the equity.
I would like to see the balance sheet strengthened with more equity. The danger is that might come on punitive terms, in a debt for equity swap at some point in the future.
Balance sheet - is weak. Net assets of £11.6m includes £17.1m intangibles, meaning that NTAV is -£5.5m. Not a disaster, but negative NTAV always makes me uncomfortable, especially at companies which are not properly profitable.
Value Creation Plan - I flagged up to management today, that many private investors hate this type of scheme. However, the company pointed out that, as a people business, such schemes are necessary to attract & retain the big fee earners.
With the hurdle set at 13p, that would be a (more than) doubling of the share price before the scheme pays out anything. I'm sure shareholders would be delighted with that. On the other hand, people who put money in at the 13p placing must be annoyed to see management potentially being rewarded for simply bringing the share price back up to where it started! I can see both points of view on this.
My opinion - my patience has run out today with this one, and I exited my long-term position this morning. The main reasons being;
- I've become increasingly uncomfortable with the expensive debt funding from the Chairman.
- Under-capitalised balance sheet
- I've consistently been critical of the way the accounts are presented.
On that last point, I'd much rather just see a reported loss, and understand that the company is experiencing growing pains, and that's that. Instead, the attempt every year to massage out positive performance by various definitions of EBITDA, is I think stretching credibility way too far.
On the plus side;
- The CEO has done it before - building up a highly successful and very valuable PR group
- There are some good businesses within Porta
- Once more established, the group might attract a bidder (the CEO mentioned 2x fee income as a multiple pertaining in the US for takeovers)
So I'll maintain a watching brief from now on. Hopefully the above is an even-handed review.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Paul - your comment (below) re ASCO 24th May is spot on!!
There again, niche technology companies like this, with a big moat, can carry on going up & up, far higher than anyone believed possible. So it wouldn't surprise me at all to be kicking myself later at having sold too early. The trouble is, when you can't really justify a valuation on fundamentals any more, then it's really passing from investing into speculating, which makes me uneasy.
Paul,
Re PTCM (A share i follow)
Been a pleasure reading your reviews on here. It was quite a balanced view on Porta.
My view.
Firstly not shocked to see a 1M buy trade show up at end of today. (Actually from yesterday.) Director or fund? Are directors still locked out here?? What did they say at briefing? Find out tomorrow? Be canny for a director to wait for all the sells and then buy in.
I think Management have used these results to dump all the bad financial news. Sure TTVM was bad and the European offices never quite worked out. Are they shaking the tree here for stock to buy?
Look at numbers here. 3.5-4M loss. Of which 2.7M was D and A. (Non cash.) 1.53M was exceptionals. Plus they talked about 1M cost savings for 2016 figures at previous AGM. To me this is a firm on the edge of being profitable, as long as they can reduce exceptional and D and A costs in future. They hopefully won't be closing divisions if all parts of business are now doing well. Note also the cash in the bank has barely changed since 2014. So lots of large figure but cash is very stable. Albeit the balance sheet very weak and they have 8m debt in loans.
If you compare these figures to the half year figures.
1st half: 1.53M loss. with 1.377 D and A and 548k exceptionals.
2nd half 1.9m loss with 1.34M D and A. 1M Exceptionals.
Add back in the apparent 1M savings for 2016.
So in the 1st half of 2016 I see opportunities for 0-300k profit if the costs and D and A fall away and savings are realised. We know the first 3 months are ahead of budget. Alas brexit looms.
The new acquisitions are all doing well and there has been a stream of new contracts. Glencore and Samonite extra business. Of course we don't know how many contracts they have lost. PR companies don't announce this
I am impressed by their Australian business. On a video yesterday David Wright talks about doubling the size of the Australian business. I can't believe this would just be on organic growth?? Did he mention how he intended to do this at the briefing?? Or news on any acquisitions?? 10-15% growth won't double a business size.
I agree with the debt worries and the weakness of the balance sheet. These new loans at 12% seem a bit OTT to me.Why they can't borrow money from a bank instead is a big mystery to me. Also other loans are due to be repaid at end of 2016. (I did read the explanation in your post above.)
I think a business is starting to shape up here. It is frustrating the way they have gone about things. Especially the results. I hope they do manage to start shaping a profitable busines here. I can understand why you have sold here and your frustrations.
I plan to hold this share for now as I think 5-6P undervalues a business turning over 34m. I do hope you will keep following this share. Were there many at the analyst presentation yesterday??
Small request - pls could people try to remember to put the Ticker or company name in every comment posted, so that people know which company you're talking about! That way other readers don't have to look back at previous comments, to try to work out what you're on about! ;-)
Many thanks, Paul.
Paul
I note that a non-exec at Tracsis has resigned with immediate effect. Could be due to any number of reasons.
With the sale of a % of shares by the CEO this year, and one of the largest holders selling down their stake are they having a few of those wobbles that business and life sometimes throw at you?
Hi Paul,
Looking back, I held Porta Communications (LON:PTCM) for most of 2014, buying at c.14p and selling for c.7p. At the time I rather feared I had done the typical (for me, anyway!) thing of selling out for a loss at the bottom, so it is strangely comforting to see that 18 months later that they sit at c.5.5p. Or is that simply schadenfreude?
I do get the feeling that PTCM will turn out to be another serial disappointer, promising great things but never quite delivering. I suspect we have all been in a few of them in our time. All part of investing in small-caps I suppose.
Good luck to holders. I hope it comes good.
Steve
ACSO is the dream share! I bought in at £3, sold out half at £7 and have been running the profit ever since. Your comments have made me question the wisdom of continuing run the profit, however it' such a great company that I struggle to bow out. Every time I have sold one of my big winners, it has gone higher!
Hi d40eq6,
accesso Technology (LON:ACSO) wasn't a continuous thing though. There was a game-changing announcement re Merlin on 30 Jul 2015, which I covered here - explaining the share had suddenly gone from being expensive, to being reasonably-priced, given the surge in growth.
So if the facts change, then we should change our mind! So I don't think it's right to say that the share at 300p was comparable to when it was 700p, for the sake of argument. I think it was actually better value at 700p than at 300p, because the facts had materially improved - massive contract wins.
As for when to sell? Nobody knows. It's just down to market sentiment really.
Regards, Paul.
Paul- quite agree with your points. I actually sold out half at £7 in November 2014- a good 7 months before the game-changer. The shares had drifted lower before that and I was considering chucking out the rest. It was your commentary in part that helped restore my confidence in the share and it has been well rewarded.
I suppose the old adage is that it is never wrong to take a profit....
Among the news today I'm not sure if many people opened the Boohoo.Com (LON:BOO) RNS this morning as it was entitled along the lines of 'Notice of AGM' but it looks like Boohoo.Com (LON:BOO) might be planning to use some of their excess cash to buy back shares.
paraic84,
FYI they had exactly the same resolution at the AGM last year (which got passed) if you rewind the clock 12 months and not a single share has been bought back to date, so this is not new news!
All the best, Si
Porta Communications, David Wright CEO, discussing FY results. Just a 3 minute clip.
http://www.piworld.co.uk/videos/2016/5/24/porta-communications-full-year-results-2015
Hi Paul - are you going to comment on RNWH's results ?
Thanks
Glaws
What do you think about the results?
I checked Paul's last review and he said "I won't go over all the detail again, but suffice it to say that (for me anyway) this share remains uninvestable, due to it having an extremely weak balance sheet."
Hi Glaws2,
Probably not. The trouble with Renew Holdings (LON:RNWH) is that I always say the same thing - P&L good, but awful balance sheet, needs to do an equity fundraising like Costain (LON:COST) did to repair its balance sheet.
So not much point in just repeating the same message.
Regards, Paul.
Is it really that bad (Renew's balance sheet)? From a quick reading of the interim results, current assets approx 111m, total liabilities (current + non-current) approx 172m. So about 61m total debt in my book, about 3x annual profit from H1 figure. I would have said not good, but not uninvestable. Am I missing something here?
Disclosure: I have no position in RNWH.
Now he's taking over as CEO he can strengthen the balance sheet...
Scm
Paul thanks for the Porta Communications (LON:PTCM), I used to hold glad I sold out, I quite agree about the presentation of the figures I never did like that. Yes has potential but will wait on the sidelines for now.
I like Topps Tiles, I used to have a load but sold them for reasons which escape me at the moment. They’ve open up a few boutiques near me on the mean streets of Knutsford and Wilmslow, Cheshire. Nice staff, decent tiles and it’s good to see they’re opening on the high street. I hate driving out to the arse-end of nowhere, to some scrubby industrial estate to do my home-improvements shopping. I’d much rather wander round Knutsford, get some nice lunch, have a mooch round Tatton Park – much more civilised than missioning to Trafford Park. Strangely, the Knutsford Topps Tiles Boutique is sandwiched between McLaren and Tesla dealerships. Maybe the high street isn’t dead after all? It’s just changing and evolving.
Thats interesting because its the opposite location near me, in fact the last 2 locations I have lived Topps have been tucked away on industrial estates. High street locations are expensive and maybe not so good for loading tiles which are heavy items. To be honest I prefer out of town locations, access and parking nearby is easier, its just less hassle. My concern is if there is any slow down in the housing market then Topps who are more mid to top end in tiles will get hit again, you only have to look back at the last recession.
£BON
Thanks.
Ex-cash p/e at current price and based on Morningstar forecast eps of around 5 looks too harsh
Sorry, but what are you referring to?
Hi Paul, Since it is a quiet day... what am I missing with Bonmarche (BON)? Enterprise value of £40 million or so, cash on balance sheet, does £9-10m net profit, great return on capital employed. There is a change of boss happening and the last announcement was cautious but still seems a weirdly low value to me, there surely must be something obvious I have missed. Any thoughts? Something to do with upcoming changes in accounting for leases maybe?
Thanks
Yes they look good value but the sector is down, even the better retailers have fallen quite markedly such as Next (LON:NXT) and Ted Baker (LON:TED), the future of high street retail is not looking rosy. The trading update did not help and it looks like a profit fall this year. One positive is the age group they sell to are less likely to do online shopping. I don't hold any Bonmarche Holdings (LON:BON) but I hold Next (LON:NXT) who have recovered slightly.
See the RNS announcements over the past six months - both Hargreave Hale and Miton appear to be selling down their holdings. HH still have approx 9%; the question is are both trying to get out completely, or just reduce their holdings?
At some point it will bottom out at what could be a very attractive valuation.
Ta
Chris
Hi Brackendale,
I don't have anything to add on Bonmarche Holdings (LON:BON) really. We're all in the dark. Clearly someone is selling, persistently, and there's a bit of a buyers' strike.
As someone else has said, with the retailing sector so out of favour, there are probably better bargains to be had with higher quality businesses such as Next (LON:NXT) (in which I have a holding). So when the best companies are cheap, the relatively weak ones (on measures such as operating margin) become even less attractive.
Add in profit warning(s), change of CEO, and a gap in newsflow, and BON seems to just dribble down a bit more each day.
I bought a tiny scrap more last week at 125p, but I don't have any conviction to buy more heavily.
BON is acting as if another profit warning is on the way, because if things were going well, then you would expect insiders to be buying. I mentioned a while back that Instis might want out, but with no buyers, what can they do? Just dribble out stock.
The divi yield appears to be over 5%, and twice covered, but is that sustainable? Who knows.
Overall, I'd rather work on facts, than guesswork, so for now I'm keeping my powder mostly dry on BON.
Regards, Paul.
Thanks to all of you for your insights, certainly makes a lot more sense as to why it has declined.
I am not sure why the institutions have taken such a negative (short term?) view on it, but that is probably why I don't earn big money in the City!
I own both TPT and ACSO
I sat on my hands when ACSO directors sold big time earlier this year- since then a 20% rise in the share price, even after the pull back today. I really rate this business - will continue to sit on my hands!! The fact they can predict a significant portion of their revenues out to 2024 is a huge plus
I bought tiles from Topps Tiles a few years ago - and was impressed by their quality of service and ability to deliver very quickly. I agree that this is a nice business and lets hope the dividends really start to motor