Small Cap Value Report (7 Apr 2017) - EPWN, MOTR, FDL

Good morning,
I'm planning to cover a few stocks from yesterday, since there is a lack of news today (ignoring the macroeconomic issues, of course!)
Regards
Graham
Epwin (LON:EPWN)
Share price: 106.4p (+2%)
No. shares: 142.5m
Market cap: £152m
A strong set of results from this manufacturer of building products (windows, doors, decking, etc):
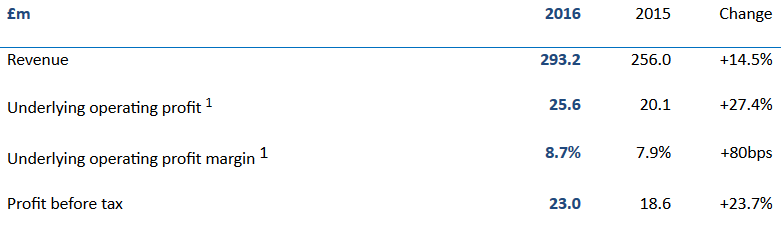
Final dividend is increased marginally to 4.4p.
Net debt also increases to £20.6 million.
Epwin has been pursuing growth by acquisition; all acquired companies are said to be performing well.
Outlook is a bit subdued:
"Whilst the long-term impact of the EU referendum result on consumer confidence remains unclear, trading in the current year has been in line with management's expectations. Input costs have increased sharply as a result of the weakening of sterling since June 2016. However, the Group is continuing its efforts to mitigate this and the Board remains confident in the long-term fundamentals of the Group and the markets it serves"
The overall vision seems to be continuously expanding/improving the product range and ending up with vastly more cross-selling opportunities and economies of scale as a result.
And the statement makes a few interesting arguments to the effect that people aren't repairing and maintaining their properties as much as they should, so that a backlog of necessary repair work is being built up. They would say that, wouldn't they!
Like-for-like revenues (excluding acquisitions) grew by just 2%.
My opinion
Seems difficult to get too excited about this. On the one hand, it would be much too harsh to describe this as a commodity business - there is substantial expertise required in the manufacture of many of these products.
On the other hand, the company's admitted vulnerability to exchange rate movements, and the lack of like-for-like growth which is also due to factors beyond its control, leave me with some doubts about its underlying quality.
Regular readers will be aware that acquisition-led growth is something I instinctively shy away from.
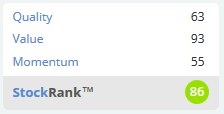
Apparently I'm not the only one suffering from a bit of scepticism toward this share, as the PE ratio is undoubtedly very cheap versus the market as a whole, at less than 8x.
Stockopedia agrees that it's in the bargain bucket:
Motorpoint (LON:MOTR)
Share price: 150.75p (+3%)
No. shares: 100m
Market cap: £151m
This gave the magic words "in line with expectations" in the sub-heading, so investors immediately knew not to panic (indeed, they pushed the shares markedly higher from the 140p prior close).
Turnover for the year of approximately £820m, an increase of 12.5% on FY16
The Board expects the Group's Profit Before Tax for FY17 to be at the upper end of the range of current market expectations, reflecting the improving trading performance in the second half (see note 1).
Scrolling down to Note 1, I see that this range for adjusted PBT is considered to be £14.6 million to £15.5 million.
When Paul covered Motorpoint's profit warning last October, he noted that their PBT broker forecasts were reduced from £21 million to £16.7 million at one particular broker, at that time. Things may have deteriorated a bit further after that, so that the final result will be around £15.5 million.
They key promise last October was that net margin would recover in H2, and that appears to have occurred in Q4:
The final quarter of the Group's financial year in particular has seen increased customer footfall and online traffic, driving improved volume performance both in like-for-like sales and sales at new sites.
Outlook
Safe to say that this is a bit cagey?
The Board is cautiously optimistic regarding the UK used vehicle market and remains confident that Motorpoint's independent and flexible model ensures the Group is well placed to continue to grow market share.
My opinion
I like the concept of focusing on the "nearly new" car segment, and I note that the service has an excellent (9/10) rating on trustpilot, where it has well over 300 reviews. Most reviews highly praise the staff, describing the service as a no-pressure sales environment, which must be a welcome relief from the typical second hand car dealership!
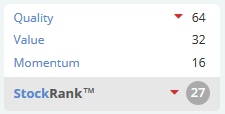
The Stockopedia rankings aren't too keen on it, particularly in terms of Value and Momentum, though for what it's worth the forecast PE rating is less than 10x and perhaps Momentum is set to improve now that the shares have bounced after this latest update?
I'd put this on the watchlist.
Findel (LON:FDL)
Share price: 200.4p (-0.3%)
No. shares: 86.4m
Market cap: £173m
and
Phil Maudsley Appointed Chief Executive
A double-barrelled update yesterday, including the announcement of an internal hire for the position of CEO, who replaces the Chairman in the executive role.
The new CEO was previously MD of Findel's "Express Gifts", its direct-to-consumer online retailing division, and appears an obvious choice for the role..
Separately, the long-serving Group Finance Director has "stood down" (no further details given), and the search for his successor is about to begin.
The position of FD is a sensitive one and I think investors like to know the circumstances surrounding the departure of an individual from this position. For Findel specifically, it very recently announced that it needed to increase provisioning for customer refunds in relation to flawed insurance products from £18 million to £29 million. Perhaps one could be forgiven for supposing that there might be a link between these events?
Getting back to the trading update, things are a bit mixed:
The Group has seen strong sales growth and anticipates total like-for-like* sales growth for the full year to be around 10%. As highlighted in January's trading statement the rate of sales growth accelerated in the second half of the year.
Pre-exceptional PBT is a slight miss:
Overall, the Group expects to report a profit before tax and exceptional items slightly below the bottom of the range of consensus **. Core net debt is expected to end the year at c. £80m, an improvement of around £5m on the prior year and slightly better than market expectations.
Again checking the footnotes, the lower bound of the range for PBT over the 53-week period is £25.5 million. So something a bit worse than that is in store.
Express Gifts is said to have done well in terms of revenues and customer recruitment, but sacrificed margin due to a sales drive in imported USD-priced product.
Things are less rosy in the Findel Education Division. LFL sales are down c. 4%.
Outlook
Sounds upbeat to me:
The significant increase in the Express Gifts customer base and the continued investment in customer recruitment activity form an encouraging base to take into the new financial year. We remain watchful of pricing conditions as a result of foreign exchange movements from the perspective of Express Gifts, but look forward to delivering growth in the coming year.
My opinion
There's quite a lot for an analyst to unpack at Findel, but it's the sort of business I might be interested to buy at the right price.
Something I don't really understand is why shareholders have reacted in such a calm way to the recent flurry of announcements.
Given the recent increase, there must remain an element of uncertainty around the provision needed for historic mis-sold insurance. Also, the loss of an FD would ordinarily result in some selling pressure. And the company is set to miss its earnings forecasts. But the share price is slightly higher now than it was before all of this was announced!
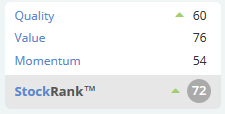
I guess it is not too highly rated at the current level. Expectation must already be fairly low.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Epwin seem to be doing well in spite of the issues raised.
safestyle will probably end up buying epwin whilst epwin trades at this price !
Regarding Epwin and Safestyle the latter seem to sell to private customers rather than to builders so I see this as a safer bet. It was not until around 12 years after we had double glazing installed that I realised that it lasts just long enough to avoid a claim under the 10 year guarantee but not long enough to start to need some replacements soon thereafter (my windows were not from Safestyle but I suspect they are all the same). If a window mists up then people get it replaced so the customers provide a sort of ongoing annuity of income to the industry.
Not sure it is all the same, my last house never had any problems with misting even after 30 years yet other makes seem to be prone to it. Safestyle make their own I believe, not sure that includes the actual sealed units of glass or not. The problem with Safestyle is their selling tactics, don't ever let them get your number or if you do give them it make sure it's one you can easily change. If you need the units replaced you can get that done fairly cheaper, I know because my builder damaged one and got it replaced I thought it would be about £200 but he said it was only £25. All these companies charge high prices because of marketing, advertising and high commission to salesmen, check the car the sales rep drives.
They certainly manufacture the double glazing units. Their last report refers to a new glass toughening furnace. Reviews on Feefo seem quite good on average with 4.4 out of 5.0 for over 700 reviews. I was in early on and it has been a good investment.
Sold my Epwin due to the importance of its relationship with Entu. I was concerned that Entu doesn't look that strong,and that at some point in the future the terms of that relationship might need to be revised in Entu's favour to the detriment of Epwin.
I also own Epwin (LON:EPWN), because of its high cash flow yield, high divs and low P/E. I agree that the link with ENTU is a cause for concern and would justify a lower multiple but the question is how big? I have taken some comfort that Entu has recently managed to produce a set of final numbers (admitedly 5 months after the end of its financial year) with a going concern statement. Also the exclusive supply agreement with ENtu runs to mid-2019.
Panmure Gordon has pointed out Epwin's large discount to Polypipe, Safestyle and Volution. Epwin has tended to trade on a similar low rating to Eurocell (which similarly sells into the PMI and social housing markets). But I note the recent strong rise in Eurocell stock, for which I do not understand the catalyst.
Re Motorpoint. I am very cautious about car dealers in general. The business model for them is that little margin exists on new vehicles but the money is made on second hand sales and on servicing. However there are going to be a large number of 2 and 3 year old cars starting to hit the forecourts as a result of the very successful personal leasing of new cars in recent years. I believe that this will squeeze margins on second hand cars across the market. So small margins on second hand joins small margins on new
I cannot really see Motorpoint being able to avoid this. Maybe they are better placed than some ?
I recently rather foolishly volunteered to buy my daughters next car on her behalf. I could barely bring myself to deal with the nearly-new car salesman, so irritating did I find his attempts to upsell me financing, warranties, insurance products, fancy polishing treatments etc etc.
They claim to make little margin on "the metal". That's just the lead for all the add-ons.
If I could have found an equivalent car for sale privately I would have driven a long way to buy it. But the dealers seem to have the market sown up because everyone buys on finance nowadays.
If Motorpoint are as good as their reviews they could do well.
Re Epwin (LON:EPWN) Companies in the property RMI (Repair, Maintenance and Improvement) sector such as Epwin are in a difficult situation,
The economic outlook is inflation, higher import costs due to sterling depreciation, squeeze on consumer spending. The low rating of this company is a reflection of this scenario post the Brexit decision.
Personally I am staying away from companies that rely on consumer spending, discretionary or otherwise, for the foreseeable future.
Epwin (LON:EPWN) is a play on the housing market without the upside of the house builders that is why it always has a low p/e. If the housing market/economy collapses it wont just be Epwin's gutters that will be up against a brick wall.
In addition to the builders destocking the last thing a homeowner will replace in a recession are the gutters (unless they are leaking over the porch) or the double glazing.
Edit- Just spotted for those in Epwin that IC gave a positive tip for yesterday but then IC rarely looks beyond the figures which are good but I think the wrong time of the economic cycle for brick manufacturers and double glazing.
Don't know why you would buy Epwin instead of Safestyle.
But then I don't have either.
Hi steviej,
If of any interest, the reason why I bought Epwin (in addition to Safestyle) was in part because of its strong competitive position in a market in which it is a major player, if not the major player in the UK. This is confirmed by the fact that there was a Competition Commission enquiry into its merger with Latium in 2012 and its decent ROCE figures also suggest a satisfactory competitive position. Since 2012 Epwin has continued to make a range of acquisitions to strenthen its competitive position still further. I also like the fact that Epwin has a better balance between trade sales and retail than does Safestyle. I think Epwin is a company that some love to hate and I don't generally invest in cyclicals but I must admit I have made an exception with Epwin for the reasons explained above.
Dear Graham,
I own shares in Epwin (LON:EPWN). You wrote:
I would add that net debt was reported as £29.9m at the half-year stage:
http://www.stockopedia.com/share-prices/epwin-LON:...
Regards,
Asagi (long EPWN)
Thanks for that Asagi,
Good luck
Graham