Small Cap Value Report (8 Nov 2016) - FEVR, RCN, KWS, ACRL, PUB

Good morning!
I really enjoyed the discussion in the comments section of yesterday's report, so thank you to everyone who contributed. I suppose there was a certain irony in me bemoaning the post-fact nature of a lot of popular discussion. Only to illustrate my point with something (Brexit polls) where my own recollection wasn't entirely accurate!
Still, that did illustrate the proper process - someone points out that you may not be entirely accurate in what you're saying. You check the evidence they provide. If they're right, then you revise your opinion in light of the fresh information provided. That's how things should work, but sadly often does not - especially on social media - because ego and stubbornness get in the way.
I am becoming increasingly convinced that the world was a much better place before social media was invented. Hopefully there will be a backlash against Facebook in due course. Mind you, it is very good at catching criminals & fraudsters apparently. I've just been watching a TV programme about how insurance fraudsters, and other bad people often give themselves away through their social media postings.
Fevertree Drinks (LON:FEVR)
Share price: 1100p
No. shares: 115.2m
Market cap: £1,267.2m
Trading update - not a small cap any more, but it's topical & interesting, so I have some comments. This maker of premium fizzy drinks is worth a mention, as it nicely illustrates the point of how "expensive" shares can keep going up to seemingly stratospheric levels.
The key here is repeated improvements to expected performance. The latest update, out yesterday said;
The Board is pleased to announce that Fever-Tree has continued to perform strongly in the second half of the year.
The performance in the UK, the Group's largest market, has been particularly strong as new distribution gains have combined with a continued rate of sales growth.
Given the strong sales in the period to date, the Board anticipates that the results for the full year ending 31 December 2016 will be materially ahead of current market expectations.
That's pretty remarkable stuff - at this late point in the year, I wouldn't normally expect any "materially ahead" statements - as most companies will probably know how this year is likely to play out. That's for companies with a 31 Dec year end, of course. So Fevertree must really be trading their socks off.
If you look at the Stockopedia graphic for broker consensus forecast, it's striking how the company has been upgraded multiple times earlier this year;
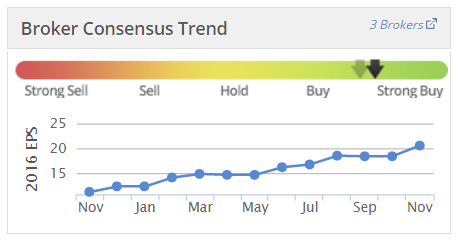
I'm pretty sure the growth here is all organic growth too, but please correct me on that point if it's not.
What's interesting, is that if you look back to a year ago, the share price was 530p, and broker consensus forecast was EPS of 11.3p. So most people (including myself) looked at it, and thought that the forward PER of 46.9 was very expensive, and declined to buy the shares.
However, roll forward a year, and it now transpires that 2016 EPS will be something like 23-25p - more than double the original forecasts. Therefore a year ago, the PER was actually 22 - fairly reasonable (based on my estimate of 24p EPS for this year - the midpoint of the range in the previous sentence).
This illustrates the point how exceptional growth companies can appear expensive, but because they're going to strongly out-perform forecasts, they were not actually expensive at all. The trouble is that truly exceptional growth companies are so few & far between in the London market. So if you latch onto the wrong one, it can be an expensive mistake, if the growth doesn't pan out as hoped for.
This area is a key focus of mine these days - I try to find growth companies where the broker forecasts look way, way too cautious. A good example of this recently was Gear4Music (G4M), where I backed up the truck and bought as many as I could at about 180p. This was due to me doing some number crunching, to revise the broker forecasts, and realising that they were considerably under-estimating likely revenue & profit for this year & next year. When the market realised this too, over the following few weeks, the share price doubled. I don't think we're up with events by a long shot yet, either. However, the next catalyst is not likely to be until the January trading update.
We're in a market that is highly receptive to growth stocks, so they're generally expensive at the moment. I didn't spot the potential at FeverTree unfortunately - it seemed ridiculous that people would over-pay for tonic water, which to me, doesn't taste any different to the normal stuff. Although opinions differ on that. Above all, it's a triumph of marketing, branding, and spotting a brilliant opportunity to create a new niche of premium mixers. Complacent established competition too, helped. So hats off to FeverTree's founders for pulling off such a remarkable coup.
Lessons learned re growth companies
So I suppose the things I've learned from FeverTree (and other growth stocks are);
1) Don't take broker forecasts as gospel. They're often far too pessimistic at exceptionally good growth companies. So that apparently expensive PER may not necessarily turn out to be expensive after all.
2) It usually won't be obvious that a company is likely to thrash broker forecasts - you have to really understand the business model, and I think probably meet management too, to understand the potential. So deeper research is needed for growth companies, to spot something exceptional that the market may have missed. It also requires real conviction to continue holding an "expensive" share.
3) Filtering databases to find stocks probably won't find exceptional growth stocks like this. They'll just look far too expensive on a forward PER basis, and therefore will probably be rejected. Yet actually the forecasts could turn out to be wrong, and that's where the opportunity lies.
4) I'm going to pay more attention to the Stockopedia momentum ranking - as that picks up broker upgrades, which are the early indications that things are going better than expected.
5) Lots of investors I chat to don't buy stocks which have risen a lot, because they feel they've "missed the boat". I'm very much guilty of this myself too. This needs more thought - shares that have risen a lot, have usually done so for a good reason (excluding silly speculative rubbish). So a strongly rising share price is a call to investigate further, and see what we're missing, rather than something to necessarily fight against or ignore.
6) I've noticed how growth companies in the UK can look expensive for a while, but the rating then goes into the stratosphere once strong overseas growth begins to happen. This certainly drove the really big gains in £ASC shares, and a similar thing happened at Boohoo.Com (LON:BOO) more recently. It's also helped drive Fevertree Drinks (LON:FEVR) up considerably. Once investors see strong international growth starting to kick in, they will often massively re-rate an already highly rated share. I think this is in the process of happening at Gear4Music (G4M) as well - it achieved +169% sales growth in mainland Europe in H1, and I don't think the market has fully priced that in yet.
7) In a bear market, most of the above goes out of the window. So I think it's important to remember that growth stocks usually only attract racy ratings in bull markets. They can collapse in price in a bear market, especially if sales & earnings begin to disappoint. A PER of 50 could turn into a PER of 15 in a bear market, which combined with lower earnings forecasts could easily mean investors losing most of their money. So knowing when to sell is crucial with growth stocks.
The above is just me thinking out loud, by the way, as I'm guilty of making a lot of mistakes, same as everyone else.
Redcentric (LON:RCN) - in yesterday's report, I tried to unravel what on earth has been going on with the misstated accounts at Redcentric. I should emphasise that we've not been told the full details yet of what's gone wrong at the company. So I'm awaiting more full information, and my gut feel suggests that more dirt could come out of the woodwork.
That said, the share price sell-off does look overdone, based on what we've been told so far.
There's been no further news from the company yet, apart from a couple of quite interesting TR1 forms out today. However, I want to flag up an interesting post by Mark Bentley on the ShareSoc blog. Mark highlights the issue of significant gains made by the CEO recently from cashing in share options, on the back of what we now know to be false accounts.
Clearly that's completely unacceptable, and any gains made by Directors from false accounts should be forfeited, in my view. Disgruntled shareholders may want to congregate around ShareSoc, so that a united voice can be put together.
Keywords Studios (LON:KWS)
Share price: 475p (up 3.3% today)
No. shares: 54.4m
Market cap: £258.4m
Trading update - from yesterday, this announcement has been mentioned by readers, so thought I'd better take a look at it.
The company describes itself like this;
Keywords Studios, the international technical services provider to the global video games industry
It's AIM listed, and seems to be based in Dublin.
A positive update yesterday;
...pleased to announce that it now anticipates that revenues and adjusted PBT* for the full year to 31 December 2016 will be significantly ahead of current market expectations...
As a consequence, the Board expects adjusted PBT for the current year to be not less than €14m.
Note that it reports in Euros. It's good to see the company quantify profit expectations.
FinnCap says that this compares with consensus of E12.5m, so a useful beat.
Out-performance has mainly come from one recently acquired business;
This outperformance has been driven primarily by recently acquired localisation and audio business, Synthesis, sustaining higher levels of activity during the second half of the financial year than previously anticipated after a particularly strong second quarter which benefitted from a number of large projects alongside its normal flow of activity.
My opinion - it looks expensive, and growth seems to be coming in large part from acquisitions. On the plus side, it's great to hear that the group is trading well ahead of forecasts.
I wouldn't know where to start in analysing this sector, so I'll pass on this share. A potentially interesting company to research though, if you understand its activities & sector.
Accrol Group (LON:ACRL)
Share price: 126p
No. shares: 93.0m
Market cap: £117.2m
Admission document - I've been meaning to look at this company for a few months, and have finally got round to it this evening.
Accrol is a toilet roll, kitchen roll, and similar manufacturer, based in Blackburn. It was floated on AIM in Jun 2016 by Zeus Capital, at 100p. They got the IPO away just in the nick of time, as just a fortnight after the company floated, the UK voted for Brexit.
Consider this risk factor in Accrol's admission document;
Brexit
If Britain were to leave the European Union, it could have a direct impact on the Group due to unfavourable movements in exchange rates, particularly the British Pound which could weaken significantly against overseas currencies, including the US Dollar and Euro.
The Group purchases the majority of Parent Reels in foreign currencies, with significant purchases in US Dollars and Euros. Should exchange rates move in an unfavourable manner as a result of Britain leaving the European Union, the Group’s raw material costs will increase and this could have a material adverse impact on the Group’s business, financial condition and results of operation.
The Directors and Proposed Directors have identified a number of mitigating actions that could reduce this exposure including switching suppliers, making payment in British Pounds or other currencies, acquiring more Parent Reels from UK suppliers, re-balancing operations or passing price increases on to customers.
The Directors and Proposed Directors also believe that adverse movement in exchange rates may be offset by a beneficial movement in paper prices. Should Britain leave the European Union, there may be other, unforeseen, effects both impacting the Group directly and the market in which it operates and the mitigating actions identified may not always be effective. [see page 38 of admission document]
Well, a big adverse movement in exchange rates is exactly what has happened. So I wonder how this has actually impacted Accrol?
There are a number of other risk factors which concern me. Especially the disclosure of heavy concentration with major customers. The biggest single customer is responsible for 25% of Accrol's turnover. There are several other customers around the 10% level each. That's a big risk - I reckon if the top customer pulled out, it would possibly wipe out most, or maybe all, this company's profits at a stroke.
Also, note that the company believes that "parent rolls" (which are used to make toilet rolls) are advantageously priced. This may not continue;
Parent Reel price volatility
The Group considers that, due to an oversupply of Parent Reels and pulp at present, Parent Reel prices are currently comparatively low.
However, if Parent Reel prices were to rise above the Group’s expectations and the Group was unable to offset such increases through cost savings or price increases, that could have a material adverse effect on the Group’s business, financial condition and results of operations.
This is important, because when reading an admission document, I'm looking for the reasons as why the vendors (who know the company & sector much better than I do, after all) want to cash in most of their chips? I'm very suspicious of all new issues. A lot go wrong within 2 years.
The IPO at 100p was a disposal of 20.15m shares by the founding family, and a PE company which supported its growth in 2014. Plus a further 43.3m new shares - however these proceeds were used to pay off existing shareholder loans. So this float was more-or-less entirely existing shareholders cashing in their chips. They do however still retain 15% (the founding Hussain family), and NorthEdge Capital retained 15%.
MIP scheme - section 4 of the admission document details a horrible management incentive scheme, called MIP. This gives management 12% of the upside in share price above 130p (30% above the IPO price). So when you're pricing this share, bear in mind that anything above130p is only 88% yours. The rest will be nabbed by management. Dreadful.
Planned 6% dividend yield - Zeus has used this method several times, to get new issues away. They promise a generous yield, but as we saw with Entu (UK) (LON:ENTU) the enticing yield can be a mirage. If performance falls away, then the divis will be curtailed or disappear altogether.
So a fair bit in the admission document that I don't like. Let's look at latest update.
Trading update - this covers the 6 months to 31 Oct 2016, so it's for H1. The company has a 30 April year end.
This sounds alright;
The business has made good progress since the start of this financial year and trading has been in line with our expectations.
During the six months ended 31 October 2016, the Company has continued to win new business with existing customers in addition to the previously announced new £10m contract gain, which we can now confirm is Lidl.
That's a good point about the discount supermarkets - they are Accrol's main customers, which supports its assertions to be very competitive on price. Bearing in mind that Aldi, Lidl, etc, are winning market share in the UK, then that should augur well for further sales growth for Accrol. It's always good to have major customers which are expanding, for obvious reasons.
More production capacity is coming online, to support higher customer orders.
Forex hedging - this is important, as it will have absorbed the impact of sterling devaluation (for now);
We continue to follow our hedging policy to mitigate adverse movements in Sterling against the US$ and Euro. Following our significant purchase of dollars pre-Brexit, we have increased our facilities and we continue to closely monitor the Company's forward currency positions.
Hedging only defers an adverse P&L impact, it doesn't eliminate it. So I think we need to know when the hedges expire, and higher raw material prices begin to hit profits?
Outlook comments for the current year sound encouraging, including this;
We remain confident in the outlook for the full year and that the strong cash flows generated by the business will support our progressive dividend policy and underpin our continued growth.
So that sounds as if the divis are safe for now.
My opinion - the key issue for this company seems to be when higher input prices will feed through, and what ability the company has to pass on higher prices to its customers? Are customer contracts flexible in this regard, or fixed price?
Overall, I think this looks quite a good company, but on balance there are various items in the admission document (mentioned above) which make me too nervous to want to buy any shares in this company.
A few quick comments, before the first exit polls come out in the US election.
Punch Taverns (LON:PUB) - preliminary results 52 weeks to 20 Aug 2016.
The figures are too complicated for me to go into right now. However, I've added a few to my Stockopedia fantasy portfolio, but have not bought any personally yet.
The potential upside with Punch relates to the possibility of it refinancing its large debt mountain onto more favourable terms. At the moment it is paying high interest rates on a range of bonds & other borrowings. So roughly two thirds of its £168.1m operating profit was consumed in interest payments. Over time, that should reduce, and it could get into a virtuous circle of improving free cashflow, and thereby enabling more of the expensive debt to be repaid or refinanced onto lower interest rates.
Bear in mind that the freehold portfolio is worth considerably more than debt, so it's not a basket case by any means. Although bears might say that the freeholds could be worth a lot less then they're in the books for, in a fire sale.
I did have a detailed go through all the numbers earlier in 2016, but need to refresh my memory when time permits. So it's going onto the watch list.
Think I'll leave it there. See you in the morning!
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Hi FREng
I will have a go at answering your question, since Paul has plenty of work to do round here, and I generally take a free ride.
You wrote:
Could you explain why you sold Avesco (LON:AVS) on 4 October, just days after a positive SCVR write up that said "I'm hoping for upside to 400-500p here, in the long run, and it remains one of my core personal holdings." ?
That sounds somewhat accusatory to me too. Especially because Paul has been accused of various things over the years and is actually as honest a man as ever went near the stock market.
How about: "It would be useful for me to know the rationale behind sales of stocks, like Avesco for instance, where you have set out a positive case for further upside."
ATB
Jon
Your piece on Accrol is gold dust to the less experienced. IPOs are attractive and can be an opportunity for susbstantial gains, from which I have benefitted over the years. To be alerted to the, let's be kind, strategies "cashing in chips", MIP schemes all adds to gauging the worth of a float. Who knows it might be a great stock. It seems to make absolute sense to produce voluminous low value products close to the consumer rather than shipping fresh air all the way from a low cost Asian producer, which would have hooked me, now I will think again, so might those seeking to catch unsuspecting investors. We have been warned.
Hi catalogue,
Thanks for your comments.
I'm not saying whether Accrol Group (LON:ACRL) is necessarily good or bad.
I just see my job as being to rummage through the admission document & RNSs, and report back to you. Then you can make up your own mind.
Also, secretly, I quite like reading admission documents! Which makes me very sad LOL!!!!
Regards, Paul. :-D
Hi paul,
I think there is one significant fundamental you have missed in your report of Accrol. That is the large purchase of shares by the ceo of the company on the 29th of September. He bought £132,000 worth of shares at a price of 132p a share. A significant amount as he did not hold any prior to this.
Paul can you looks at sbry today as revenue is 12.6bn v 12.4bn in 2015. Point being this year revenue includes argos sales of 1.4bn ish. So whats going on?
Paul
Thanks for the link to your fantasy portfolio, Beam Me Up Scotty. Very interesting - and very successful!
Could you explain why you sold Avesco (LON:AVS) on 4 October, just days after a positive SCVR write up that said "I'm hoping for upside to 400-500p here, in the long run, and it remains one of my core personal holdings." ?
Hi FREng,
You asked;
Could you explain why you sold Avesco (LON:AVS) on 4 October, just days after a positive SCVR write up that said "I'm hoping for upside to 400-500p here, in the long run, and it remains one of my core personal holdings." ?
Sure. The reason is simple. I DIDN'T sell AVS. I top-sliced it, as I almost always do with successful positions, to rebalance the position size in my portfolio.
Top-slicing has been my policy for many years - as readers here will know.
The facts are that in my fantasy portfolio I originally bought AVS at 125p, and AFTER recent top slice am up 131% on the balance.
It remains one of my largest holdings, at 174k/1846k = 9.4% in the fantasy portfolio, exactly in line with my commentary in the SCVRs.
Hope that clarifies.
I look forward to your overdue apology.
To be blunt, if you're going to be a PITA and make unfounded implications of wrongdoing, etc, then I won't bother to carry on with the fantasy portfolio. I didn't want to do it in the first place, and rarely remember to update it.
Ed coaxed me into doing it, as he said in early 2015 that he's a data guy, and wants proof that my approach works. So I reluctantly agreed.
It's had a very good run recently, and that may not continue. As with everything I do, if it becomes a chore, and if people get nasty over it, then it goes in the dustbin. I'm perfectly happy to have a quiet life, and not spend every day trying to help people interpret RNSs and results statements.
Paul
Paul,
It was a sincere thanks for the link to the fantasy portfolio (which I hadn't found before) and a sincere (and, I thought, polite) request for some insight into what motivated your well-timed (partial) sale. I certainly had no intention of causing offence and I apologise, grovellingly, for inadvertently doing so.
To help me in future, could you say whether you really don't want questions explain how I could have phrased this question so that it didn't cause offence?
The Trump effect.
I looked through the top fallers today (there's no major impact of the Trump win yet, it seems) and came across Alumasc (LON:ALU) which has fallen 5% or so today. It looks interesting - does anyone here have any knowledge of ALU?
Alumasc (LON:ALU) shows excellent figures, but has a massive pension defecit. (PER 8.4; PEG 0.6; Yield 3.5%). The company recently shed some less profitable subsidiaries, and the last update was pretty positive. I hold and am happy to do so. The 24-Hour Charty People can see this falling to 127. If it does I would like some more. (Today's move is on small volume, as are most shifts here).
Thanks - I hadn't spotted the pension deficit.
Paul, FEVR generates almost £300,000 profit per employee, that's remarkable and explains how niche it is.
BVXP comes close to it and I hold both
Hi Modform,
Yes, fair point (post #22).
Although I think what matters more, is how sustainable profitability is?
So the big question with Fevertree Drinks (LON:FEVR) is whether it's built a permanent place in the tonic water market, or whether the goliath incumbents may try to snuff it out with competing products?
To my mind, it's just too faddish to justify taking a punt on.
Regards, Paul.
Hi Paul
I dont think that the goliath incumbents will be able to snuff it out in the same way that VW would not be able to snuff out say Ferrari by building a car that costs £250k and goes from 0 to 60 in 3 seconds.
Enough of the population like premium products (I'll have a gin and Fevertree please!) that there is room for Fevertree Drinks (LON:FEVR) AND Schweppes. I would have thought that with such a small turnover (£90m) there is room for expansion without making any real dent in the big boys sales/profits.
I still have high hopes for this stock and will certainly top up on either pull back and/or when the dust settles over the US election.
Thanks for the link to the Fantasy portfolio BTW
For Paul and others wondering what Keywords Studios (LON:KWS) does, this video of their presentation at ShareSoc in Richmond in July is what led me to start buying their shares.
http://www.piworld.co.uk/company-video-2016/2016/7/15/keywords-studios-kws-sharesoc-richmond-july-2016
Paul
You omitted to say whether you think FeverTree is a buy/sell/hold at this price.
Hi GBGMC0,
I don't give Buy/Hold/Sell ratings or advice. I just don't agree with the whole principle of commentators telling readers what to do with their own money, that seems completely wrong to me.
The onus here is for everyone to do their own research, and make up their own minds.
Regards, Paul.
Paul
What I mean is usually you give a My Opinion section where you say if it's expensive or not. You have omitted this with your FeverTree analysis, but have included it with your other reviews.
Hi GMGMC0,
Ah I see!
What I mean is usually you give a My Opinion section where you say if it's expensive or not. You have omitted this with your FeverTree analysis, but have included it with your other reviews.
Fevertree Drinks (LON:FEVR) market cap is well over £1bn, so I only mentioned it the other day as a topical share to illustrate an interesting point - how growth companies grow into the valuation, and what we can learn from that.
I don't have any particularly strong views on FEVR - although it is noticeable how growth investors who saw the potential have made money, whilst those of us who focused on value measures, got it wrong (so far, anyway). That was the main thrust of the article.
Regards, Paul.
I can't really add much with regard to Fevertree Drinks (LON:FEVR) but I have ridden the stick up with an initial purchase in Oct 15 and then purchases in Nov, Jan, March and July. It was not based on much analysis:
- I liked the product. I really do think the low cal tonic is far superior than say Schweppes
- growth potential there was a stat mentioned that Fevertree Drinks (LON:FEVR) was in 7,000 bars and Bombay Saphire in 37,000 in the uk
- great ROA, ROCE etc
I personally think with turnover in the £80m to £100m range there is still room for growth. It is 11.8% of my ex cash folio and I am still tempted to top up.
My only fear is that they will be taken over and all the real value will accrue to Schweppes or A N Other.
Paul,
Trifast (LON:TRI) has issued H1 results today which look good and have been bolstered by exchange rate gains. The EPS broker forecasts for the "year after next" (FY18 in this case) has been modest and looking back Trifast has beaten them when the year comes round. Another underrated growth share at a modest PE I think? Ian
Yes, Trifast (LON:TRI) looks very good and Brexit-proof because of several overseas sites. One to buy if there's a sharp fall after the US election result.
I like Trifast and have been a satisfied holder for a while as they have piled up year on year of good results. But I think that it is dangerous to think of a p/e of 16.5 as "modest"
We are in a period of record car sales ( to which i believe it has some correlation), it is a manufacturer in a lower level of technology, fasteners (nuts and bolts to you and I), is changing its long time CEO, has a 8.6%operating margin and a 40% gearing. I mean what could go wrong?
As I said, I am an admirer and a holder of the stock, but I think a 16.5 p/e is quite exciting enough
Aislabie,
Trifast (LON:TRI) is at a modest PER compared to FEVR and BOO and before today's H1 results the average broker EPS forecast was +22% EPS in 2017 and +3.6% in 2018. With only part of H1 inc the exchange rate effect the EPS gain was +24%. TRI should have a favorable Britexit export exchange rate tailwind because 70% of their sales are outside the UK. The +3.6% 2018 EPS broker forecast increase was/is ridiculously low and mirrors Paul's 1st point:
1) Don't take broker forecasts as gospel. They're often far too pessimistic at exceptionally good growth companies. So that apparently expensive PER may not necessarily turn out to be expensive after all.
TRI have a 5 year EPS average growth rate of +29%/annum and a confident chairman's outlook. OK its a exceptionally boring widget manufacturer/distributor with a SR of 90, but it was and is executing exceptionally well. Ian
Hi Paul,
A flip side to talking about high P/E ratings. Northen Bear (NTBR) reported interims. They have a P/E rating of 4.7. Your challenge is to tell me why because I'm stumped.
Thanks Mathew
Mathew
Thanks for the pointer to Northern Bear (LON:NTBR) interims. I DMOR and concluded they were a safe hold with a dividend that would probably be 5% when the finals are announced (and they might get a well-deserved re-rating after their finals), so I bought 20K.
Paul - I assume that the "intersting post by Mark Bentley" link is supposed to go to that post but it doesn't. It goes to the Investegate site with the RNSs of Redcentric.
Laughton,
Thanks for pointing out the incorrect hyperlink, I've now corrected it.
Regards, Paul.
Thanks Paul,
I know you have commented on Getech (LON:GTC) before. I am amused that the share price was down today on the results announcement, as I think it is impressive they report a profit in their current market. Maybe they are over-optimistic, but I think Getech are doing their best to survive the period of depressed crude price and be best positioned to take advantage from the revival of exploration in the future. Lots of operational gearing there, so I can really see Getech bringing a few millions of profits at some point (the company is currently valued under 10m).
Cheers,
Thomas
Talking of trading updates - "materially ahead of expectations", you might have missed a great update yestrday from KWS -Keywords. This is company that does graphic and audio design and programming for gamesmakers -mobile, console,app etc. It has a huge moat having acquired a lot of small players and is used by 21 of the 25 largest gamemakers. It is growing at a wonderful pace with a large international presence.
Paul - I couldn't agree more with all of your thoughts on Fevertree. I've previously written about growth investing through the lens of QVM / factor investing. This article is particularly interesting for anyone reading who uses the StockRanks and likes buying expensive stocks - http://www.stockopedia.com/content/high-flyers-how...
Basically, there's a set of nosebleed expensive shares (that no value investor will touch) which have very high Quality & Momentum rankings... which consistently outperform. They normally have a ranking profile like this:
We've seen it in stocks like Boohoo and Fevertree recently, but in recent years there have been dozens of standout winners with precisely this kind of profile - from Dominos, Betfair spring to mind here to any of Facebook, Amazon etc in the USA.
Fevertree might only rank 65 for its overall StockRank - but its "QM Rank" is 96/100... so it's in the set.
What Value investors need to realise is that "value" is just one of several risk-factors or styles that pay off in the market, but each of them comes in and out of fashion at different times. The opportunity cost of sticking relentlessly to value investing can be seriously expensive.... it's worth adding exposure to other factors to hedge the risk of underperformance.
Thanks Ed,
I agree very much. I'll check out the QM ranks, to see what's in there.
Certainly for me, the penny dropped a couple of years ago that value shares didn't seem to be going anywhere, and that GARP stocks were really where the market was going. Accordingly, profit from like Boohoo.Com (LON:BOO) have really hoovered up all my value share mistakes.
As you say, the market goes through phases, and it's just not interested in value right now. However, at some point the music is likely to stop, and suddenly growth shares will sell off, and value shares will come back into fashion.
To my mind there are really 2 approaches to finding good shares, namely;
1) Shares that are mispriced right now, and
2) Companies that are likely to out-perform, hence won't look underpriced yet, but it will become apparent in the future that they were under-priced, after more growth has happened.
Regards, Paul.
Hi Paul
As an ex analyst from both a midcap Broker and an Investment Bank I thought I'd chime in on your interesting point. As we all know any good FD worth his salt will always try to under promise and over deliver. A good example of this was Ed Power at Kentz (whom I used to cover). There was always pressure on him to be less cautious and he consistently ignored the pressure and Kentz consistently beat expectations.
As a covering analyst, if you really like the equity story of a company you adopt a similar viewpoint. You want to remain cautious yet optimistic with your forecasts, so you can keep upgrading them. It's much better than getting ahead of yourself and having to rein in your numbers. I think when you get these sorts of excellent growth companies like FEVR and BOO what we see in terms of analyst forecasts being too pessimistic is a combination of this optimistic caution as well as analysts literally not being able to keep up with the rate of change.
Cheers
Rob
Rob
I think you make a good point about behavioural finance in regard to analysts. I have generally found (but don't have statistical evidence) that the more bullish the analyst, the lower their short-term earnings estimates and bearish analysts have high short term earnings estimates. Then when the actual numbers come out both sets of analysts can "defend" their views that the numbers were even better/ worse than they had forecast and therefore retain support their buy/ sell rating.
Today's Edison note on the KWS upgrade illustrates your point very well.
" Full-year results are now expected to be materially ahead of consensus and we upgrade our FY16e EPS by 13%. Erring on the side of caution, we have not changed our FY17 estimates significantly. Nevertheless, we believe the company does have a platform to sustain double-digit earnings growth, and hence medium-/long-term prospects for further share appreciation remain good."
Ed,
To be fair, whilst it's OK illustrating the shares with high Quality and Momentum rankings that worked out well, for a serious analysis you also need to include those with the same ranking that subsequently tanked? That would highlight Paul's argument better.
Paul,
Re: social media I couldn't agree more. It's solely responsible for the increasingly narcissistic outlook of many people. As an example... today we have one of the most important events of modern times going on in the USA and I just looked at the BBC News website and the lead story is Prince Harry's girlfriend being trolled on twitter!! Can you believe it - even the Beeb is turning into Hello magazine.
All the best, Si
For a dystopian view of where we are headed with social media, watch the new series of Black Mirror on Netflix.