Small Cap Value Report (Fri 12 July 2019) - TCG, BOOM, MGR, FLO, GYM, SIXH, MERC

Good morning!
I will scroll back and look at events from earlier in the week, once I've covered today's news.
- Thomas Cook (LON:TCG)
- Audioboom (LON:BOOM)
- Miton (LON:MGR)
- Flowtech Fluidpower (LON:FLO)
- GYM (LON:GYM)
Now let's catch up on two stories from ealier in the week:
- 600 (LON:SIXH)
- Mercia Asset Management (LON:MERC)
Thomas Cook (LON:TCG)
- Share price: 8.5p (-36%)
- No. of shares: 1536 million
- Market cap: £130 million
The fat lady is singing for shareholders at Thomas Cook (LON:TCG), where the proposed recapitalisation envisages that "significant amount of the Group's external bank and bond debt will be converted into equity". Commiseration to anyone who is holding this.
We've not written much about Thomas Cook in this report. For me, there were two obvious reasons: 1) until recently, it hasn't qualified as a small-cap, and 2) the writing has been on the wall that the equity was headed for disaster, so there would be little to say.
IG says that these shares are unborrowable, but I know one or two bears who managed to open short positions - well done to them!
Prospects remain extremely bleak, even at 8.5p. If the company avoids administration and has an orderly recapitalisation, the best-case scenario that I can imagine for existing holders is that the fundraise happens at 1p (putting a value of £15 million on the existing equity).
The only reason for creditors and new equity investors to offer crumbs to the existing equity is to get the recapitalisation voted through. But if shareholders reject the recapitalisation, then administration beckons and with it, the likelihood that they get nothing at all.
Needless to say, I reckon these shares are uninvestable - further downside to come of at least 90%.
Audioboom (LON:BOOM)
- Share price: 255p (unch.)
- No. of shares: 14 million
- Market cap: £36 million
New podcast studios open in New York City
Audioboom has opened new recording studios in New York. This confirms what I've said before - the company is transitioning into a content company, rather than a technology company.
It's important for companies to be clear about where their competitive advantage lies. YouTube*, for example, created the best video platform, and ordinary people voluntarily created content for it (eventually with the incentive that they could take a share of YouTube's advertising revenue).
Audioboom has decided to do things the other way around: it is going to incur the cost of content creation, and then hope to cover its expenses and generate profits through advertising revenue. This is more like the business model of a traditional TV or radio network, rather than a cutting-edge technology company.
Miton (LON:MGR)
- Share price: 45.55p (-3%)
- No. of shares: 173 million
- Market cap: £79 million
Miton sees (small) net outflows from both equity funds and multi-asset funds. The overall Q2 outflow is £87 million (about 2% of AuM). This follows a flat Q1.
Investment performance was strongly positive (although this is less interesting, since it's largely beyond Miton's control). The overall result is that AuM increased 8% in six months.
CEO comment:
"In common with much of the industry, we experienced outflows from our UK equity funds reflecting both the wider concerns about the UK market and the divergence in returns from different parts of the market, post the 2016 Brexit vote. Our funds are actively managed and at times their performance will differ from peers and the wider market."
Miton does have some US and Europe funds (e,g, the US Opportunities Fund) but their numbers are being dragged down by the outflows from UK funds.
The UK equity market already struck me as a bit unloved, and announcements like this help to confirm my suspicions.
Miton shares pass four of Stocko's screens (including income) and are cheap on a variety of metrics:
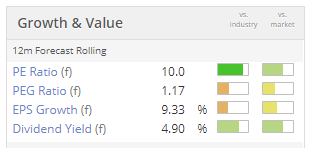
My view: There is always a question mark around diversification. Miton now has four distinct investment teams, each managing at least £600 million. The diversification across different teams and geographies seems ok to me, so I think the valuation here is too cautious.
The StockRank is 89.
Flowtech Fluidpower (LON:FLO)
- Share price: 132p (+5%)
- No. of shares: 61 million
- Market cap: £81 million
This H1 update is in line with expectations.
As a measure of cash generation, net debt has reduced by £1.1 million in six months, which is after making a defcon payment. So on a fair underlying basis, the debt reduction is more like £2.7 million. Net debt is £18.8 million.
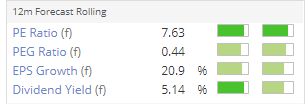
My overall impression of this company is positive, but my understanding of its activities isn't strong enough to forecast is prospects. Value hunters may wish to sniff around.
GYM (LON:GYM)
- Share price: 250.75p (+3%)
- No. of shares: 138 million
- Market cap: £346 million
This update is in line with expectations.
Everything is on track, with 15-20 gyms to open this year. "Another year of strong profitable growth for shareholders".
Membership numbers are up by 10% compared to a year ago, and average monthly revenue per member is up 5.6%, too - a nice combo. Extra revenue is being picked up from premium memberships and other sources.
This looks like one of the better rollout stories - it reiterates that "strong operating cash flows [are] funding the rollout of new sites".
Memberships can be cancelled at any time, which might make revenues a bit more volatile compared to traditional gyms, but I suppose this is an essential part of the low-cost model!
From Wednesday:
600 (LON:SIXH)
- Share price: 20.3p (1%)
- No. of shares: 117 million
- Market cap: £24 million
This engineering group has had a great year, disposing of its pension scheme and simplifying the financial outlook for investors. It provides machine tools, components and laser systems.
There has also been a huge improvement in operating margin (on an underlying basis, it increases to 8.1% versus less than 3% last year).
65% of revenues derive from the USA, with only 15% from the UK. It has 3 sites in the USA (versus 2 in the UK). I don't think the operating margin improvement came from currency movements - this might be worth checking. The company says most of its purchases are in dollars, too.
Outlook sounds fine:
Despite certain macro-economic and political uncertainties impacting customer sentiment, enquiry and quotation activity remains stable with revenue visibility underpinned by an improved orderbook.
As we've noted before, there are 44 million warrants outstanding, enabling convertible loan holders to convert their loan into shares at 20p each. The loan notes and the warrants expire in February 2022.
So the share count could increase to 160 million, for a market cap of £32 million ($40 million) at 20p.
600 says that its adjusted net income from continuing operations this year was $4 million, leaving us with an adjusted P/E multiple of 10x.
The adjustments look reasonable to me - they relate to things like the pension scheme, the convertible loan, changes in tax rates, onerous lease provisions, etc. (see page 42 of the annual report).
Aside from the convertible note, net debt at year-end was $5 million.
My view - This seems to be in good shape and offer decent prospects.
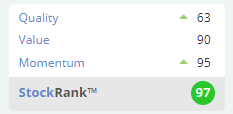
The StockRanks absolutely love it, giving it an almost perfect score:
From Tuesday:
Mercia Asset Management (LON:MERC)
- Share price: 32.7p (-1%)
- No. of shares: 303 million
- Market cap: £99 million
I've not looked at this one before, but it attracted some great comments underneath Tuesday's report.
It's a specialist asset manager, providing equity and debt to businesses in the UK regions (i.e. not in London). It had a noteworth win with Blue Prism (LON:PRSM), which turned out to be a 100-bagger for it.
In addition to its own funds, it manages the best part of £400 million on behalf of third parties.The majority of this is in venture capital, with the rest in private equity and debt.
It uses 3rd party funds at the start of a company's life. The most promising investees are then eventually brought on to Mercia's own balance sheet, after achieving a certain amount of growth and scale (presumably this transfer happens at a fair price to 3rd party investors).
Of Mercia's directly owned portfolio, 37% of the value is in the top 3 holdings: nDreams (17%), Oxford Genetics (11.6%) and Warwick Acoustics (9%). So it's not fully diversified but nor is it very heavily concentrated.
30% of the directly owned portfolio is still classified as "early stage" (maybe pre-revenue), while just 8% has reached profitability. The key sectors are:
Results
- Net assets £126 million, NAV per share 41.6p.
- Operating profit £2 million (from £1.3 million)
- Cash and equivalents of £30 million.
Outlook confident and determined.
Notwithstanding the challenging political, economic and market sector climate, the Group looks forward to this financial year with great energy and purpose. The Board will remain focused on the progress of the largest balance sheet direct investments and the pace and scale at which these are being developed.
My view
This suits me in terms of the sector and I like the strategy - it makes sense. There's plenty of talent in UK regions away from London, and the deals might be available at better prices than you would find in London.
I also like the mix of 3rd party and direct investing, though I need to do more research into how it works.
Profits are currently small relative to market cap, and I think they could be lumpy, depending on the timing of exits from big investees. Of more interest to me is the Net Asset Value per share (41.6p) and whether this is a reasonable estimate. More work is needed to figure this out, but thanks to readers for flagging it to me! I will look into it.
That's it for today, and for the week - thanks everyone!
Have a good weekend.
Thanks,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Think that MERC is certainly a very progressive company going places and Simon in Investors Chronicle is vert big on them and will certainly give some great bullish news on them to keep them flying high . Will not have raised all that money for nothing so look for a big announcement
Hayashi - only two years in, but the petrol XE has been a revelation. Said goodbye to the IS200 with some misgivings (still in good nick overall and an agile car to drive) but fancied a change at age 70 and the Jag's comfort and handling are superb. Now only doing about 10K miles per annum and averaging nearly 10 m.p.g. better than the IS. No squeaks and rattles to date and the stop /start has worked out that I do not want it! Visibility can be tricky at angled junctions and boot not great, but helped by (optional) split/fold seats. No regrets so far!
Hi John. IS200 SE. It was mainly17 annual services, but it did blot its copybook with a brake caliper seizure at around 200,000 miles!
GYM (LON:GYM). I've been going to the same gym for 17 years, in which all the equipment has been changed twice, so perhaps depreciation over 7.5 years is an industry standard.. Over that time I guess numbers have declined a little, probably due to increased competition.
Miton
'Investment performance was strongly positive (although this is less interesting, since it's largely beyond Miton's control).'
Er surely not. The whole point of active managers is to do well compared to the comparative group and the market. perormance is one big reason that new money comes in. Look at Woodward. I reckon that Miton overaall were up on their funds by about 12% in the first six months. That is pretty good. Their really big funds - UK Multicap Income (£!.2bn), US Opps (£634mn) & European (£610) have done pretty well though the first two have slipped to lower second quartile over 3 years and 1 year. European is absolute top of class over 3 years and 1 year and that is a big class of over 100 competing funds. Unusual and very impressive. Their UK Smaller (£129mn) appears to have n awful record however.
I have only been reading the recent AUM headlines on active fund managers but it seems to me that among the 'boutiques' Liontrust are doing really well. Though one has to concede that on the profits front Polar Capital has been outstanding.
So the share count could increase to 160 million, for a market cap of £32 million ($40 million) at 20p.
600 says that its adjusted net income from continuing operations this year was $4 million, leaving us with an adjusted P/E multiple of 10x.
but if the warrants are exercised, 600 (LON:SIXH) will use the monies to repay the debt, saving 8% of $9.5m per annum i.e. $0.76m. In that case, net income would be higher, at $4.76m and the P/E multiple would be 8.4.
Asagi (long 600 (LON:SIXH) )
GYM (LON:GYM)
This is from the admission document - this suggests it's wasn't standard to have break clauses with regard to the sites they had at that time of admission (2015)
I am very sanguine about the long lease situation , you can look at it as potential millstone around their neck and it may be. However i would say gyms are not exactly like shops - move a shop and most of the customer base will go to the new shop unless its a very generic. shop type However if a gym moves and a new gym replaces that gym in the old location i would guess a high % of bods would be tempted to go with the old site if its roughly the same ?? i may be wrong in that regard - not ever having frequented a gym i am the exact opposite of an expert. Perhaps my experience comes from pubs where as long as the price is right and the drink acceptable the name on the door matters not.
Presumably with such long leases there can be mitigating steps put in place to come to compromise agreements with landlords - if on wants out and the premises can be re-let?
Fundamentally if i though that if they cant have shelf life of 15 years with the gyms they open i wouldn't want to be investing anyway - i do admit though i would guess gym popularity may come and go over time and disruptors may turn up with better offering (virtual gym anyone?) so i would agree there is some risk element here that they could end up like Debenhams i guess.
Audioboom (LON:BOOM). I suspect there are high risks with transitioning from podcast applications to studios.
When I listen to podcasts, it's the content that matters, not a fancy studio or the app. I loaded Player FM, for "Invest With The Best" content & when that was exhausted, loaded Podbean for some other content. The app, the tech and the studios were secondary considerations. Even though I detest Podbean as an app, I have it for the content.
I would imagine most other users decide to listen for the content, not a fancy production studio ?
Incidentally, most of my recent "podcast" listening has been YouTube videos (e.g. Mohnish Pabrai) converted to audio via onlinevideoconverter (commendably slick) and then played back with Player FM. A lot of these were recorded where he was presenting in person or presenting remotely from his office PC. No fancy studio.
Would be a bit wary of asset managers with open fund structures especially with a small/micro cap slant at the moment with the BoE is making noises about regulatory changes following the Woodford gating debacle.Miton seems likely to be impacted by any changes.
Trade payable at Lookers may well linked to consignment stock of new vehicles, so not as potentially damaging as might first appear. Strong cash generation and solid asset backing has encouraged me to dip a toe in this morning.
A lot of car dealers own considerable freehold property portfolios. So the downside risk may not be as bad as people think, at least for now. I remain of the view that most people will still want to own their own car - it's a status symbol, and an object of pride for many people, and something you can personalise, it's a home from home. Using an autonomous vehicle instead would just be like catching the bus, instead of using your own car - i.e. not something you want to do, but is occasionally necessary!
At 36p, Lookers has a mkt cap of £140m.
Its last reported NTAV was higher, at £168.5m, which includes £250m freehold property.
The main drawback with Lookers for me, is the recently announced investigation into its selling techniques, which could involve fines.
On balance I'm also steering clear of this sector at the moment, although at some point there could be asset-backed value there, perhaps, if mkt caps drop a long way below the value of freehold property.
Thanks for this Paul. I have had two cars in the last 19 years, both from Lookers and have always found them very good to deal with, albeit servicing is expensive (but the coffee if waiting is great!). First of these was a Lexus, which lasted 17 years and service was so good that I bought some shares and went to Lookers AGM in Manchester to sing the praises of the dealership. Met the now CEO Andy Bruce there and impressed. When the Lexus went a couple of years - and 230,000 miles- ago, Lookers gave me an excellent deal on new Jaguar XE, which has been faultless to date. Bruce certainly has issues coming at him from everywhere (and the biggest uncertainty is indeed over the FCA investigation) but my gut feel is that with patience it will come good. Not perhaps the best reason for trying to catch a falling knife!
I'm surprised that someone driving a Lexus would have that much contact with the dealership!
Amazed the Lexus went..these cars are almost indestrcuctable/reliable. Had to be talked into getting one..now on the second. One point I have never figured with driverless cars...I happen to quite like driving. Don't think I am alone..will you be able to continue?!
No chance of getting 230,000m out of the Jag.
GYM (LON:GYM) 250p
Numbers look most excellent - i remain on sidelines unfortunately having sold out some time ago when price was higher - i wish i had bought back in when price dipped dipped below 200p. These numbers to me de-risk the business somewhat as it proves they are executing according to plan.
a google search for peel hunt and gym dated today tells us the following presuming they have been correctly quoted.
Wowsers a doubling of profits - from what level though? - is that doubling £20 mill to £40 mill - or is 2019 part of the figures - as 2019 profits nearly doubled anyway - i am kind of presuming they are gunning for the 40 mill figure - this would presumably be £30 mill ish + post tax and presumably eps north of 22p? - those numbers sound too good to be true in some respects?
My slight concern with this company is whether the profits give a fair and true reflection of reality - its easy to under account for "depreciation" in a business like this.
Also the IFRS16 changes - the wording above suggests under the new rules the financial metrics wont look as good - lower profits or higher debt/other liabilities presumably?
In summary all looks most excellent today and a pe of 18 * 22p = 400p target price in a couple of years seems do able which is some decent upside.
There is quite a handy presentation on the GYM (LON:GYM) site about IFRS16 and how this affects the accounts, basically dilutive in earlier years and accretive in later years.
Average lease time left of a gym is 16.5 years, with some £300m+ of lease liabilities. Looking at the number of gyms I suspect the deals they negotiate are fairly good ones.
Buried at the bottom of the report is a note about how they have changed their depreciation on equipment - they have now extended their useful life as there is evidence that more stuff is surviving longer.
I too regret not buying in at under 200p. Management appear focused and their execution is good. I did believe there could be a threat from Sports Direct, but at the bottom end of the market I do believe it would be really difficult for another low-cost provider to undercut them. So, there may be scope to increase rates a little further although I think there is a natural limit on how far it can go. Very few people would pay £30+/month for instance unless there was a very good convenience factor.
average lease term 16.5 years! is this the Debenhams model?
GYM leases - it would be worth checking if they have break clauses in those leases, as that's the ideal scenario - longish leases, so you can hold on to the profitable sites, but with 5-yearly break clauses, so you can ditch any problem sites.
Lookers (LON:LOOK)
Not a great fan of this sector (probably an understatement) and the share price action almost seems to be replicating what it did in the last recession in 2008 ish - albeit they are ahead of the curve in that regard in taht there is no recession yet.
I have generally been very bearish on this sector as i see cars as all being mostly electric (less parts to fix
) potentially sold/leased direct and potentially maintained by the car companies themselves or by their appointed repair outlets which may not be the current dealers ?- tesla has shown the way to go with their numerous over the air updates and taking stuff in house maintenance wise. I would guess 100%+ of the profits (is that possible) comes from the ott dealer rates they charge for servicing and the like.
Having said that the lookers market cap is now down to 180 mill - and it is still decently profitable - and it has decent wad of freeholds so potentially the tangible assets may provide a decent backstop perhaps. I have though had a look at the balance sheet per the last annual report and there is trade payables of £1.2 Billion - this is mostly match by inventories of £1 Billion - these numbers are too big in relation to the value of the freeholds to give me comfort that there would be much left if they did have to wind down the business - even a 10% write down on inventories would be £100 mil which is more than two years profit. I also get the feeling that closing down outlets would have significant costs attached too.
Note my thinking with regard to the dealership models is more pessimistic than most i must say, so my thoughts are definitely biased in that regard.
Having worked in the industry at a fairly senior level for over 25 years, sadly I concur with your observations re long term outlook for dealers. Also, within the next 5-10 years people will start to forgo the hassle and cost of owning cars for in city travel/commutes and use autonomous electric vehicles via mobile apps. The manufacturers are all busy working on these solutions. E.g., VW have today announced they are committing $2.6B to Ford autonomous programme. For dealers, I can only draw parallels with the horse industry in the first half of the 20th century. They will still exist but in relatively tiny numbers.
@mandragogoran
You are much more optimistic about the technology breakthroughs that will be needed than I am (and I work in the safety-critical software industry).
But even if the autonomous vehicle (AV) technology works perfectly, what the car passenger will have with your scenario is a driverless version of Uber - which they already have available today. And it won't have a driver to clean the car from the mess left by the previous passengers, respond to unusual situations, or break the law if necessary to get round an obstacle or avoid an attempted robbery.
So if you are right, Uber will make more profit by not having to pay their drivers but passengers will get a worse service than they can have today and there will be fewer incentives than already exist to give up their personal car.
The motor manufacturers are investing heavlily because if autonomous cars are successful they face an existential threat from the tech companies, as cars become more and more "computers on wheels".
Maybe it will be the cybersecurity companies that will profit from AVs, once the risk from successful cyberattacks becomes a real problem. "In a gold rush, invest in shovels".
Once it becomes apparent that the tech does not fall asleep at the wheel, does not drive the vehicle drunk or high, does not have a blind spot, does not tailgate, does not lose concentration, won’t do a hit and run, etc etc the public will start to think that vehicles that cannot do this are a menace. Of course AVs will fail from time to time but as clear water becomes evident with the safety record of other vehicles public opinion will shift in their favour. The desire for near to 100% safety record in order for AVs to be accepted will abate.
Furthermore, business people will start demanding driverless capability so they can spend time in the vehicle making phone calls etc. Cyclists may start demanding that vehicles that cannot monitor their blind spots with sensors be banned to reduce the number of serious accidents involving motor vehicles and cyclists.
I cannot think why a driverless taxi would be dirtier than one with a human driver when the companies operating them will clearly be able to afford to spend some of the money saved on not having drivers on cleaning them regularly through the day and surely they will have some sensors to detect when they need cleaning.
Insurance costs have become prohibitive for young people so why bother spending all that money on driving lessons and insurance if you don’t have to? The attraction of being able to go out drinking and no one having to limit their intake because they are driving is also likely to appeal to a certain segment of the population. Insurers already offer discounts to people who are happy to have their driving monitored by a black box. So, there will be plenty of financial incentives to gradually adopt vehicles with more and more safety features to the point where the vehicle itself is taking care of the vast majority of the driving tasks anyway. Advanced Emergency Braking Systems are already starting to be fitted as standard, so humans will not be allowed to have full control of braking in some circumstances.
https://europe.autonews.com/automakers/eu-japan-back-automatic-braking-regulation
It’s very hard to predict the speed of change but it could come much faster than people think. My own prediction would be within ten years as the environmental need to change away from fossil fuel powered vehicles will be speeding up the rate at which vehicles get replaced anyway.
Seems to be an incredible dilution in prospect for Thomas Cook (LON:TCG) to get that type of cash.
I do wonder post-dilution there may be a buying opportunity in prospect? Finance charges were crippling its results. Even after £750m the group will be heavily indebted though.
Last time I read up about them their airline was not in bad shape, and would have been bolstered by the failure of Monarch and to a lesser extent Flybe. Today we read that Norwegian boss Bjorn Kjos has stood down and their airline looks in very bad shape. Norwegian ceasing operations would be very good news for the likes of Thomas Cook.
Miton (LON:MGR) please.
Half year update shows an 8% increase in AuM thanks to a strong market/investment performance. Q2 is the first quarter to have a net outflow for a couple of years and results include a large drop from 2018 H1 (Inflows: £616m) to 2019 H1 (Outflows: £82m).
Creditable trading update from Flowtech Fluidpower (LON:FLO) given the sclerotic state of the UK government and increasingly uncertain economic outlook.
The management of Flowtech Fluidpower (LON:FLO) do seem to know what they are doing but I do feel that these sort of businesses ( small companies supporting manufacturing ) are likely to be hit badly in the forthcoming recession. Reluctantly I sold out last week.
Flowtech Fluidpower (LON:FLO) has an in line (but slightly positive) trading update this morning.
----------
Group Trading Update and Notice of Half-year Results
"Flowtech Fluidpower has achieved further organic growth of 2.9% and reduced net debt by GBP1.1m in H1 2019. The Group expects to achieve another year of solid progress; results are in line with market expectations"
GROUP Trading Update AND FINANCIALS
HY1 2019 HY1 2018 FY 2018 Growth
Unaudited Unaudited Audited H1 2019
GBP'm GBP'm GBP'm v H1 2018
----------- ----------- ----------
Divisional revenue:
Components 50.0 46.9 6.5%
Services 9.6 9.5 1.4%
Total Group revenue for
the period 59.6 56.4 111.1 5.7%
----------- ----------- ----------
Net debt 18.8 18.0 19.9
------------------------- ----------- ----------- ---------- -----------
Group revenue during the first six months of the current year increased by 5.7%. On a like-for-like trading days' basis organic growth was 2.9%, the balance resulting from 2018 acquisitions. Quarter 2 saw a reduction in organic revenue growth, relative to Quarter 1, reflecting the wider economic conditions.
Net debt at 30 June 2019 was GBP18.8m. This represents a GBP1.1m reduction from the position as at 31 December 2018 and compares favourably with a net debt increase of GBP3.0m for the comparative period in 2018. The GBP1.1m reduction in debt is after making contingent consideration payments of GBP1.6m relating to prior year acquisition activity.
Our continuing focus on working capital management should lead to further debt reduction by the end of 2019.
SUMMARY
Overall, our trading in the first half is in line with full year market expectations and we continue to expect to deliver another year of solid progress despite less buoyant market conditions. The Directors remain confident about the future for the Group and look forward to updating shareholders on its cost reduction and working capital initiatives at the time of the Half-year results.
NOTICE OF RESULTS
The Group is planning to release its Half-year results on Tuesday, 24 September 2019.
My morning smallcap tweet: Thomas Cook cooks holders in rescue D4E.
Thomas Cook (LON:TCG), Palace Capital (LON:PCA), Lookers (LON:LOOK), Emmerson (LON:EML), Open Orphan (LON:ORPH)
Thomas Cook Group (TCG) Market has got tougher so gives up on asset sales and plans £750m recapitalisation with significant dilution for holders. No indication of likely price. Guides H2 EBIT down YoY. I'm short.
Palace Capital (PCA) AGM stmt: Interest in flats in York development has been stronger than expected. I hold.
Lookers (LOOK) Q2 'increasingly more challenging' with new regs down 4.6%. Also weaker demand for used cars. Guides H1 U/L pretax £32m (£43m) and FY below its previous expectations.
Emmerson (EML) £2.25m placing at 3.75p, a 6% discount.
Open Orphan (ORPH) sells its remaining shareholding in Integumen for £566k.
Hi MrContrarian, how are you able to short Thomas Cook? Been trying for months but none of the spread-co's (IG, City, Spreadex) allow it :(
Hi mmc071, It was possible to short Thomas Cook (LON:TCG) on the 20th of May when the price was in the range 9 - 12p or so. I managed to get shorts on with IG and ETX that day though not in the size I would have liked. Though just after I put the short on with ETX I got a phone call from them saying that they couldn't get any more borrow, so that would be it for shorts.
Anybody who was short then had to hang on though as the stock took off towards 19p.
It really is a pity there isn't any borrow because at 8 1/2p, a short here would be an absolute gift.
(short Thomas Cook (LON:TCG) )
Hi MrContrarian, how are you able to short Thomas Cook? Been trying for months but none of the spread-co's (IG, City, Spreadex) allow it :(
For shorts, I think it helps if you telephone an order, or use an intermediary broker (as I do), rather than trying to trade online.
For example, even though the IG online platform is saying no to new short positions, my broker managed to successfully double my short position in Thomas Cook (LON:TCG) this morning, via Spreadex, who apparently themselves are hedging via IG.
I agree with Graham that existing equity likely to be almost wiped out in the proposed fundraising, and huge debt for equity swap.
The RNS today all but admits that, by saying;
There is an interview today with TCG's CEO, on BBC iPlayer, from the Today Programme this morning. He starts at 07:19 (1hr 19 mns into the programme). He starts to say that it is the best outcome for shareholders, then corrects himself and says best outcome for suppliers, customers, and employees!
Therefore it seems pretty obvious where the existing equity is going. I agree with Graham that a token value of say 1p per share might be attributed to existing shareholders, with new equity diluting them to virtually nothing by being issued at that price.
We don't know for sure, of course, but that looks the most likely outcome to me.
Regards, Paul (disclosure: short position in TCG)