Small Cap Value Report (Fri 29 June 2018) - SUH, MMC, RCH, CWD

Good morning, all. Hoping for some positive RNS announcements from some quality companies today!
Today we have:
- Sutton Harbour Holding (LON:SUH) - final results
- Management Consulting (LON:MMC) - proposed placing and open offer
- Reach (LON:RCH) - trading update
- Countrywide (LON:CWD) - share price sliding
Graham
Sutton Harbour Holding (LON:SUH)
- Share price: 33p (unch.)
- No. of shares: 105.6 million
- Market cap: £35 million
Sutton Harbour Holdings plc ("Sutton Harbour", "the Company"), the AIM listed waterfront regeneration and destination specialist, announces preliminary results for the year ended 31 March 2018.
This stock has always been a bit unusual. It's primarily a property play, with the potential for some additional income on top.
It now has a majority owner with 73% of shares, which it purchased at 29.5p.
The free float excluding that investor is only worth about £10 million. There are a couple of other large holders, too. So it's not too liquid.
Official net assets are £39.3 million or 37.2p per share, so the market cap offers you a small discount to that figure.
The property values are up-to-date but are falling, according to the latest valuations. Maybe a discount in the market cap makes sense, under the assumption that property values still have further to fall?
Worth noting that it is leveraged, using £24 million of bank loans on today's balance sheet.
Plymouth Airport
Some "hidden value" could be released from the company's lease on Plymouth Airport (now closed).
The Airport has been closed since 2011, and nothing has been done with the site yet. Various government bodies have been deciding what is to be done with it:
The Company currently awaits the outcome of the hearing and specifically whether the Government Inspectors will uphold Local Planning Authority's proposal to safeguard the Former Airport Site for 5 years for potential general aviation use (which includes private aircraft and other non-commercial passenger services), following which, the local planning authority proposes a review of the policy. The Company maintains that far greater social and economic benefit for the city will result from the development of the site for an appropriate mixture of residential and other uses which can deliver housing (including a substantial contribution to the need of social housing), community and educational facilities and employment space, effectively integrated with the existing surrounding developments.
Planning issues can be very controversial. In this case, the planning process means that SUH is left holding a derelict piece of land with nothing happening on it, as far as I know.
Operations - revenues from the company's fisheries and marinas have fallen, while car park revenues are stable. Gross profit from these sources is down 17.5% to £2.1 million.
My opinion - I can't remember how or why this stock originally ended up on my radar. Probably as a potential asset play, a couple of years ago.
As far as the situation now is concerned, it strikes me as fairly priced at a modest discount to NAV.
It likely is going to need positive news on the Airport site to trigger a re-rating.
Stocko algorithms are a bit more harsh, calling it a Sucker Stock (no quality, value or momentum!)
Management Consulting (LON:MMC)
- Share price: 2.75p (-12%)
- No. of shares: 511 million
- Market cap: £14 million
This is an operations consultant with offices around the world.
The Board announces that the Company is today launching a Placing and Open Offer to raise proceeds of approximately £8.5 million net of expenses under the Placing and Open Offer.
The discount to the current share price is extreme: shares are being issued at 1p.
To raise £10 million (gross), that will mean 1 billion new shares, so existing shares will represent ownership of just one third of the company:
Shareholders should be aware that the Board is of the view that it was necessary to set the issue price at this level to ensure the success of the Placing and Open Offer.
In other words, sufficient demand to invest would not have existed above 1p.
And without this injection of funds, the company will face a cash shortfall and insolvency next year.
When I covered this stock in August 2017, the Going Concern note warned that "all options" would have to be considered, if the company under-performed. The share price was 7p at the time. The 2016 annual report included a similar warning.
So this has been on the cards. The dilution is going to be worse than it might have been, but that's always the risk when a company needs to be refinanced.
I got some feedback in the comments section about professional services businesses which have done well for investors. Such companies do exist: Accenture ($ACN) and AON ($AON), for example. I guess I would need to do more research, to understand what set them apart from the others.
Management Consulting (LON:MMC), on the other hand, has been listed for 20 years. While it may be a successful company for its clients and employees, creating lots of value for those stakeholders, it has achieved very little for shareholders over that time. I don't see any reason for that to change going forward.
Reach (LON:RCH)
- Share price: 78.7p (+4%)
- No. of shares: 299 million
- Market cap: £236 million
This is the stock formerly known as Trinity Mirror (TNI). It owns the Daily Mirror, Daily Express, Sunday People, Daily Record, Daily Star, OK! and some big regional newspapers. It bought the Daily Express, Daily Star and Ok! earlier this year.
Reach plc is issuing a trading update for the 26 week period to 1 July 2018 ahead of its 2018 interim results announcement on 30 July 2018.
Let's see how the like-for-likes are performing:
Had Express & Star been owned from the beginning of 2017, Group revenue on a like for like** basis would have been expected to fall by 7% over the period with print declining by 9% and digital growing by 5%.
To break it down a little further, the Express & Star publications have been doing much better than the rest of the group. Their total like-for-like revenue is down by only 3%.
Net debt is £85 million. Impressively, the company had almost entirely eliminated its net debt by December 2017. It then bought the Express & Star publications!
Recall that the group's pension deficit is one of the most important numbers to watch. It is not mentioned today, but was last reported at £378 million (on an accounting basis).
Outlook is in line with expectations.
The company very helpfully includes these expectations at the bottom of the trading statement: adjusted PBT of between £131.7 million - £133.9 million.
My view
I don't know if I'm brave enough to buy shares in this myself. I am beginning to see a strong argument for it being undervalued.
We could put the enterprise value as:
- Market cap £236 million
- Net debt £85 million
- Pension deficit £378 million
- Total = £700 million
I suppose it's important to note that actuaries would probably put the pension deficit at a much higher level.
But still, the enterprise value shown above is only about 5x the adjusted PBT figure. Many of the adjustments will be non-cash and one-off charges related to the acquisition of Express & Star.
So I reckon this is definitely worth investigating to see if you can visualise the company emerging safely, with a normal balance sheet, in a few years' time.
Rising interest rates should reduce the pension deficit, too.
Value metrics are fantastic.
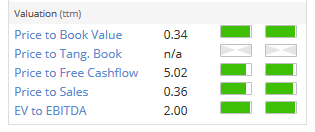
Would Express & Star have been happy to join forces with Reach, if Reach was headed for the knacker's yard? (I suppose a pessimist would argue that they are both headed to the same place.)
Another similar share, Johnston Press (LON:JPR), looks headed for worthlessness. It has a £220 million bond coming due next June, and the bondholders have formed a committee to discuss the situation.
Reach (LON:RCH) appears to be in a much healthier situation. The dividend yield is 8%. I will probably end up waiting until the outcome is a bit more certain, but this one is going on my watchlist.
Countrywide (LON:CWD)
- Share price: 36.7p (-8%)
- No. of shares: 238 million
- Market cap: £87 million
It has been pointed out in the comments that the Countrywide (LON:CWD) share price has continued to slide all week.
On Monday, it announced that it wanted to raise equity finance to cut its debt load in half, i.e. about £100 million. The share price was c. 60p when I wrote Monday's report.
There has been no news since then, but the share price has continued to slide. The market cap is now less than the amount it wants to raise, and less than half of the debt load.
A bit like the situation with Management Consulting (LON:MMC), the scale of the dilution being faced by shareholders is escalating.
That's the big problem with equity refinancing. As a shareholder, you might look at the share price and think "I will still be left with x% of the company after the placing, it's not so bad". But if the placing ends up being at a much lower level (and it's impossible to predict where a placing will take place, without inside information), then the percentage you are left with could be just a fraction of that.
All done for today and for the week. Thanks for dropping by!
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Hi All
Earlier on this week there was some interest in the sale of shares by the directors at Ramsdens Holdings (LON:RFX) which also resulted in the share price falling. I contacted their investor relations department to get some clarity on the reasons behind the share sales and whether it was related to the underlying business. I got a response earlier today from Lucy Wollam from Hudson Sandler:
"The sale of shares by Peter, Mike and Jason were undertaken for personal finance reasons, and were their first sales since the IPO in 2017. They all retain a significant holding. In respect of Peter, his sale is fully in accordance with the lock up given on Admission to AIM in February 2017 and he still holds more than 1m shares."
There's no mention of deterioration in trading so wonder if it's a buying / top-up opportunity.
Hi Reacher,
re your comment on Ramsdens Holdings (LON:RFX) .
And particularly your reaction to the fact that the directors sold for "personal finance reasons"
Even if it were the case, would you really expect to get a response for IR along the lines of "well yeah, things aren't going great at the moment, so they thought it was a good time to sell"?
No offence intended, but I don't think the response you got provides any real clues as to the investment merits.
I wouldn't really like to guess, a factor in the timing and that they all sold together might simply be that a few days after publishing their full results would be seen as the time when it was most clear that they held no un-published price sensitive information.
Hi Gromley, no offence taken and it’s always good to get another perspective. I believe under the listing rules a company would need to officially disclose whether there was a deterioration in the business that would lead to results being below expectations. Whilst I wouldn’t expect a PR company to disclose that, I do think the explanation about the lock-in period made some sense.
I just wanted to share the information I received. I do consider Ramsdens operating a diverse business which is why I though it was an opportunity.
Have a great weekend!!
Thanks Reacher,
totally agree that if there were any deterioration in trading they would need to inform the market and the directors would be in a closed period and unable to sell until after that announcement was made.
On the other hand if they generally just felt that the market say 12 months looked less rosy they might consider there be no need to inform the market but that it would be a good time to sell and cite 'personal financial circumstances'.
I'm not for one moment suggesting this is the case here; in fact from what little I know of Ramsdens Holdings (LON:RFX) I would have thought the short/medium economy should be beneficial. I just thought though that the PR "would say that wouldn't they".
Interesting though that you refer to the lock up; I think you are inferring that this was the first time they were allowed to sell since IPO, which would make sense of the whole thing; but I didn't read that from the response you quoted.
Anyway as you say different perspectives on things are always a benefit.
Thanks for the dialogue on Ramsdens Holdings (LON:RFX). As one of you says, dialogue brings out good and different thinking. I would like to throw another thought into the equation. They all achieved the same price of 180p, a relatively small discount from the 187p at the time? I guess the 1m shares all went to the same place, and we might see an institutional investor or two having increased their holding in the near future. It seems to be a very successful company, with good prospects. I am a holder and it has done me well. I intend to hold, and thought about adding, but the good opportunity has now passed when it fell to 165p or so, on the rather flimsy grounds of director selling. Anyway, the remuneration committee will soon build those shareholdings back up again, wont they, or am I being too cynical?
With regard to Reach I agree it has a lot of interesting facets, but as an investor you have to have a view on Goodwill and Intangibles and if you strip these out of the balance sheet you have negative assets. I like much of the story but cannot bring myself to buy on that basis.
That's a valid point Camtab from the last accounts we can see that TNAV is negative £235m (NAV of £666m)
Also potential investors running the numbers need to bear in mind that the latest published numbers we have give the position before the acquisition of the Northern & Shell business.
From the pro-forma balance sheet associated with the acquisition (page 79 HERE ) it looks like TNAV of the enlarged group would have been -£350m.
It is worth bearing in mind though that the pension deficits drive more than all of this negative TNAV - again from the proforma the pension deficit was £402m.
That's not suggest to that one should therefore ignore it, but one does just need to bear in mind that the deficit is a very volatile number (being the difference between two very much larger numbers calculated on questionable assumptions) - many believe the deficits will reduce in the near to medium term.
Actually though I would argue that there is some 'real' value in the intangibles, most of this is not actually 'goodwill' but 'publishing rights and titles' (£544m for the nationals and £254m for the regional titles - these being the figures before the N&S acquisition.)
These represent the "moat" (albeit one that is gradually evaporating), they are the differentiator that allows them to make money. I'm not suggesting that their titles are superior to those of the competition, simply that people are quite loyal to their choice of newspaper.
In some respects I would argue that the value of the titles is more tangible than the value of a grotty old printing press that has not yet being fully written down.
Anyway Reach (LON:RCH) will present their half year results at the end of July (I'm impressed that they are committing to the same time as ever, despite the integration) and this will give us the first proper opportunity to see the shape of the new group. I would expect to see the balance sheet somewhat better than the proforma numbers I reference above.
Anyone concerned about the balance sheet, therefore, probably should wait for a few weeks and review.
I continue to hold, largely because it is monstrously cash generative and whilst the acquisition disrupts that somewhat in the very short term it extends the longevity more than sufficiently to compensate - even if 'digital' never fully takes off.
The outlook for interest rates suggests that investing in high pension deficit companies could be a reasonable strategy while the market worries about the deficits. Reach (LON:RCH) is one of the most attractive of these on a cash flow basis. Other side of coin is that pensions regulator might become more draconian.
I'm not really sure it can be valued on a profits multiple though. Everything suggests decline is terminal. It's about how much cash it will produce before it falls off the cliff.
Reach (LON:RCH) is massively cash generative even in a declining market. I can see net debt eliminated again within 2 years and I think that ultimately the pensions deficit will be eroded significantly over the next 5 years from contributions + rising interest rates.
Revenues down 7% are relatively good news as cost cuts and synergies over the next 2-3 years should exceed that revenue decline without too much of a problem.
I am long. Happy to take 8% a year in dividends as I think when we come back in 5 years time profits will not be dramatically different to today but I suspect pension deficit will be 25% lower, and net cash will be circa £100m.
I'd expect the share price to be double in that scenario, so along with the 8% dividend thats in the region of a 20-25% annualised compounding return and I'm happy with that!
Short 3 mins with Warwick Brady, CEO of Stobart (LON:STOB) talking ahead of AGM on July 6th 2018
http://www.piworld.co.uk/2018/06/29/stobart-group-stob-ceo-interview-june-2018/
Vision for the future – 00:20
Current situation - 01:45
The Chairman, Iain Ferguson, CBE – 02:13
Plymouth Airport is, sadly, not a viable site, and cannot be expanded. Long term I suspect SUH will get their wish and make some profit from housing value. But there is a lot of resistance to change of use, and I wouldn't be surprised to see it run and run before that happened.
anyone watching Countrywide (LON:CWD) implode? Down 50% this week on big volumes after warning. Wants to raise £100-125m new equity. market cap now below £90m and debt probably £200m. Not sure they can wait to 26 July to update on recovery plan, might be over by then. Short
Thanks HB, I've added an additional comment on Countrywide (LON:CWD). Cheers
How can it cost Management Consulting (LON:MMC) £1.5m to raise £10m when they have irrevocable commitments from existing shareholders to buy the shares? If there isn't a cheaper way to raise the money, is it worth remaining listed? (No position - just boggled!)
Surely Fastjet have to be kidding!!!
Anyone any thoughts on Shoby investments selling 10 million Motorpoint (LON:MOTR) shares at 225.
Shares down 11% this morning.
Perhaps a buy opportunity?
Lloyd
I wondered whether there was a quick profit to be made from the fall in Motorpoint (LON:MOTR) but I'm put off by Jon Baird (one of the PDMRs) selling half his shares (some 377,500) ten days ago.
My morning smallcap tweet: Farcejet avoids crash with rescue placing.
Action Hotels (LON:AHCG), Management Consulting (LON:MMC), Akers Biosciences Inc (LON:AKR), Tau Capital (LON:TAU), Appscatter (LON:APPS), Fastjet (LON:FJET), LXB Retail Properties (LON:LXB)
Action Hotels (AHCG) Possible offer of 24p, a 50% premium.
Management Consulting Group (MMC) Placing and Open Offer at 1p to raise £10m to avert cash crisis., tripling shares in issue. 68% discount.
Akers Biosciences (AKR) will be suspended on Monday since they haven't published the AR within 6 months "due to the work ongoing to review and make appropriate adjustments to certain previously filed financial statements".
Tau Capital (TAU) will be suspended on Monday since they haven't published the annual audited accounts within 6 months.
Oneview Group (ONEV) another 90 day shareholder loan and previous ones extended.
Appscatter Group (APPS) FD scarpers on day of re-election at AGM. He is thanked and 'continues to be a supportive shareholder'.
Farcejet (FJET) to raise at least $10m in placing and subscription at 8p. Also £1.6m open offer. 146% premium! Expected to be sufficient working capital for the remainder of 2018.
LXB Retail Properties (LXB) cuts the expected realisation again to 26-28p/sh from 30-35p in Feb due to retail and leisure markets becoming even more challenging over the last three months. Will return 7.5p/sh soon. I hold.
Good Morning Graham,
I wonder, if you have time, if you'd like to cover off Inland Homes (LON:INL) as they have released a couple of RNS, this week and perhaphs Diversified Gas & Oil (LON:DGOC) ?
Thanks,
IG
Hi IG, the market didn't seem terribly impressed by those Inland Homes (LON:INL) announcements, did it? (disclosure: I currently own INL shares.)
The deals announced weren't game-changing news for me, but were still positive. CEO:
"These are significant transactions that demonstrate both the market-leading expertise of our planning team, as well as the appeal and variety of schemes that sit within the Inland Homes portfolio."
Same with the NED announcements. Positive, not game-changing.
What did you think?
re: Diversified Gas & Oil (LON:DGOC). it's not my sector, apologies :)
Best,
Graham