Small Cap Value Report (Fri 29 Sep 2017) - PURP, APGN, PIER, ITM

Happy Friday!
Purplebricks (LON:PURP)
- Share price: 377.625p (+1.4%)
- No. of shares: 272 million
- Market cap: £1,027 million
This unusual estate agency issues a bullish headline for its AGM statement:
Strong progress across three continents, on course to meet expectations
UK revenues are still guided to £80 million for the full year (ending in April) and H1 revenues should have more than doubled.
The US launch is underway, having begun on 15 September.
Quick excerpt from the CEO comment:
We are relentless at working to ensure we understand our customers' needs and meet their expectations and are proud of our 27,000 Trustpilot reviews and our NPS score of +80. Considerable progress has been made across the Group in the financial year to date and we are confident in our future and in meeting the Board's full year expectations."
Indeed, I too have referred to the online customer reviews when weighing up the pros and cons of potentially buying shares in Purplebricks.
However, it turns out that Purplebricks has been unhappy with what has been written about it online, when it's less than favourable.
The independent review website AllAgents suspended its coverage of Purplebricks following threats:
Due to repeated threats of legal action forcing the removal of content and negative reviews from our website, we have regrettably taken the unprecedented step in suspending the PurpleBricks profile page until further notice (as of the 18th September 2017).
It has even taken down the original notice of suspension, following more threats:
Not only, it appears, does Purplebricks not like what our reviewers say about them on allAgents, but they're also rather miffed about what we wrote about the suspension of the Purplebricks profile on our site. So, due to the further threat of litigation from Purplebricks, we've decided to remove it, despite it being entirely factually correct.
And how's this for a rhetorical blow:
In our humble opinion the thousands they're paying their lawyers to write to us might have been better spent responding in a positive way to the criticisms raised by our reviewers.
Ouch!
I already felt that Purplebricks was overvalued, but my conviction is growing. Companies should be able to take criticism, and allow customers to discuss their experiences without trying to shut down debate.
Shutting down debate is impossible in the current year, anyway, due to the nature of how the internet works.
To be fair to Purplebricks, their CEO claims that the AllAgents reviews which the company disputed were fake, could not be justified, or were by people who hadn't used the agency.
But have any other agencies had the same issue with AllAgents? Have any other agencies had their coverage suspended? If not, then the problem would seem to lie mostly with Purplebricks.
Applegreen (LON:APGN)
- Share price: 530p (-1%)
- No. of shares: 80.8m (+8.1 million Placing Shares)
- Market cap: £471 million (including Placing Shares)
Completion of placing raising EUR46.9m (£41.1m)
This is an Irish petrol retailer which has been expanding through the UK and USA.
I won't go into it in detail here but I'm flagging it as worthy of further research, because I think it does have a lot of growth potential, and the execution of the growth strategy so far has been excellent. The number of sites has grown from 152 to 283 since December 2014, and it's now in the process of acquiring US and UK businesses with almost 50 sites between them.
This placing is going to assist in funding those acquisitions and also help growing the rest of the pipeline too. It's a prudent move, as net debt had ticked up to €33 million by June 2017.
Today's placing was fully subscribed and sets the company up for the next stage of growth in an industry which might be set for a lot more consolidation in the years ahead.
Brighton Pier (LON:PIER)
- Share price: 114p (+4.6%)
- No. of shares: 31.8 million
- Market cap: £36 million
This group owns Brighton Pier and Eclectic Bars, and is run by the well-known investor and entrepreneur, Luke Johnson. He has a 24% stake.
The Pier was added in April 2016, so last year's results (i.e. results for the year ended June 2016) mostly don't include it. So there is no point in making a simple year-on-year comparison of results.
Actually, I'm finding these results quite frustrating. I want to see how the Eclectic Bars performance has changed year-on-year, but there is no proper segmental breakdown of the figures.
We are only told that the Bars division made an operating profit of £2 million before losses on disposals, but the corresponding number for last year isn't given! In my opinion, it's unsatisfying to have the analysis of performance broken down at great length into "Pier" versus "Bars", but then for each division not to have its respective contribution to group financial performance made explicit.
Making do with what's given, these are the aggregate results:
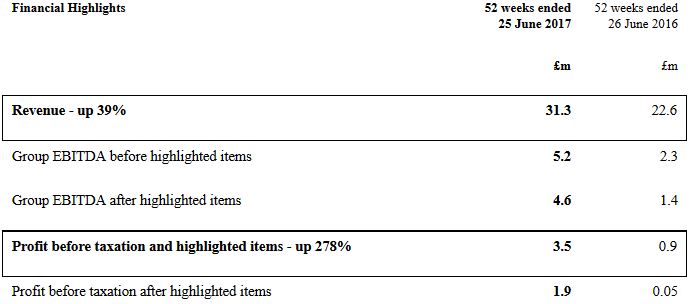
The Pier traded in line with expectations during the period, but the latest trends aren't so positive:
Since the end of the financial year, trading on the pier during August and September has been mixed and did not match the strong trading performance of financial year 2016, owing to rain and strong winds. The management team at the pier has shown itself adept at generating revenue when the sun shines and saving costs when possible.
Meanwhile, Bars improved its gross margin by 200 bps and tightly controlled its costs, disposing of six underperforming venues and closing its doors on unprofitable nights.
The group has an ambitious strategy to "create a growth company operating across a diverse portfolio of leisure and entertainment assets in the UK", hoping to become a sector consolidator.
Regular readers will know that I'm a sceptic when it comes to bars and restaurants. To me, they resemble airlines: there are very large fixed costs (rents, wages) and yet most players in the sector end up competing with each other on price. There is no long-term competitive advantage.
This particular company has net debt of £7.2 million (gross debt £11.3 million), doesn't pay a dividend, and has a strategy to seek out more acquisitions. If you have confidence in management and/or in the Eclectic formula, then fair enough. Personally, I would need a really cheap valuation multiple and preferably a strong dividend yield to get me interested. And that's not currently the case.
ITM Power (LON:ITM)
- Share price: 47.5p (+12%)
- No. of shares: 250.6m (before issuance of 73 million new shares)
- Market cap: £119 million
Proposed Placing and Open Offer
This is a hydrogen energy company which had a material uncertainty over its going concern assumption the last time I covered it.
It is in the process of sorting this out now, with a proposed placing and open offer to raise a gross aggregate amount of £29.4 million (£25 million in the placing, £4.4 million in the open offer).
The 40p issuance price is a discount to yesterday's close, but the news has been greeted positively so the shares are currently trading at 47.5p.
I took a look at some company literature and interviews a while ago, and was impressed with the technology. If hydrogen becomes more widely used, particularly by vehicles, then ITM could be exceptionally well-placed to serve this growing industry.
Revenues have remained very small so far, however, so there is no doubt at all in my mind that this is in the "speculative" category, and Stockopedia algorithms agree ("highly speculative"!).
But the work pipeline reported at the final results recently was some £35.5 million. Today, it upgrades that to £36.7 million of projects under contract or in the later stages of negotiation. How much of that will translate into profitable cash income is open to question.
We are also told that there are 50 additional projects worth up to £180 million in sales, where ITM has been "engaged to provide a written proposal, the client is understood to remain actively interested", and there is a belief that that the client "has the financial means and the ambition to implement the project in the medium term".
So it sounds as if ITM could potentially spring into life over the next few years.
This is how the fresh money will be used:
The net proceeds of the Firm Placing and the Open Offer (expected to be up to approximately £28.4 million) will be utilised by the Company to provide working capital to support the delivery of the contract backlog and opportunity pipeline, to move to new larger facilities to increase annual production capacity, to strengthen the Group's balance sheet, and to move toward achieving positive cash flow and profitability within the medium term.
My opinion
I'm impressed by the size of the placing, and would expect that ITM is financially secure for at least the next couple of years. The best case scenario, which can't be ruled out, is that no further funding will be required. Although if significant numbers of those 50 other projects turn into contracts, they could create a short-term shortfall.
As far as risky shares go, this looks like one of the more interesting ones!
That's all for this week, thanks for dropping by and have a great weekend!
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Re: ITM Power (LON:ITM).
I can't recall where I read it but I was surprised to hear that ITM are used by German based gas suppliers. In essence the German suppliers use ITM systems to mix hydrogen with natural gas for domestic use, which reduces the carbon element of the gas, and I guess overall means that less natural gas is supplied as a consequence.
It strikes me as a great way to mix the existing market for hydrocarbons, and the potential lower carbon footprint future. Whether and how profitable it is for ITM I have no idea.
The natural gas network can also be used to transport hydrogen (inject near the hydrolysis point, filter out near point of use).
On Purplebricks' profit potential it helps to look at the business with the longest track record separately (UK). The operational gearing is impressive. (disclosure I hold)
2016 turnover £18m margin GM 57%
Admin costs £9.6m
marketing £12.9m
EBIDA £-11.7m
2017 £43m turnover GM 56%
Admin costs £9.6m
Marketing £14.4m
EBITDA £0.75k
2018 forecast turnover £80m
Broker expectations on where margin and admin expenses will be for '18 show a marginal increase in admin costs and marketing whilst retaining a similar GM, with a forecast £12m EBITDA.
It therefore looks like the UK could be generating significant profits as a standalone business by April 2018.
In my view its quite uncommon to see a business increase sales YoY so dramatically without a significant increase in admin and marketing costs.
The Australian figures in the trading statement from Purplebricks (LON:PURP) caught my eye. 12m for Aus versus 80m for UK full year guidance still on track. That would seem to be mightily impressive fir Aus considering the very short time it has been running.
But can they actually make money doing this? If the marketing spend can reduce as a percent of sales the answer is probably yes. But with increased online competition in the UK and the USA market to support this reduction may be a long way off.
This is not a stock I hold. With Aus going so well I think I would hold on a while longer if I did hold these share but it looks too risky to buy in now. Need to wait longer to see how the USA goes.
Regarding Applegreen (LON:APGN) , I regularly pass, and occasionally use, three of their larger and longer established sites. They are always extremely busy. The attraction is less the fuel than the food offerings. White vans flock in for breakfast, then parties come through for the various other offerings.
The company is long established, and has recently expanded to include fuel depot and refining interests in Ireland. They now supply bulk fuel to other retailers.
As it is the price seems a little rich to me, but you cannot deny this is a growth company, with a decent niche business, and very experienced management. One to watch indeed.
ITM Power
as an engineer i just dont see the future in hydrogen, particularly for cars, you still need to have an electric engine so why not just have an elec car
I've also seen people getting behind and carried away with green technology that doesnt work, its as if whether it works or not isnt really the point. For instance if you put renewables into a newbuild property its more likely to get planning, there is no plan to maintain or use what ever green tec it is, its only there to ease the planning consent
as an engineer i just dont see the future in hydrogen, particularly for cars, you still need to have an electric engine so why not just have an elec car
Range and refueling are the main barriers to adoption for pure electric. If hydrogen refueling becomes easy, then I'll happily burn it and contribute to the over-saturated atmosphere when my battery loses charge. However, we already have a hydrocarbon infrastructure, which I suspect will be the complement of choice for many hybrids, until the battery issue is solved and hydrogen based solutions may just be too late to the party.
"For instance if you put renewables into a newbuild property its more likely to get planning, there is no plan to maintain or use what ever green tec it is, its only there to ease the planning consent "
I agree. My house built in 2011 has 2 air-source heat pumps. Very 'eco' according to marketing blurb. In reality they are very unreliable, breakdown often and cost a fortune to run.
Graham,
ITM Power (LON:ITM) announced a fund raising this morning. I believe last time you covered ITM you anticipated this , the RNS features quiet a lot of details. Could you share your view on the outlook and maybe what this means for existing shareholders?
Thanks,
Joe
Hi Joe, thanks for bringing that to my attention, I'd missed it. A very interesting announcement and I've covered it for you.
Regards
Graham
What about results from STY Styles and Wood? Is this not within cap limits?
On Purplebricks US expansion an often quoted figure is that US agents charge an exorbitant 6% leaving a fat margin ripe for attack. I'd understood though that in the US the usual practice was for the agent to deal with the whole transaction - most domestic conveyancing does not involve lawyers for example - so they do quite a bit more work than an agent in the UK would. Also any agency business is something that always looks very profitable from the outside but much worse from the inside because of all the work that goes into abortive sales.
Does anyone know what is actually included in the 6% figure - ie. what the US agents actually do for that money and whether it includes any expenses or payments out to third parties as well as the agents actual fee?
My limited experience of residential conveyancing in the UK is that people often make throw away remarks about the thousands they pay in solicitors fees whereas most of that is actually stamp duty and search fees and the bit the solicitors' firm actually gets is tiny by comparison.
Hi All,
Second vote from me re: Brighton Pier (LON:PIER). I have been long, exited, and am long again. There's the Luke Johnson connection, which may be good for some It is for me. Mr J's (passive?) "involvement" with Interquest may be a huge negative for many. Ramridge and Matylda - yes indeed thay have made good progress and regarding "where's the growth" - you are right, it may me limited as the bars side is still I think a turnaround (exiting poor performers and improving the rest) and the Pier is somewhat limited given what it is - although they seem to be active and successful in driving ideas, sales and profits from it. A successful turnaround in the bars could still be material.
They seem to be signalling that acquisitions/consolidation in experiential leisure/entertainment is where they are headed. I'll leave it to others to make what they will of that. What I can say is that the jury is (IMO) still seriously out about so called "experiences" in pubs (ping pong, "re-inventing Bingo" and the like!) - especially where fundamentally the money is still made in F & B. From a personal perspective, I run comedy and music venues (which are serious destination venues and about as experiental as you get) and we are bucking the industry blues right now. And we have found over the years that this usually happens in downturns. Our only theory is that people ringfence "affordable treats" (emphasis on the treats). I'm not saying it's easy right now but we were up a lot last year and are also up this year (vs industry LFL's generally down). Paul has correctly reflected the restaurant/pub industry woes and they are very real.
I am happy to still hold APGN, they offer a good level of product over here in Ireland (north and south)... as well as expansion further afield
Purplebricks (LON:PURP) was a real gimme short off its double top in August: lovely risk-reward at those levels. For those adverse to shorting, small short positions can be taken via Spreadbetters: Purplebricks (LON:PURP) is very liquid so spreads are tight and pice action reasonably ok (though it has been volatile). A £10 per point short on a spreabetters platform is the equivalent to a short position of just £3700 at current share price. Pauls interview with Lucien Miers was very good (I was still short at the time so it fitted my bias). If nothing else, it illustrates the level of detail shorters tend to go to in getting their homework right before taking a short position. Clearly, Paul learnt a lot about Purplebricks (LON:PURP) from Lucien who was on the opposite side of the trade.
Technically I wouldn't rule out a retrace of the price to nearer 220-240p but that might take a while. Surprisingly low declared short interest atm but one to watch especially if you are long
From a fundamental aspect Purplebricks look a pretty poor prospect: when I run it through my health check list I can't get it to score any points at all. Which rather fits with the Stockopedia ranking.
From a technical aspect, the share price has some way to go before it challenges the upward sloping 200-day moving average, currently placed at 332p. We may see some 'jam tomorrow' bulls supporting it at that level. If that moving average is breached, then I think the shorters will be keen to have another go.
Does anyone have an interest or a view of the OPG prelim results?
Highlights
* Profit after tax of £23.1 m up 24% compared with £18.6 m in FY16
* EPS of 8.43 pence per share on attributable basis up by 59% compared with FY16
* Full year dividend of 0.98p per share, including interim dividend of 0.26p already paid
* Generation up 30% to 4.4 billion units from 3.3 billion units in FY16
* Revenue up 60% to £205m from £128m in FY16
* EBITDA margin of 32% despite higher coal costs
* Net Debt £308m; gearing of 57% consistent with FY16
* 62 MW solar project construction started and on track for commissioning in FY18
As per a previous announcement, they do say (warn) that "the current year will prove to be a year of re-alignment, setting the business on its course to recover increased profitability in FY19 due to the prospective strong tariff potential and reduction in coal prices" and previously they warned that "the first quarter of FY18 has been a challenging one given the sustained high seaborne thermal coal prices that have impacted our sector as a whole. Although consensus prices for the second half of the year are expected to be lower, we anticipate a reduction in earnings for FY18 in the absence of a material reversal in the coal price"... but a current P/E of THREE seems a little absurd. I do have a couple of worries though - the income statement indicating a doubling of distribution costs (though maybe this is due to the large increase in turnover) and more than doubled finance costs considering debt has only risen 21%
Allagents had very few reviews but I have seen the negative reviews being quoted by a number of reports so I can see why Purplebricks (LON:PURP) wanted to do something about it. It would be easy for rival agents to do reviews on there, not so easy to adversely effect the review score if there were 1000s of reviews. Allagents site has been criticised before and described as controversial: https://www.estateagenttoday.co.uk/news_features/Allagents-ratings-site-set-for-major-expansion
HI Graham - I personally don't read much into the allagents issue with Purplebricks (LON:PURP). There's a lot of negativity from other estate agents towards Purplebricks (LON:PURP) and the implication was that they were using allagents to undermine them. Further, Purplebricks (LON:PURP) directs customers towards Trustpilot for reviews, so presumably the main people posting reviews on allagents might be those who go out of their way because they are very angry about the service. I.e. it's unlikely to be a representative sample. Purplebricks (LON:PURP) certainly won't be the first or last company to challenge unhelpful online reviews, especially if there are reasonable grounds for believing they are fake.
On a separate note there is a useful article here about the pressures facing their traditional UK competitors which will make it even more difficult for traditional agents to compete with Purplebricks (LON:PURP): http://www.propertyindustryeye.com/countrywide-lsl-and-foxtons-facing-26m-annual-profit-cut-from-lettings-fee-ban-analyst/ (As a reminder Purplebricks (LON:PURP) has only minor exposure to lettings).
I have written negatively about Purplebricks (LON:PURP) for quite some time now. It's interesting as quite a lot of traditional estate agents who have gotten in touch with me over it. Some of them do have relevant grievances (the fake positive reviews that get posted on Trustpilot, the business model that requires customers to pay regardless of a sale, etc.). However, I do think there is a degree of anger that this upstart is taking their business and destroying the profit pool.
The problem I have with Purplebricks (LON:PURP) is if anything, they have been too successful in destroying profits in the sector. I see their recent trading statement has reported that the cash balance is down some £6.5M. Naturally, money is being spent to get the US operation going, but even after that, it indicates to me that the UK business is barely cash flow positive at all.
Indeed PURP will sink all ships. Which it entirely misses in its own marketing missives, sorry AGM statement. For example the US is a $70 billion opportunity at current prices, but only $35 billion if prices half. Then take into account negative gearing because PURP is not really taking much cost out, especially in the US where realtors work from home anyway. Estate Agents are probably the only thing propping up off prime retail rents right now. I would expect them to downsize, pay less rent, and make less profit. So less profit all round - which is a good thing for customers, but does not make PURP anything but a short at this SP.
"I do think there is a degree of anger that this upstart is taking their business and destroying the profit pool. "
You bet! Hence the need for PURP to defend itself. This is an entire industry under threat that has been ripping of customers for years- any wonder they don't like it?
Up front fees ensure commited sellers and an efficient model. It bring joy to my heart as I drive around seeing ever increasing numbers of SOLD signs on Purplebricks boards. ;-)
For me, the whole Purplebricks reviews debate hinges on whether they are objecting to real negative reviews or fake ones.
Traditional estate agents would certainly have an incentive to try & talk down Purplebricks, due to the threat to their model. So there could be an abnormal number of fake reviews.
I suppose it all depends on how honest the traditional estate agents are. From experience, SOME of them are highly dishonest, so I would suggest they are very capable of writing fake reviews. Whether that happens is another matter.
In the case of sites like Trip Advisor, it's much easier to distinguish good from fake reviews, as, for example, real people may stay at multiple hotels & review lots of them. Fake reviewers create a profile & write one review with 5 stars for everything. Few people will sell multiple properties.
Perhaps talking to real customers might be a better way to evaluate Purplebricks customer satisfaction.
I took profits on Purplebricks months ago. I don't see how all the US property portals would sit back & allow Purplebricks to grow there without competition.
There's major restructuring under way at Digital Barriers (LON:DGB) it seems. The market has responded positively.
Couldn't possibly get any worse. Could it? Never seen such an ongoing destruction of shareholder value by fat cat management living off big reputations. Shame the 80 % shareholding institutions didn't sack them.
Totally agree with the comment "Companies should be able to take criticism" - tangentially... I have seen some shocking and quite arrogant responses on Tripadvisor to customers giving less than perfect reviews of their restaurants, which I find very off-putting.
Good write up Graham, thank you. I'd be interested on your views about the purported offer for Redstoneconnect (LON:REDS) if you have a moment.
Could I second the request for comment on the REDS 'offer'...
Hi, it looks like a worthless piece of news to me since the directors have rejected the claim that they have even been approached, the AP Systems website is not professional enough to make it look like it could seriously bid for Redstoneconnect (LON:REDS), and the company accounts specifically for AP Systems Holdings Limited show that it was dormant until December 2016 and only has paid-up capital of £10k.
Thanks Graham. I don't really understand AP's motives unless its purely attention seeking - does this happen often?
Yes, it happens from time to time in my experience.
Cheers
Ah commisery! The misery you feel when someone makes a nasty comment about you.
Great pun.
Thanks Graham,
I have always invested long only, for my retirement, but if I could short, then Purplebricks (LON:PURP) would head the list and IQE (LON:IQE) would follow, in second place
Hi Graham - wonder if you could have a look at Brighton Pier (LON:PIER) . Its full year results look really good with respect to all metrics. Also beating broker forecasts from what I can tell.
Thanks, Ram
Ramridge - I quite like the look of Brighton Pier - I think the main thing stopping me here - Is where can real growth come from and why are shares in issue rising 30% YoY - Graham's more experienced view would be welcomed here too.
Hi matylda and frederigtug - Re. Brighton Pier (LON:PIER) matylda - you are raising good questions.
The one about the number of shares is indeed puzzling. Today's report says
FY 2017 total diluted weighted average no. of shares in issue = 33.2m, and the number for FY 2016 was 18.8m. .
That's a huge 77% increase in issued shares from from one year to the next.
And yet there is no apparent explanation in the accounts for this rise. No usual suspects such as share options for management. etc.
As far as the business side is concerned, to me this is a play on Luke Johnson. Buy the shares if you believe he can turn round the bars division and the Brighton Pier side and deliver sustained profitable growth. He has a 28% stake in this company. Today's report shows a big step in that direction IMO.
This is the explanation for the extra shares=
Brighton Pier (LON:PIER) from RNS dated April 26, 2016
Eclectic Bar Group plc is pleased to announce that at its General Meeting today, held in connection with the Placing, the acquisition of The Brighton Marine Palace and Pier Company and the proposed change of name (the "Proposals"), as announced on 8 April 2016, all Resolutions were duly passed.
Accordingly, the Acquisition and Placing are expected to complete tomorrow, 27 April 2016, and the Company's name will change to The Brighton Pier Group PLC (the "Enlarged Group") and the Company's TIDM will change to 'PIER'.
The 15,454,546 New Ordinary Shares have been allotted and issued pursuant to the Placing, credited as fully paid, and will be identical to and rank pari passu in all respects with the Existing Ordinary Shares.
The number of Ordinary Shares in issue and the total voting rights in the Enlarged Group following Admission will be 31,677,287.
Hi laurie - excellent. That explains it perfectly.
Hi Ram, covered it for you.
Cheers, Graham
Hi Graham Brighton Pier (LON:PIER) many thanks for covering it. You are showing a few facets of this business that I hadn't considered.
Even with LJ at the helm, is this the right sector to be in right now? I tend to agree with you, probably not.
Thanks Graham - Much appreciated