Small Cap Value Report (Mon 24 Aug 2020) - UPGS, CLG, STU, MOTR

Good morning! It's Paul here with the SCVR for Monday.
Today's report is now finished.
It's very quiet for small caps results/trading updates today. I've got family visiting, so want to get this week's reports out of the way by lunchtime at the latest, hence would prefer no reader requests this week, if possible!
Here's today's agenda;
Up Global Sourcing Holdings (LON:UPGS) - repaying Govt funds
Clipper Logistics (LON:CLG) - results FY 04/2020
Studio Retail (LON:STU) - results 52 weeks ended 27 March 2020
Motorpoint (LON:MOTR) - trading update
.
Up Global Sourcing Holdings (LON:UPGS)
As covered here previously, this product sourcing company has traded well throughout the covid crisis. I last covered it here on 6 July 2020, being impressed with its update.
Today it announces;
Return of Government furlough funds
An unusual announcement today;
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces that it has taken the decision to repay the £465,237 that it has received under the Coronavirus Job Retention Scheme ('furlough scheme') and does not intend to make any further claims under the furlough scheme or for the associated Job Retention Bonus.
The Group is also no longer utilising the Government Time to Pay and VAT deferral schemes. All VAT and PAYE payments are up to date as at 31 July 2020.
These payments are possible because the Group's profitability and cash generation have been stronger than expected during this crisis....
... Returning this money to the taxpayer is therefore the right and proper thing for us to do.
.
I salute their sentiments, but do wonder if there's more to it than that? I've not looked into the finer detail of Govt support schemes, so am wondering if any readers know whether companies have to demonstrate that covid/lockdown has caused them financial hardship, in order to be eligible for these schemes? Particularly for a listed company, if they're putting out positive trading updates, then I would hope HMRC would push back against any requests for deferral of taxes.
Separately, but on the same topic, there are articles in today's papers saying that research from Oxford, Cambridge, and Zurich Universities suggests that a staggering 6 million people continued to work (an average of 15 hours per week) whilst on furlough. That's about two thirds of people funded by the taxpayer scheme, which was meant to prohibit working whilst on the scheme, until amended later on, to allow some work.
I've no idea whether this could be a factor in companies returning furlough monies, but it would be very easy for HMRC to ask to see email records, and then demonstrate that people were working, when they shouldn't have been. It does seem crazy having a Govt scheme that actively tries to make people idle, but I understand the reasons it was brought in as a temporary way to prevent unemployment. The unintended consequences seem to have been problematic though.
Maybe we'll see more companies return furlough monies? A friend's small business received a Govt grant, and is not sure if they are entitled to it. They're having a huge internal row about whether to give the money back or not, and asked my opinion. I said that, in their position, I would segregate the money into a separate bank account, then write to the body that awarded the grant, asking for written confirmation that the recipient is entitled to keep the money, describing the business, its activities, and any other relevant facts & figures.
.
Clarification re Up Global Sourcing Holdings (LON:UPGS)
An adviser to UPGS contacted me, to say that the company was very upset about the above commentary. I reported on UPGS's RNS stating that they have decided to return the Govt furlough monies. In the same section, I reported on another item on my agenda, an article in the Telegraph about research saying that furloughed staff had widely been working from home, part time, in the UK generally, during April & May.
On reflection, I shouldn't have put these two items together, in the same section, as that led UPGS to misunderstand, and think I was linking the issues, or implying wrongdoing on their part. That certainly wasn't my intention, at the time it just seemed to make sense to put the one subject in a single section. I thought my use of the word "Separately...." made it clear that I wasn't linking UPGS to the Telegraph article.
On reflection, this was a mistake on my part, and I can understand their point of view, so am happy to give an unreserved apology for any offence caused. If I'm wrong, am happy to admit it, and apologise, so this has not been forced out of me, it's a genuine apology from me, as I can see why UPGS took offence, even though it was unintentional on my part. As stated above, UPGS has traded strongly, and I have been very impressed with its resilience & financial performance throughout covid.
UPGS is adamant that it's returning the furlough monies because this is the right thing to do, and out of a sense of civic responsibility, so I am happy to pass that message on to readers here.
Clipper Logistics (LON:CLG)
Share price: 392p (up 6% at 09:52)
No. shares: 101.7m
Market cap: £398.7m
One of the increasingly popular PR summaries has been added at the top of this announcement:
An excellent year leading to record results; strong momentum throughout COVID-19
I can't decide whether I like those summary comments or not! On balance, they're probably useful for companies which have a track record of telling it how it is, and best ignored for rampy/speculative companies.
Clipper Logistics plc ... a leading provider of value-added logistics solutions, e-fulfilment and returns management services, is pleased to announce its Full Year Results for the year ended 30 April 2020.
EPS is up 20.5% to 15.9p - a good result, but that gives us a hefty PER of 24.7
Adjusted EPS is disclosed further down, and is more relevant as it removes amortisation of intangibles and is a bit higher at 16.6p (up 16.9% vs LY), a PER of 23.6
Dividends total 9.7p for the year (flat vs LY) for a yield of 2.5%
Current trading is strong;
... the Group has experienced a very positive start to the new financial year, with exceptionally high levels of demand for its e-fulfilment and returns management services in particular.
Consequently, the Board anticipates that the Group's results for the year ending 30 April 2021 will comfortably exceed market expectations.
It's a pity they forgot to include a footnote to tell us what market expectations are, which is best practice, and is being increasingly disclosed by many companies.
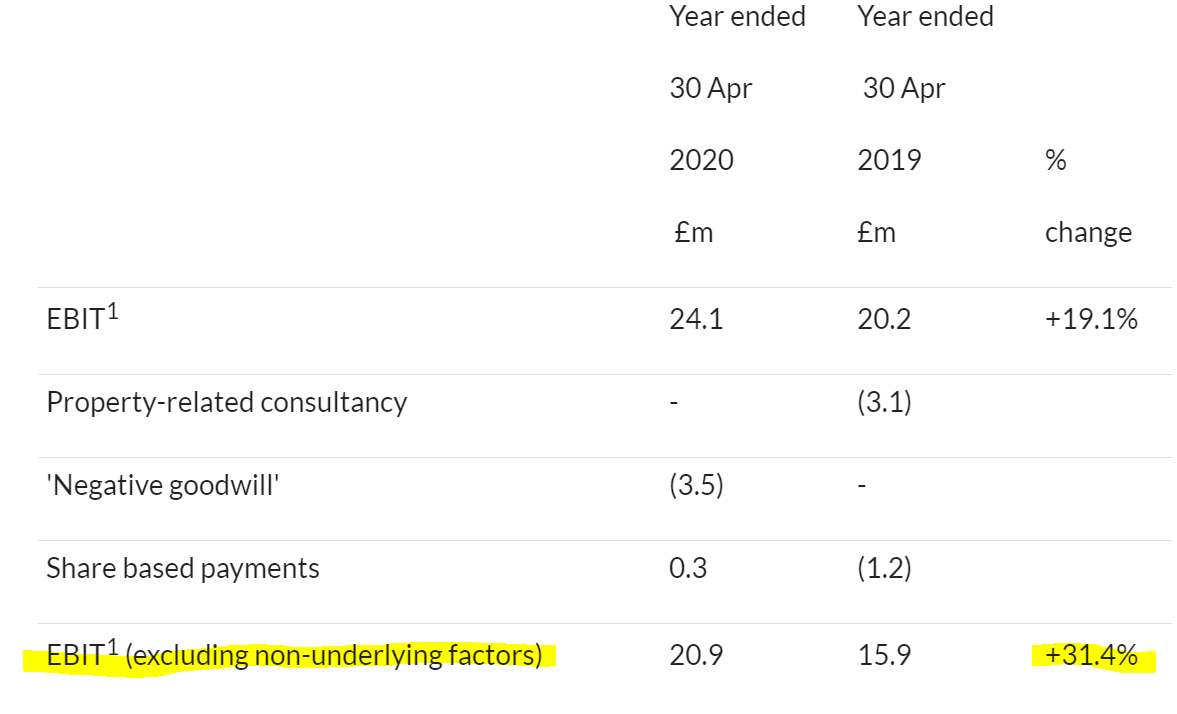
A table shows non-underlying items. I've highlighted the figures that seem to best reflect underlying trading;
.
.
Commercial vehicles division - I've not noticed this before, but Clipper owns 5 commercial vehicle dealerships, which generated £82.5m revenues (flat vs LY) and £2.0m of EBIT. Hence this division probably needs to be removed from the figures if you want to focus on the main logistics business only.
Finance costs - have shot up from £2.2m LY, to £11.2m this time. That's almost certainly due to the distortions created by IFRS 16. Let's have a look at note 8. Yes, that's the culprit, a new finance charge of £8.0m has appeared (obviously nil LY before IFRS 16). This is a massive distortion of the numbers, and now makes operating profit meaningless, because it excludes rental costs that are now shown within finance charges. What a mess IFRS 16 has made of company accounts, I despair.
This is why I tend to focus on EPS, because that should take into account everything.
Balance sheet - hugely distorted by large IFRS 16 entries.
NAV: £29.3m, less intangibles of £65.9m, gives NTAV is negative, at £(36.6m).
That's a weak balance sheet, but as we've seen with another logistics company, Wincanton (LON:WIN) , companies in this sector seem to be able to operate fine with negative net assets. It seems to be due to a favourable working capital business model - i.e. getting money up-front from customers, before creditors have to be paid.
I'm not keen on that type of thing, and prefer balance sheets to be at least positive in NTAV. Hence my personal preference would be for CLG to hold back dividends, and instead allow cashflows to gradually strengthen its balance sheet.
That said, CLG seems to have sailed through the covid crisis, hence is now battle proven in a crisis. Therefore a weak balance sheet isn't necessarily a deal-breaker for me - balance sheets need to be viewed in conjunction with other factors, such as cyclicality, quality of earnings, etc.
Cashflow statement - is just gibberish, due to the huge IFRS 16 entries, which obscure the real cashflows.
Ignoring all that, the profit seems to have been spent on (in descending size order): paying dividends, capex, and a small acquisition.
My opinion - good results, and a strong current trading update.
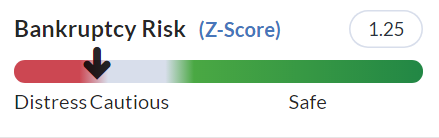
Balance sheet is weak, but that probably doesn't matter. This is confirmed by a borderline Z-Score;
Highish valuation seems justified due to growth.
It makes complete sense for retailers * eCommerce companies in particular to outsource their logistics. It's frequently an area that gets messed up internally (e.g. Joules (LON:JOUL) distribution fell apart last Christmas), and often consumes a high level of management time & anxiety. Therefore outsourcing it to experts makes complete sense. Clipper has an impressive client list, which seems to have low churn, so revenues are strongly repeating in nature, and rising for the eCommerce clients.
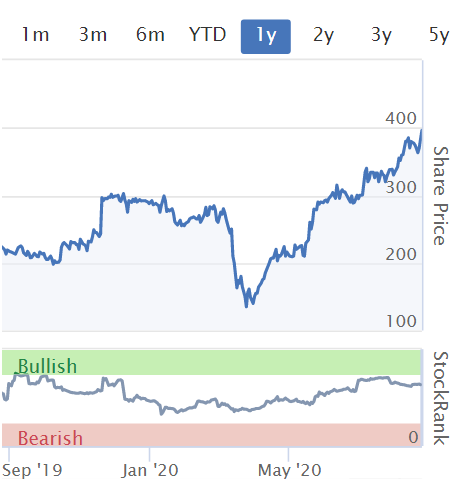
Overall, I like it, and think this could be a good long-term investment, although personally I wouldn't pay the current price, which looks up with events. Amazing recovery in share price, from the March lows, but it looks justified based on good trading;
.
.
Motorpoint (LON:MOTR)
Share price: 278p (up 2.6%)
No. shares: 90.2m
Market cap: £250.8m
This is a secondhand car supermarket chain.
Motorpoint Group PLC, the UK's leading independent omni-channel vehicle retailer, today provides an update on trading for the 20 weeks to 21st August 2020
The CFO for 5 years, James Gilmour, has suddenly resigned, as he was due to be re-elected at today's AGM. That's a concern.
Trading update -
"Over the last 11 weeks, the period which the Group's retail sites have been fully reopened, the Board has seen its key operational and trading metrics comfortably ahead of the equivalent period last year.
...Supply of stock and margin remains strong.
No figures. So what does "comfortably ahead" mean? That's not good enough, investors need figures, to be able to measure & compare performance. Other car dealers have reported good trading in Iune & July, as pent-up demand was unleashed. Most have given us reams of detail, facts & figures, so Motorpoint's update today stands out for how little it tells us.
Outlook - too early to give guidance. We have to wait until 8 Oct 2020 for a proper update on the half year performance.
My opinion - that was a waste of everyone's time, it tells us virtually nothing.
.
Studio Retail (LON:STU)
Share price: 239p (down c.4% today)
No. shares: 86.4m
Market cap: £206.5m
SRG, the online value retail and Education business, today announces its full year results for the 52-week period ended 27 March 2020.
This share used to be called Findel. I've started looking through these numbers, and wish I hadn't! It's more complicated than I thought, because it seems to be a bit like N Brown (LON:BWNG) in that it sells products online, but makes its money from offering credit.
There's a disposal pending (awaiting clearance from CMO - seems to be taking a long time, as sale agreed in Dec 2019, for £50m - significant in comparison with the market cap of £206.5m
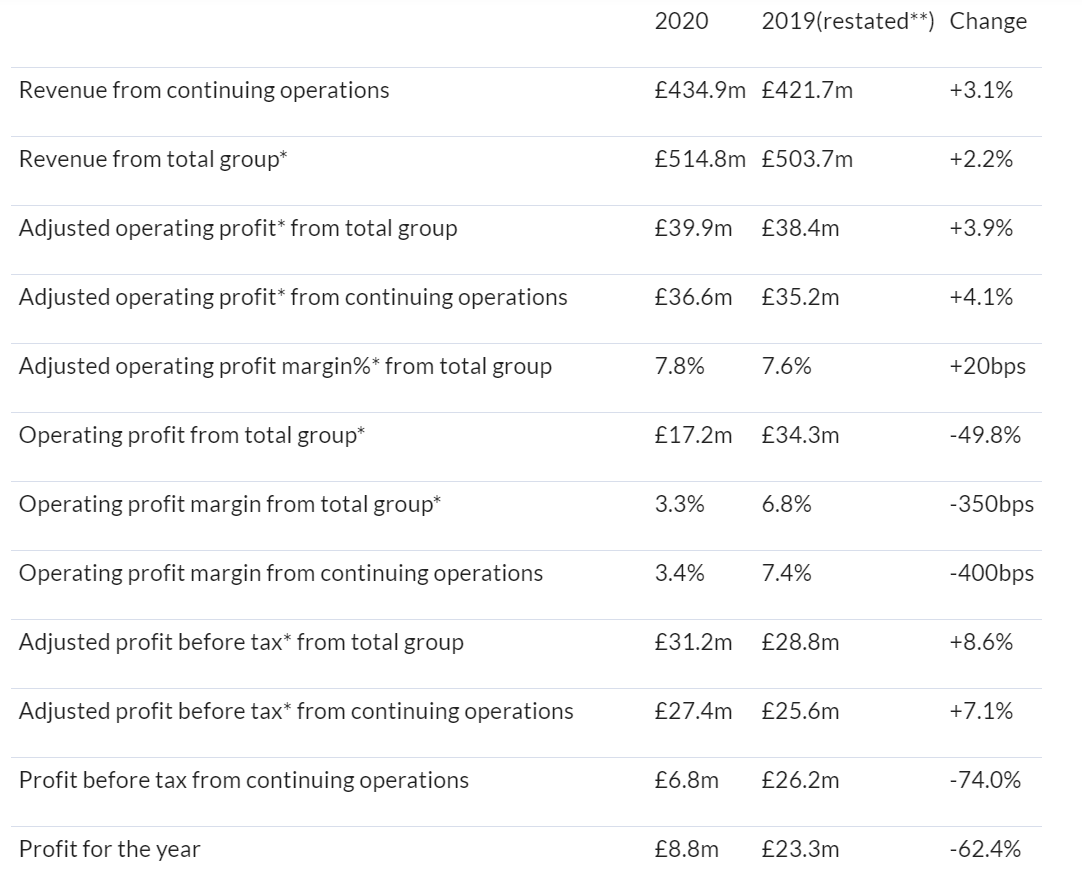
So the continuing operations figures are the most relevant to the future - revenues of £434.9m (up 3.1%)
The financial highlights gives us a bewildering array of options for how to measure profitability;
.
.
Adjustments - I usually check, and accept adjustments made to company accounts, because they're usually bona fide one-offs, or non-cash things like goodwill amortisation. In this case however, I want to flag, and put a question mark next to the £20m adjustment called "Estimated COVID-19 bad debt impact", a cost which has been removed from the adjusted profit, thus substantially increasing it that measure of profit.
Pensions - see this section in the RNS for more detail, the numbers look significant.
Balance sheet - a huge receivables book, funded with long-term debt. I think it's high cost credit offered to customers, with all the regulatory risk that brings with it.
Outlook - very strong trading during lockdown, but this is expected to reduce back to normal in the future. Too early to give guidance.
My opinion - it just doesn't interest me at all.
Dividends seemed to stop in 2009, with nothing paid since. That doesn't suggest to me that this is a decent, cash generative business.
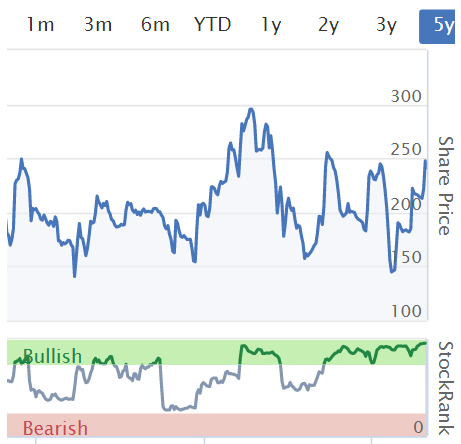
The shares have zig-zagged sideways for the last 5 years. What's going to change?
.
.
That's it for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Hi Michael Tee,
.."If they have the reserves, they don't need tax-payers money. Others need it more..."
I don't see how company A can establish whether it's 'more deserving' or not than company B.
The civil servants have had to draft in haste regulations covering an enormous range of scenarios and one COULD argue that directors have a fiduciary duty to do what's best for their 'stakeholders', just as it's everyone's right to reduce their (own) tax bill to the minimum.
My nephew works for a FTSE 100 company and the external caterers have been happy to avail themselves of the Eat Out to Help Out offer, improving their (and THEIR stakeholders') trading prospects.
In the context of a £ 100+ BN trickledown project like HS2, I'm not sure the current stimulus issues (more drone than helicopter money) are worth getting too exercised about !
ATB
..
I should add, a business can still perform well (and generate distributable reserves) while also evidencing that it has been affected by Coronavirus. There is no restriction on dividends as a result of the use of government schemes from my knowledge. If anyone has a government source to the contrary it would be good to post here for us to take a look
UPGS:
Paul,
I read your comment about the repayment of furlough payments.
I think this is all about the difficulty in paying dividends if a company has accepted furlough payments. The directors have large shareholdings and will want to receive dividend payments. Without repaying furlough payments, paying a dividend is controversial.
It is obvs positive if they do not need the funds.
Michael
My understanding is that although a number of companies state they are repaying government Covid support "in the public interest", their main motivation is to avoid restrictions on dividends and executive bonuses. I am not an expert on the individual schemes but I believe that some contain explicit prohibitions and that there is a "read across" from those to the other schemes (which were introduced earlier) which don't have the explicit conditions but might be expected to have them implicitly (you can see the newspaper headlines - massive director bonuses paid to company X which claimed government covid support!).
I am sure that HMRC will be reviewing email traffic during the furlough period as part of their routine PAYE audits over the next 6 years.
Hi Michael,
I’d like to politely disagree with this, if I may.
In my opinion, a company should be able to pay Dividends out of reserves already generated prior to Coronavirus. It can still be affected, claim furlough support for temporary/current disruption while paying dividends out of retained earnings. No issue there in my view. It’s different, at least morally and also from HMRCs point of view, if the reserves created in order to pay the dividends were entirely as a result of furlough, though!
Hi James
Just to clarify,my post deals with what I understand to be the reality rather than what I view as the ideal position.
Details of some of the restrictions can be found at:
https://www.gov.uk/guidance/apply-for-the-coronavirus-large-business-interruption-loan-scheme
see the end of the Eligibility section just before the Who cannot apply section
Thanks Steve - I wasn’t aware the CBILS restriction until now, I am only very familiar with everything other than CBILs so my bad!
This is not about reserves and all about perception.
Paying dividends having accepted (bailout) money from the government looks bad.
If they have the reserves, they don't need tax-payers money. Others need it more.
We’ll agree to disagree Michael. The schemes are there to support business affected by the virus, not for those only in dire straits prior to the virus with zero reserves.
"My opinion - that was a waste of everyone's time, it tells us virtually nothing."
Paul,
Great comment (as ever!). I just wish there was a way to automatically send your commentary & analysis on company RNS to their CFO/CEO/PR teams each day.
Hi Zipmanpeter,
A lot of companies & PRs do read these articles, as I get typically about 1-2 complaints every week!
Regards, Paul.
W.r.t H & T (LON:HAT), if holders have not realized why the SP has fallen so much despite Simon Thompson's favourable review last week and a relatively reasonable recent update, it's because Artemis has reduced their holding leading to a big dump of shares in the market :(
Have been considering buying more but given its in my top 5 already I have stopped at the moment but is clearly undervalued by a considerable amount. Its never going to multi-bag but when the results over the next 12-18 months come in with the added stores it will re-rate.
An expensive haircut for me and others too I'm sure. The market is a power game. Lesson learned.
Does anyone know if there has been something leaked on the Creightons (LON:CRL) results due Wednesday or does todays move signal the speculative buys have started hoping that there will be a big swing (up I hope) on the release?
Thanks Tommy
I hold
Yes interesting price action today. I think this might just be in anticipation - I seem to remember there was a similar move in the run up to results last time too.
I sold out of Creightons (LON:CRL) recently as similar beauty product companies have had falls in retail sales during the pandemic and there's been a bit of optimism around Creighton's hand sanitiser which may be misplaced given how many other companies are now making hand sanitiser. I also thought this sentence in their most recent update in July hinted at a possible profit warning:
Despite pivoting the business with speed, the competitive environment and demands on the supply chain have nevertheless been, and continue to be, challenging. The Company will continue to find the positives where possible to keep moving forward.
Thank you Patrick I might need to think about book the profit and move on as I had seen a similar gloomy report from L'Oréal and come back again later in the year
Genuine question if your portfolio companies sales are generated 70% (Mine was though I am not sure it is now, it is not a metric I check) overseas is the portfolio geographically diverse and there is no need to invest in overseas listed companies/funds or is diverse sale not the same thing?
That depends on investor psychology. If people get (more) downbeat on the U.K. and start bailing out then most stocks are correlated to some extent even when they aren’t directly affected by passive index fund selling.
I remember a few years back when Chevron and Total were very similar businesses but Total had half the market cap because everyone was down on French shares.
Share prices could be certainly marked down by international sentiment, but if your timescale is long enough that what you care about is earnings, then I don't think there is a problem with your 'diversity'. If £ declines, they should sell more, retain more AV in £ or be able to translate overseas earnings into more £. And plenty of UK stocks have overseas subsidiaries anyway.
But a UK pharmaceutical is likely to continue to be valued somewhat lower than a US one because overseas investors think only the US is the stepping stone to eternal growth. :(
Re Brexit/Macro picture - I'm holding a lot of cash still(>30%). Over 6 months the erosion in value will be negligible vs the safety it brings although I am of the "inflation is coming" school" in the long term.
(I already see price increases in basic supermarket goods (including from range reductions and eliminations of promo offers) and all this money printing has to come out somewhere. "Good time Boris" will not want to return austerity or raise taxes; creating inflation is a long term and insidious but politically easy way of reducing the real value of govt debt.)
Anyway, I feel there is a good chance of another big spike down (up to 20%?) before next say Feb 21 by when Brexit's initial impact will finally start to be clear - especially as mentioned by others the US is another potential wildcard in 2020 : What if Biden or Trump gets Coronavirus 10days before election! or Trump takes a wild swing on US trade, foreign or domestic policy if losing. Not hard to imagine triggers - Taiwan, Portland, Tech crash ).
I normally much prefer to be fully invested and wait out ups/downs in firms/ opportunities I believe in, even over a period of years, but after a dreadful 2019 I have to admit to being gunshy. Loss aversion is probably going to drive another bout of under-performance !
If you are such a firm believer in rising inflation, why are you not holding gold instead of cash?
and finally, my back of the envelope look at house builders.
The starting point was Persimmon (LON:PSN) has shown a clean pair of heels to the sector. What should we make of this? It has best returns, best margins, best balance sheet and highest valuation. In a bull market best best best does not always equal best share price. Looking at reporting periods Persimmon (LON:PSN) an Taylor Wimpey (LON:TW.) both report to 31 December. Bellway (LON:BWY), Redrow (LON:RDW) and Barratt Developments (LON:BDEV) have June or July for Bellway. To make an accurate results comparison we must pull the half years apart. Looking at ROA Persimmon leads the pack at 20 and Barrat are last at 9. Bellway (LON:BWY) is very solid at 15% and trades at book value. So of the pack of chasers it looks to me as though Bellway (LON:BWY) is least controversial. Although Barratt Developments (LON:BDEV) has a better balance sheet, they consistently have lower margins and returns. Like I said before however, a rising tide catches all boats eventually.
I have Berkeley Group (LON:BKG) which has announced it is returning £208m to investors this year via dividends and buy backs and Mj Gleeson (LON:GLE) whose model of building starter homes I like. Another way to play housebuiqdelrs is Ibstock (LON:IBST) which looks cheap to me.
Berkeley Group (LON:BKG) looks good but the shares have already done quite well. They sit between Persimmon (LON:PSN) and the pack. They have decent returns, decent balance sheet but because of London can be volatile. Im a little surprised London hasn't held them back more.... I did also look at Springfield Properties (LON:SPR) but they have low returns, margins and decent gearing. This does add up to stronger growth as you would expect but are therefore highest risk in a Covid world.
I think Berkeley Group (LON:BKG) is a 'proper' company if you get my drift!. Well managed, good shareholder returns, not involved in building large blocks of flats with cladding problems. But what Mj Gleeson (LON:GLE)? I really thought it would be doing much better. What I dont like about is the level of executive remuneration.
Having held Barratt Developments (LON:BDEV) and still holding onto Vistry (LON:VTY) and initially scratching my head as to why when Barratt Developments (LON:BDEV) falls 5%, Vistry (LON:VTY) would fall approx. 2x more than Barratt Developments (LON:BDEV) (i.e. £like for like, Barratt Developments (LON:BDEV) , much more resilient)
On the other hand, when there's good housebuilders' news and Barratt Developments (LON:BDEV) increases say 5%, Vistry (LON:VTY) increases at a similarly level.
Having seen the wide discrepancy, for the future, should I wish for exposure to a certain sector, I strongly recommend comparing the "beta" as well.
When things are all buoyant, beta is perhaps neglected but it should be a key factor in bear markets when seeking exposure to a certain sector.
Vistry (LON:VTY) has same year end as Persimmon (LON:PSN), 31 Dec. It has quite low returns compared to the pack and some debt on the balance sheet. The numbers probably take some time to settle down but interestingly current 2021 forecasts look similar to 2019. Maybe this explains things, its cheap so looks attractive if all ok but given low returns and gearing, risky when heading South. There is your Beta. If covid doesn't spike again and the integration remains on track then its interesting. from memory Bovis always had a lot of land tied up in a couple of v large sites which is always a bit more risky.
#ThinkingAloud #IsItAllowed i do think that Clipper Logistics (LON:CLG) results reinforce a turning point for the high street, catalysed by covid, as alluded to by Paul and others.. foolishly dumped a load on a minervini style 7.5% drop on a run from march lows, but recently back in. Anyway, what has always concerned me is the working capital level and the lease commitment related debt now on the BS.
Interesting that PLT have been mentioned as a major client but never BOO (that announcement if it ever comes would be more than positive), and hidden in todays announcement, unless i imagined it, is confirmation of the Arcadia contract. Reassuring that Parkin and LION both heavily invested. Boring business, low margin, works on volume... must have some really impressive automation tech under the hood (i wonder how their logistics operation compares with stalwart AMZN in the UK
I know Clipper well (a former customer of theirs in a couple of roles). They have some highly automated sites, often done in partnership with and unwritten by their customers, but also a lot that are reassuringly capital unintensive and flexible (i.e. operated with people!). The margins are not great, so they thrive on economies of scale, operational competence and a good culture. They have also been very good at maximising each and every property deal they make, sweating the asset very hard.
In Macro corner, frankly its a little dull. The seismic shift in yields a couple of weeks ago from lows 50's bps to 64, has not lead to much change. The Dollar's fall has been arrested and it has recovered a little. Copper strength has stalled but remains positive and Gold, similar but down this week. Oil was flat. Not much to say really, except for Tesla, which following an announced stock split after UK trading hours a couple of weeks ago has risen a pretty staggering 49%. Stunning for a small cap going into the FTSE250 ! but Tesla is a top 10 global mkt cap. Seemingly making a mockery of decades of financial training and education. I do read a lot about what an amazing short it will be, although mathematically a short always yields the same potential return. So it is not really possible to be a better short just because the market cap is higher. Anyway the value basket was down 8% before the spike in BT today, which is 5% behind the All share index and looks ridiculous compared to Teslas 32% rise. Despite the macro picture turning ever so slightly in their favour.
I like the look of Ixico (LON:IXI) here. In a great sector, AI healthcare research, with multi year tailwinds and a natural moat that comes from the information the company has already analysed. Good trading update and well under most investors radar.
Interesting co. espeically when you consider the aging population and the greater emphasis on mental health at the moment.
I hold £ixi, their "moat" is in imaging of Alzheimers', PSP and Huntingdon disease. From their previous presentations, the founding professors are linked to UK's leading uni's , i.e. King's, and Imperial. I would imagine, this allows £ixi to get the latest research. Company is super cash rich with circa £6mn cash with no debt.
My morning smallcap tweet: LID lift
Tiziana Life Sciences (LON:TILS) Safestay (LON:SSTY) Venture Life (LON:VLG) £7DIG Lidco (LON:LID) Prime People (LON:PRP) IXICO (LON:IXI) Amigo Holdings (LON:AMGO) Motorpoint (LON:MOTR) Coral Products (LON:CRU) Clipper Logistics (LON:CLG)
Tiziana Life Sciences (TILS) gets US patent for methods and use of a fully human monoclonal antibody that may be able to treat cytokine storms eg in covid. [SP=150 Cap=286m]
Safestay (SSTY) further cost cutting due to tourism hit by "perceived likelihood of a second wave". Modelled two cases: base case that all hostels re-open by Oct; low case where all but London Kensington Holland Park and Barcelona Gothicopen by Oct but with lower occupancy. Under both cases co reaches b/e occupancy level from March 2021. Trading: in July 30 per cent. of the Group's bed stock was available and 16 per cent. of such bed stock was occupied. Discussing covenants with bank, may sell some hostels, raise equity. [SP=13.4 Cap=9m]
Venture Life (VLG) CPC mouthwashes including co's Dentyl brand to be used in a trial to investigate the possibility that using over-the-counter mouthwashes reduces covid infections. [SP=86.9 Cap=73m]
7digital (7DIG) one year contract for co's platform to host jazzed - the world's first dedicated audio-visual streaming service for jazz and jazz-influenced music - to launch globally in new territories. [SP=3.13 Cap=77m]
LiDCO (LID) guides H1 rev up 75%, due to increased demand for advanced hemodynamic monitors in covid cases. [SP=7.55 Cap=19m]
Prime People (PRP) delays FY result to lat Oct. [SP=42.9 Cap=5m]
IXICO (IXI) guides FY(Sep) rev in line with, or slightly ahead, EBITDA materially ahead of market expectations. [SP=69.5 Cap=33m]
Amigo (AMGO) comments of blog of ousted founder James Benamor on proposals for AMGO. Fight! [SP=17.82 Cap=85m]
Motorpoint (MOTR) CFO scarpers. He is thanked. Trading encouraging but no guidance. [SP=271 Cap=244m]
Coral Products (CRU) Q1 rev down 24% but U/L EBITDA up 5%. Confident cash flow will further improve if no covid 2nd wave. [SP=4.88 Cap=4m]
Clipper Logistics (CLG) FY(Apr) as guided. Maintains div. Guides FY21 comfortably ahead of market expectations. [SP=370 Cap=376m]
Decent HY results from Kenmare Resources (LON:KMR) last week. Hear more about the progress and put any questions to management at our webinar this evening. Register here
Fund This Project
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Adjusted profit before income tax* up 16.6% at constant exchange rates to £306.8 million. Operating margin* 7.0%, up 30 basis points on a reported basis and 40 basis points at constant exchange rates.
Return on average operating capital* and return on invested capital* increased to 39.7% and 14.4% respectively. Continued strong cash conversion* of 112% with net debt to EBITDA only 1.6x (1.9x at end of 2019).
27 year track record of dividend growth continues with the reinstatement of the 2019 final dividend of 35.8p per share as an additional interim dividend for 2019 and interim dividend for 2020 up 1.9% to 15.8p per share.
Pubs and restaurants have been paying VAT on food sales of 20% and supermarkets zero.. This tax differential has created an increasing gap between on-trade and off-trade pricing, as VAT rates increased from 8% 40 years ago to 20% today..
The Chancellor, Rishi Sunak, has recently closed the VAT gap between the on and off-trade, by temporarily reducing VAT on food sales in the on-trade to 5%.. Question:
We were told it was 3% initially, initially 2%, are you saying now that it's 0.1%., that's pretty much the same fatality rate as the regular flu isn't it?.
The emergency rooms here in Stockholm have about 50% of the usual number of patients coming in, and one reason is probably that people are scared of contracting the disease when they go into hospitals, and another is that, I think, they say they can wait a bit until the thing is over..
Frasers Group announces the acquisition of certain of the assets of Dave Whelan Sports Limited ("DW") from the administrators of DW for an initial cash consideration of £37 million (the "Transaction")..
Pursuant to the Transaction, the Company has acquired certain of the assets relating to DW's gym and fitness business, including certain stock but excluding the DW business names and IP.
Additional consideration (up to a maximum of £6,900,000) may be payable contingent upon the number of leasehold interests eventually acquired. For the year ended 31 March 2019 (the last date to which statutory accounts are available for DW and prior to the appointment of the administrators),
DW had gross assets of £194,976,000 and made a loss of £20,085,000.. The Transaction compliments the existing gym and fitness club portfolio within the Company's group and is consistent with the group's elevation strategy.
Basic earnings per share were 15.9 pence (2019: 13.2 pence), an increase of 20.5%..
Group revenue increased by 8.8% to 500.7 million for the year ended 30 April 2020 (2019: £460.2 million),
Group EBIT (IAS 17 basis)1 was £24.1 million (2019: £20.2 million), growth of 19.1%.
Diluted earnings per share were 15.8 pence for the year ended 30 April 2020 (2019: 13.1 pence), an increase of 20.6%.
Basic earnings per share were 15.9 pence (2019: 13.2 pence), an increase of 20.5%.
Group EBIT1 for the year was £24.1 million compared to £20.2 million in the prior year, an increase of 19.1%..
Revenue growth was very strong in e-fulfilment & returns management services, where revenue of £277.0 million was 18.4% ahead of the previous year.
Non e-fulfilment revenues marginally declined by 1.0% to £143.8 million, whilst revenue from commercial vehicles remained flat year-on-year.
Value-added logistics services increased by 18.4% to £24.9 million and the commercial vehicles segment increased by 72.6
Total group revenue* of £514.8m, up 2.2% (FY19 restated**: £503.7m). ·
Revenue from continuing operations of £434.9m, up 3.1% (FY19 restated**: £421.7m). ·
Adjusted operating profit* for the total group measured on a constant-GAAP basis up by 3.9% to £39.9m. ·
Operating profit from continuing operations was down by 52.7% to £14.7m, largely as a result of the £20m estimated impact of COVID-19 on the bad debt charge and the adoption of IFRS 16. ·
Adjusted profit before tax* for the total group measured on a constant-GAAP basis up by 8.6% to £31.2m.
Studio, our online value retail business, reported revenue of £434.9m, up 3.1% (FY19 restated**: £421.7m).
Product revenue of £311.7m (FY19 restated**: £304.2m), growth of 2.5%, with a strong performance during its peak trading period offset by a less consistent performance at other times.
Competitive market conditions and a disappointing retail trading performance during Q4 resulted in product margins reducing slightly to 33.0%
Further, the Board anticipates that earnings before interest, tax, depreciation, and amortisation (EBITDA) will be materially ahead of current market expectations..
Record first half performance with LiDCO product revenue up by 83%.
In H1, total revenues (including third party products) increased by 75% to £6.2m (2019: £3.5m) with LiDCO product revenues up 83% to £6.1m (2019: £3.3m).
In the period, HUP revenues increased by 83% to £1.5m (2019: £0.8m).
Total LiDCO product recurring revenue in H1 was up 12% to £2.8m (2019: £2.5m)..
Geographically, LiDCO product sales grew by 157% in H1 in the UK to £4.1m (2019: £1.6m).
Distribution markets also grew, by 41% to £1.2m (2019: £0.8m), with the greatest demand coming from Asia.
March: Orders of water contamination detection consumables up 46% in Q1 2020 compared to Q1 2019;
Operating loss before tax, interest, depreciation, amortisation increased by 86% to £0.9m (2018: £0.5m).
Within the Monitoring Division no one customer represented more than 10% of revenue (2018: None greater than 10%).
This resulted in an EBITDA loss of US$6.2m in the first 6 months of 2020 (H1 2019: US$1.0m profit).
The increasing impact of the pandemic is further evident when comparing the first and second quarter of 2020 with the corresponding quarters in 2019 which saw the first quarter sales reduced by 15.9% to US$43.4m (Q1 2019: US$51.6m) whereas the second quarter sales reduced by 72.4% to only US$16.8m (Q2 2019: US$60.8m)..
Fund This Project
How are peoples brexit strategies coming along?
Yes I can hear the collective groans and feel your fingers hovering over the thumbs down button, I’ve brought up that happily forgotten subject. Believe me I’m sick of it as much as everyone else, however, its coming and cant be ignored for much longer.
Johnson passed laws saying we cant extend this transitionary phase and the deadline for the EU to let us extended it went by in June. So the end of the road is coming in 4 months time and at present there is no sign of a deal.
To get a deal through EU parliament it needs to be ready by the October EU summit. I’m not sure about the UK parliament but presumably our politicians would require time to scrutinise it.
From what i can gather if we don’t have a deal by sept we’re looking at no deal.
Even if we do get a deal, we’ve run out of this transition phase, that means business will have no time for planning as nobody knows what that deal will be, they have to learn and work it out as they go along, it could be a big shock.
I have a fair amount of my portfolio abroad. Way I see it, the end of the year will be a shit show. If I’m wrong, I’ll still have what I’ve got at the moment. Sorry for the doomster/gloomster outlook.
Similar. A very large percentage of my portfolio is in European stocks, and fully expect the show that you are predicting to come true. So, currently, I am reasonably positioned for the expected shambles that is so typical of this government, and if that is the correct word to use for a grouping of ministerial toddlers. Also, I have tried to invest in sectors within the UK that may be resilient, but if push comes to shove, my finger will be over the sell button, as I am not going to suffer another portfolio decline in 2020.
TT
My thoughts exactly.
“Clearing customs” is a phrase every business will be using a lot more next year.
I think that covid has shown how adaptable businesses can be. It's also shown that the Govt is prepared to act fast, and throw vast amounts of money at a big problem (so far funded entirely by money printing, QE), in a way that I can't recall ever happening (on this scale) in peacetime before.
This suggests to me that the Govt is unlikely to hesitate, and any problems with Brexit could also be met with direct & large scale intervention to support UK businesses in any way necessary.
Therefore, Brexit seems a lot less of a worry than previously. Also, my personal portfolio is positioned in companies that shouldn't see much impact from any temporary trade and administrative problems.
I'm staggered at how stock markets have looked through covid, which involved shutting down much of the economy temporarily - far more severe action than anything Brexit is likely to throw up. Given that backdrop, why should we be overly anxious about Brexit? Covid has certainly put a lot of things into perspective, including B.
Regards, Paul.
"This suggests to me that the Govt is unlikely to hesitate, and any problems with Brexit could also be met with direct & large scale intervention to support UK businesses in any way necessary."
There goes GBPEUR parity.
I think one of the differences between government reactions to Covid and Brexit are that with the former all countries are 'in this together' and are all engaged in money printing. With Brexit it is only one country and that may be perceived differently by the people who lend to us.
Also an exit to Covid is foreseeable and an expectation of a return 'business as usual' reasonable. Brexit is permanent and its outturn not foreseeable.
"...stock markets have looked through covid, which involved shutting down much of the economy temporarily - far more severe action than anything Brexit is likely to throw up"
Stock markets digest information and then look through it, but they don't ignore it. That's why Revolution Bars (LON:RBG) for example, is down 80% from its pre covid level. The stock market has looked at the probable outcome and priced accordingly. Many other shares are in similar situations where a high level of uncertainty remains. Covid is easier to look through than a no deal Brexit would be. The uncertainty will last as long as it takes to agree a deal.
The impact on the economy would be less than a national lockdown, but might run on for much longer. Even so, the impact on the stock market could be muted, particularly at the big cap end which cares more about the global economy. However, the impact on UK society could be more far reaching. For example, while covid resulted in panic buying, a no deal brexit would probably result in genuine shortages of fruit and vegetables given the volume we need to import.
It is interesting to see the government's own "reasonable worst case" which includes power cuts, shortages of fuel, food and medicines, rationing of drinking water and troops on the streets. I haven't seen the original documents but this has been widely reported in the press. Some of that might be far fetched, but on the other hand, I don't think it addresses the true reasonable worst case. It assumes that cross channel flows would be down by 45% for 3 months. I think the true reasonable worst case is worse than that.
To pick one scenario, if we have no deal, it is virtually certain that French trawlers would continue to fish in UK waters, albeit now illegally, or to cause some other issue e.g. blockading ports. If they can't fish UK waters they can't all survive. Given the French approach to industrial action, I think we know what to expect. It is also virtually certain that the govt would then be under huge pressure to send in the navy to sort it out, and indeed this scenario is in the reasonable worst case planning. But that's where the planning ends. Is that really where it ends? It's more likely, in my view, that the situation escalates from there and possibly ending with France and others shutting down all channel crossings. That would be my reasonable worst case.
There's no way that we will get any cake, but there is still a good chance that we will get some kind of fudge and let's hope for that. If we don't it would be unwise just to ignore the additional risks and uncertainties that are introduced.
We were supposed to be reduced to a n economic wasteland by not joining the euro 20 years ago. The lesson to learn is don't listen to scare stories, they are used to try and make us be compliant with what the government wants.
EU always leave big decisions to the last minute. Think a deal will be thrashed out,but even if it is not,I am not unduly concerned about the prospects for our economy.
It’s tricky isn’t it? My usual approach would be to switch into US dollar assets ready for the pound to take the hit. That worked well at referendum time because the market was complacent going in and then panicked. But with the US presidential election coming up and the FANGAMs in bubble territory that could be a volatile situation in the US too.
So is there a safe haven? I don’t fancy holding cash in pounds. I’ve been buying metals and miners. I have an MSCI Australia tracker and I have some emerging market funds. I think the place to look that most of us probably neglect could be mainland Europe? But then their banks aren’t in a great state...
"How are peoples brexit strategies coming along?"
Holding US tech stocks, at least while the Fed music's playing
UK small caps are interesting, a few good stocks here doing ok, many with overseas markets
UK FTSE100 avoid (I think this is key as they are zero growth tied to UK GDP which has many headwinds, Brexit aside)
Silver has been useful as a hedge against GBP devaluation and general Fiat money depreciation coming down the line
Agree with Paul the UK Govt. will happily print more to subsidise industries impacted by Brexit, but there are limits to this. It works until it doesn't. Also there is a risk the EU sees it as state subsidisation and would take counter-action. The Pound does not have the same reserve currency status as the USD so I think the fx market will be quick to price in any problems. A lower Pound fx rate would actually benefit firms with overseas earnings as long as it's tech based not manufacturing or retail reliant on imported supply chains.
The black swan event is the possible breakup of the Union sometime next 5 - 10 years.
I think the main theme in my mind to invest mainly in either overseas companies or UK small caps with overseas markets so I can be insulated from UK economic events, good or bad and so just watch from the sidelines and see how it plays out.
"UK FTSE100 avoid (I think this is key as they are zero growth tied to UK GDP".
Isn't it the case that the FTSE 100 earn most of their profits overseas and would benefit from a fall in Sterling?
"Isn't it the case that the FTSE 100 earn most of their profits overseas"
Yes, that's correct.
I was thinking more the banks not the big miners and oil as I don't invest in commodities except for silver and gold.
Mainly agreed. I have a chunk in Vietnam, European assets, global equities, specific US debt. But I think some of the larger UK financials (ex banks) are fine (e.g. Legal & General (LON:LGEN)). This is one of the last places where, like it or not, the UK has scale, history and exportable strategic advantage. As an ex-manufacturer of real stuff, exported to many countries, I didn't like writing the last sentence, but I also try to learn what will work for the future, that is nimble enough to swerve the politics.
Yes, I too looked at Legal & General (LON:LGEN) but couldn't see through how they will fund the liabilities they have, if interest rates head negative.
Well, while I haven't done serious calculations, things like Cala homes building to rent means they are making some of their own direct investments for income.
Thumbs down not at all. I think we are in danger of burying normal risk under a sea of Covid 19 virus and data and in the US in the seemingly unstoppable rise of six tech stocks (or as John Murphy of BoA put it about Tesla “the ever increasing share price”). - https://www.marketwatch.com/st...
That said with the FTSE 100, FTSE Small Cap and FTSE All share down since the GE, maybe some form of shit show, as Nick Bradshaw puts it, is priced in.
That said thank you for the post, it reminds to check the exposure of my holdings to the UK and whether this exposure is likely to impact the company and the share price.
My take is that the end of the Brexit transition period really doesn't matter that much.
Despite all the hot air, it is highly unlikely that January 2021 will see the UK and EU trading with any new tarrifs in place. It is in neither block's interests, WTO rules allow continuance of pre-existing tarrif arrangements for several years.
There's a risk that Johnson agrees to a half baked 11th hour agreement which is not in the UK's long term interest. He has a track record unfortunately of valuing a catch-phrase, glizy announcement over detail, and substance. Even so, there would be negigible initial impact.
The real, and huge risk in my view is the Euro. It is an economically and politically unstable contruct. At some point there will have to be a resolution, and it's hard to imagine that happening without a nasty economic shock (at best), or full scaled disaster at worst.
I have pondered how to mitgate this risks, but don't have a real answer.