Small Cap Value Report (Mon 25 Jan 2021) - BOO, TET, SPE, ASC, HAT, YCA

Good morning! It's Paul & Jack here with the SCVR for Monday. Many thanks to Jack for doing the heavy lifting on small caps today, freeing me up to write/think about fashion eCommerce! Much appreciated.
Timing - today's report is now finished.
Agenda - starting with big news on the rapid move of fashion brands online.
Paul:
Boohoo (LON:BOO) - acquiring intellectual property (only, not shops) from Debenhams administrator
Treatt (LON:TET) - upside case, after chat with Lord Lee
Asos (LON:ASC) - in discussions to buy some Arcadia brands
Jack:
Sopheon (LON:SPE)
H & T (LON:HAT)
.
Mello Monday - tonight from 6pm
A quick reminder that this popular, fortnightly, online investor event is coming up later today, from 6pm. More details here - as usual, a very good line-up, including our own Jack, who’s back by popular demand!
Lord Lee is doing a talk about how the current rules on takeovers need urgent reform. I totally agree with him, and think we should all get behind this ShareSoc campaign to push for more transparency. In particular;
Joint Press Release from ShareSoc & UKSA on behalf of individual investors
ShareSoc and UKSA recommend The Takeover Panel:
- Review their current rules, which disadvantage individual shareholders and all those who are not privy to a potential bid.
- Sets out a clear and orderly framework for takeovers, including measures to ensure fairness to shareholders and other stakeholders.
- Consider issuing Panel guidance for assessing when talks are serious, so that announcements can be made with the usual caveats – “talks are that an early stage”, “no certainty that a bid will be made”, et cetera.
- Tighten the interpretation of what behaviour is acceptable – and, in particular, review the case of Signature Aviation and Blackstone.
.
Boohoo (LON:BOO)
(I hold)
Exciting news late last night, as the FT reported that Boohoo (LON:BOO) (I hold, as do many Stockopedia subscribers) is apparently buying the Dedenhams brand & online presence, for £55m. NB it is not buying the shops. This is potentially interesting on a number of levels. Firstly, it means the BOO group (already 9 brands) is spreading its wings into a much broader demographic, not just fast fashion for young (mainly female) customers. Secondly, I seem to recall (from when it was listed) that Debenhams focused heavily on online, and some archive material on its website suggests that in 2018, online sales (inc VAT) were over £500m. If BOO is buying something that size as a bolt on, then it could be material to its growth.
Press reports suggests there's a fair bit of interest in TopShop, with Asos (LON:ASC) mooted as the front-runner there, to protect its existing supply arrangements with Arcadia, possibly?
I see BOO has just put out an RNS I'll read it quickly & update this in a few minutes. If you're not interested in BOO, then skip this bit. That's why we put everything into sections with a heading.
"Development of online marketplace and extension of target addressable market"
My summary of key points in the announcement;
BOO confirms it has paid £55m to buy the intellectual property assets of Debenhams from the administrators. NB this does not include any shops, stock, or financial services. So it's a completely clean deal, with no legacy issues being taken on by BOO.
The main asset is a top 10 UK website, with 300m UK visits p.a.
"Fantastic opportunity" to grow customer demographic, and into new product areas (e.g. beauty, sportswear, homewares) - which was indicated as a strategic aim in the last BOO results webinar
Marketplace - this is key. DEB's existing website is a platform for many brands (a bit like Next's website), which BOO is acquiring and planning to expand into the UK's largest marketplace. Maintaining & expanding existing brand relationships, plus adding its own brands to DEB marketplace
DEB is continuing to liquidate its stock via shops & website. BOO will then relaunch DEB sometime in Q1 FY02/2022 (i.e. Mar-May 2021)
Financial impact - no effect on FY 02/2021 figures. "Modest start-up losses" expected, sounds fine to me.
Webcast - we can tune in to this at 08:30 -
Audio webcast: https://webcasting.brrmedia.co.uk/broadcast/600add34efe97358c10a2491
Zeus broker update note is available on Research Tree. It's been super-conservative in assuming only £55m revenue benefit, and breakeven profit, in FY 02/2022.
Directorspeak- Mahmud Kamani, Executive Chairman commented -
"This is a transformational deal for the Group, which allows us to capture the fantastic opportunity as eCommerce continues to grow. Our ambition is to create the UK's largest marketplace. Our acquisition of the Debenhams brand is strategically significant as it represents a huge step which accelerates our ambition to be a leader, not just in fashion eCommerce, but in new categories including beauty, sport and homeware."
My opinion - this looks an excellent deal, and should significantly boost future growth, on top of the existing strong organic growth - last reported at 35% of the 40% total revenue growth, despite there being no Christmas parties to sell dresses for.
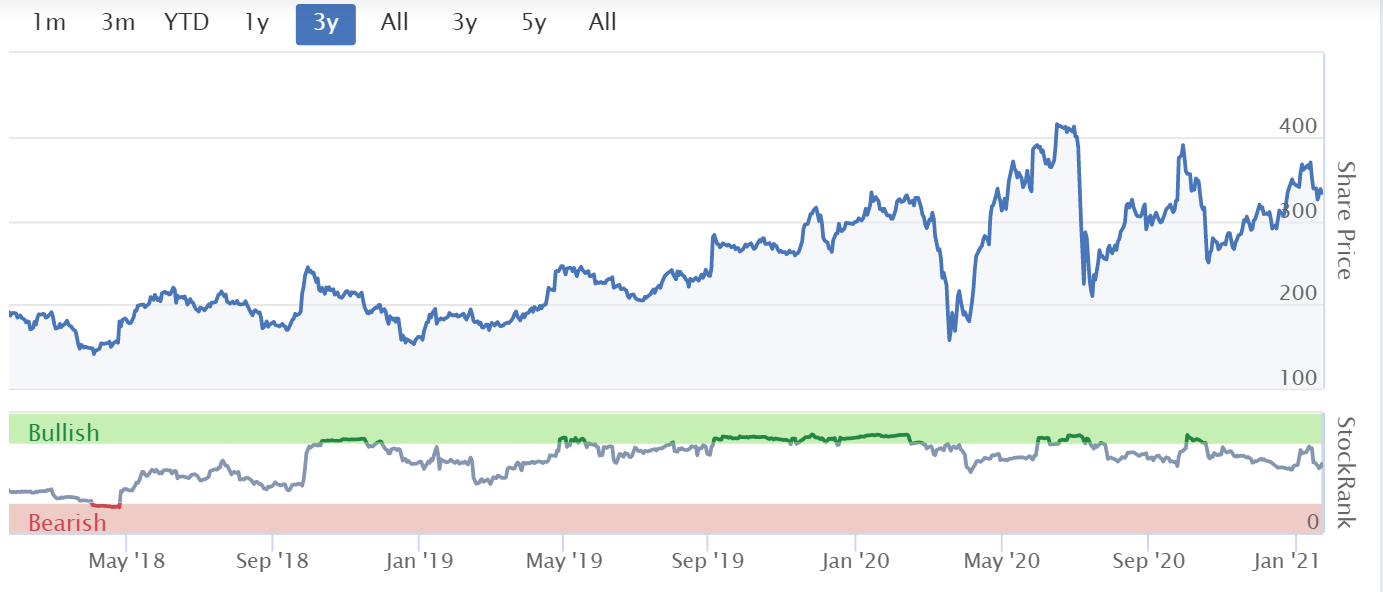
BOO is buying a significant-sized marketplace website, with a large number of existing customers, for a relatively small amount of money. Therefore, logically the share price should respond positively to this news. However, we already know that the stock market does not behave in a rational way towards BOO, you only have to look at the chart to see the mad gyrations in price, so the share price could do anything in the short term!
I remain of the view that ESG sellers have created a series of wonderful buying opportunities for a spectacularly good growth business.
.
.
For me, the short term price is just background noise. The key thing is that BOO probably has the hardest working & most capable, experienced & ambitious management/team in the sector. I see it as a major, international, long-term winner. This deal puts another piece into the jigsaw. Very good news in my view.
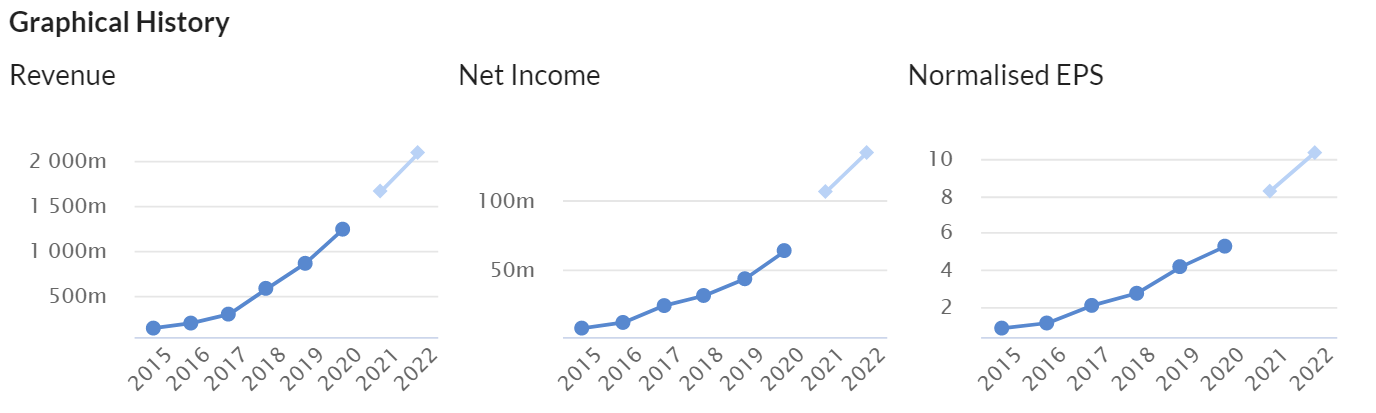
Zeus forecast is for 11.68p adj EPS for the new financial year that starts shortly, FY 02/2022. Therefore at 345p per share, the valuation is a PER of 29.5 - that is stonking value, for a share which has achieved this growth, with lots more to come.
The DEB deal should considerably accelerate future years' growth, but as usual, it's likely to take c.2-3 years to bed in the acquisition & get it growing to its full potential.
.
Treatt (LON:TET)
To follow up on this one from last week. Very much a company I've liked a lot, for years now (see the archive here), although I'm getting increasingly worried that the share price might be running away with itself.
I had a quick chat with Lord Lee over the weekend, a renowned investor, who has held Treatt since 1999 and has been publicly very bullish about the company for many years. He's delighted with the share price rise, and thinks it's justified for the following reasons;
He's always seen it as a one-off company, with nothing similar in the UK market
Valuation should be based on larger, international competitors, and other businesses (he mentioned Guidavan a Swiss competitor), where a PER of 30 or even more is the norm, in a low interest rate world we have today
Treatt is attracting international investor interest as it grows, who are prepared to pay a higher price than UK investors
Still very confident in the company's outlook, and TET is by far his largest personal holding (c.40% of his portfolio!), it's been a 30-bagger for him! Demonstrates benefit of holding winners for the very long-term
Ideal investing scenario is to find shares that not only grow earnings strongly, but also benefit from an upward re-rating of the PER - double benefit makes this very lucrative
Encouraging that the company put out an out-perform statement relatively early in the financial year - often a very good sign in his experience
Move to new UK premises not happened yet - Bury St Edmonds, due to happen later this year (summer?) - should drive efficiency gains/margins. Also new facility in Florida. Should help reinforce credibility with larger customers, when they see the new facilities scale & modernity
Strong market growth in some key categories that TET supplies, e.g. hard seltzers, flavoured tea, citrus, reduced sugar, etc
Experienced - the company has been around for c.70 years, so really knows what it's doing, very good management
My opinion - Lord Lee made a very good case for the share price rise & high valuation being justified. I certainly wouldn't bet against Treatt, a company I've always liked & seen potential in. The valuation remains too high for me though, I wouldn't be interested in buying at this price. There again, I can see why existing holders, sitting on a nice profit, might well be inclined to top slice a few, and run the rest for the long-term.
I hope that gives a bit more balance, as I focused perhaps too much on the high valuation alone last week.
Incidentally, Lord Lee talked me through his new campaign to improve company disclosures re takeover bid approaches. This is a really good idea, and I urge everyone here to check out what he's saying, and get behind it.
.
Asos (LON:ASC)
5030p (up 5%, at 09:17) - mkt cap £5.0bn
Continuing the theme of fashion eCommerce, Asos has also issued a brief update.
Statement re media speculation
- Asos says it’s in “exclusive discussions” with the Administrators or Arcadia re acquiring TopShop, Topman, Miss Selfridge, and HIIT (never heard of it) brands.
- Compelling opportunity to acquire strong brands.
- No certainty of a transaction at this stage.
- If it goes ahead, acquisition would be funded from cash reserves.
My opinion - Asos already sells Arcadia brands, so this looks like a deal at least partly motivated by protecting its supply for popular selling brands.
Apparently, back in the day, Philip Green used to rant about online fashion never working, as people want to try on the product & feel the fabric, and that Asos would never make any money with a 40% returns rate, and to stop nicking his best staff! Actually, on the penultimate point, he wasn’t far wrong, Asos has indeed struggled to make a decent profit margin, but seems to have finally got somewhere in the last year.
Hence very ironic that his best brands have ended up being bought by Asos, following his own dismal failure (hubris-fuelled). I’m glad BOO didn’t chase after these Arcadia brands at the hundreds of millions price tag that the press have been mooting, which looked too high for somewhat jaded brands that arguably had their heyday in the 90s & noughties.
Today’s news from both BOO (I hold) and Asos, is a stark reminder that retailing is moving online at pace. Talking to family & friends recently, we all agreed that buying clothes online feels normal now. If you stick to your favourite brands, then the garment fit isn’t a problem. I’ve updated my wardrobe recently from Next, Gap, and Joules (I hold), and everything fits like a glove, I never have to return anything.
So where does that leave conventional retailers? In a tight spot. As mentioned here many times before, I’m really only interested in looking at retailers which have successfully transitioned online. The rule of thumb for me, is that they should be achieving at least half of all sales online by now. Joules (LON:JOUL) is a good example of that, where I’m buying the dips, to gradually build up a medium-sized, long-term position. Given that so many have failed, or look close to failure, I really think it’s best to resist the urge to bottom fish in apparently cheap things like Mothercare (LON:MTC) or Works Co Uk (LON:WRKS) both of which I’m highly sceptical about.
As regards Superdry (LON:SDRY) and Ted Baker (LON:TED) I reckon the jury is still out. It's not clear to me that either can run fast enough to avoid being engulfed by the tide. If they fail, then the brand value would probably end up paying off creditors, not shareholders.
The other theme that’s interesting is this marketplace idea. Boohoo (LON:BOO) (I hold) mentions this as a key reason for it buying Debenhams IP. It’s looking increasingly likely that fashion brands will be congregating on marketplace platforms, maybe as even their most important outlets in future, as physical stores (esp Dept Stores) wither away gradually. Therefore owning one of, or the biggest marketplace, is the big prize for the future - and likely to drive some mega valuations. I'm toying with the idea of buying back in to Next (LON:NXT) on this basis.
Next (LON:NXT) has a very successful fashion marketplace for other brands. Others are Debenhams (shortly to be part of BOO), Marks And Spencer (LON:MKS) seems to be tentatively going down that route too. I’m not convinced by Mike Ashley’s strategy to concentrate on physical stores at Frasers (LON:FRAS) but it could have merit as the last man standing in the High Street, bullying landlords into giving him selling space very cheaply, or even free?
What about Amazon? They’ve never “got” fashion, so I don’t see that as a threat now, but who knows about the future?
Even tiny Joules (LON:JOUL) has its own niche marketplace, called Friends of Joules.
For me, BOO remains the stand-out opportunity here - superb growth, which if anything could be about to accelerate, and at a reasonable PER under 30 (based on Zeus estimates for FY 02/2022). BOO would probably be worth double the current price, if it were loss-making!! Look at the insane valuations on FarFetch and TheHut. Call yourself a “platform” and operate at a loss or breakeven, and £7bn seems to be the starting point for valuation!
Jack's section
Sopheon (LON:SPE)
Share price: 865p (unchanged at 08:33am)
Shares in issue: 10,202,888
Market cap: £88.3m
Sopheon (LON:SPE) provides software and services for Enterprise Innovation Management solutions. It helps clients to optimise their own investments and, in a sense, adds value to other companies by making sure those companies’ internal investments add value to the firm. It does so with software such as the regularly updated Accolade system.

One reassuring (but hard to quantify) characteristic of this tech stock is that Co-founder and long time executive chairman Barry Mence retains a large stake in the company.

Sopheon has a long history as a software company, stretching back into the 1990s but consistent leadership has seen SPE remain at the forefront of its niche.
The group fell from favour slightly in 2019 as the shift to recurring SaaS revenue (and, hopefully, greater customer lifetime value) came at the cost of a drop in nearer-term sales.
Management says trading has rebounded since and resumed an encouraging trajectory - but the share price performance has failed to match management’s tone.
Trading update for the year ended 31 December 2020
Running through the key points:
- SPE expects full year revenue of c$30m, in line with 2019,
- Annual recurring revenue (ARR) will rise from $15.9m to $18m, although gross retention was down from 94.2% to 91.5% due to ‘challenging market conditions for some customers’,
- The above coupled with a ‘substantial order book’ means revenue visibility over 2021 is up to $22m (2019: $18.9m),
- Total contract value (TCV) of signed SaaS business grew 274% year on year, with new wins included global brands such as DuPont and LG, alongside previously announced Mondelēz and Orion,
- Six of the new customers had initial deal value at $1m or more, compared to just one in 2019,
- Adjusted EBITDA will fall from $6.4m to $5.6m,
- Net cash will rise from $19.4m to $21.6m
Conclusion
Sopheon's Chairman, Barry Mence said: "We believe we have a substantial opportunity ahead of us, and our strong balance sheet gives us the confidence to maintain ambitious investment plans through the pandemic and beyond."
On that note, the direction of travel at Sopheon certainly sounds positive - although the speed of progress might be frustrating for some. High relative valuations generally imply an expectation of good absolute year-on-year growth.
No doubt the top line has faltered in recent years as a result of SPE’s shift to a SaaS model FY20 is expected to be $30m, on a par with $2019:

But Sopheon is winning big, high quality customers and is well positioned to benefit from the accelerated trend towards greater digital presence in a post-Covid world. It seems more likely than not that the group will grow sales in the years ahead, in my view.
As ever with cash generative, net cash, high ROCE SaaS software businesses, conventional relative valuation metrics are high - but then there is also the c$21m net cash position to account for as well.

If you dig deeper into the company it can be hard for the outsider to get a proper feel for just how the group’s products work.
But Sopheon is winning big contracts from well regarded clients. Both ARR and TCV are growing. It faces into a sizable market opportunity, and, with it de-risking its transition to recurring revenue, now could be a good time to take a look at a software company with good clients and strong growth prospects in the coming years.
H&T (LON:HAT)
Share price: 292p (+8.15% at 08:44am)
Shares in issue: 39,864,077
Market cap: £116m
For a long time, H & T (LON:HAT) has seen its share price fall despite looking good value across a range of metrics. The PE ratio has been on a downward trend.

But, pre-Covid, this group had a very solid track record of revenue and earnings growth, comfortably backed up by strong cash generation. It has also built up some attractive growth CAGRs, alongside double-digit margins and returns on capital over the past couple of years.
At some point - unless its business really is fundamentally compromised - that downwards share price pressure has to give.
Today we see an 8% bounce on HAT’s trading update, so let’s take a closer look at this proven operator.
Trading update for the financial year ended 31 December 2020
Here’s the takeaway, right at the top of the update:
Following stronger than anticipated November and December trading, despite lockdown measures, H&T expects the full-year profit before tax to be ahead of market expectations.
The detail:
- Retail jewellery sales during H2 were strong, particularly in December, and for the six months to the year-end were only 6% below prior year
- Returns from precious metal scrappage were 58% up on prior year, reflecting the high gold price
- Foreign currency income was robust at 65% of prior full year levels and Western Union transaction volumes were more than three times higher than in 2019
- The year-end pledge book was £48m, ‘with a resilient performance building through Q4’
- The personal lending book as at 31 December 2020 was £6m, with reduced impairment charges and with repayments and recoveries more than offsetting new lending
- Balance sheet cash balance of £34m with an undrawn £35m bank facility.
Conclusion
There will always be questions around the ethics of pawnbroking but, when provided honestly and with integrity, it has its place in the financial ecosystem.
HAT does say:
We ensured that our customers did not suffer financially while our stores were closed during the Spring, by suspending pawnbroking interest during that period. We continue to work with customers financially impacted by Covid to agree payment deferral arrangements where it is in their best interests to do so.
There is regulatory risk though and the group continues to work with the appointed Skilled Person and the FCA in respect of the HCSTC lending review. H&T expects the outcome of this review to be delayed beyond March due to the pandemic, but ultimately ‘expects an outcome within previous guidance’
For those willing to do the due diligence and confirm that H&T is providing a fair and value-added service to consumers, then the shares do look to offer tempting value on a longer term view given the defensive traits and cash generation.
The group is investing in its stores, technology, and colleagues at a time when other High Street operators (Debenhams and Topshop, for example…) are on their knees. Trading momentum looks to be improving, and there is another potential tailwind in HAT’s exposure to the strong gold price, assuming this trend continues.
Yellow Cake (LON:YCA)
Share price: 223p (+1.26% at 11:51am)
Shares in issue: 84,059,331
Market cap: £187.5m
Here’s an interesting company: Yellow Cake (LON:YCA) buys and holds uranium, offering equity investors a rare option to buy into quite a unique energy source.
It was recently pitched to the SIC, although the Club opted not to buy it (read the write up here). Yellow Cake has also been put forward by a couple of community members that are interested in this part of the market, and Edmund Shing has been flagging the Uranium industry group in his excellent Market Musings posts (most recently here).
It’s certainly not for everyone, and I would point to the comments section in the SIC post in particular for a fairly robust spread of views here from community members.
What’s most interesting in today’s quarterly update is its comments on the market for those interested.
- Yellow Cake's estimated net asset value was £2.43 per share as at 22 January 2021
- 38% increase in value of U3O8 held at 31 December 2020 to $279.5m relative to acquisition cost of $202.3m.
- On 3 November 2020, YCA completed its share buyback programme. A total of 4,156,385 shares were acquired for a total consideration of £8.8m at a volume weighted average price of £2.13 per share and volume weighted average discount to net asset value of 21%.
Uranium market developments
The U3O8 spot market price ended CY2020 at US$30.00/ lb, up slightly from US$29.75/ lb at the end of September 2020.
Spot market volumes decreased noticeably during the December quarter, although Spot market volumes for 2020 reached a new record level of 92.2m lb U3O8 in aggregate.
YCA says this was ‘driven by enhanced purchasing activity by primary uranium producers that had reduced production or suspended their operations due to the Covid-19 pandemic’.
Aggregate term contracting remains low but market sources including UxC indicate that nuclear utilities ‘are beginning to focus on the long-term uranium market and expectations remain for long-term uranium contracting to increase during 2021 as utility fuel managers pursue forward uranium coverage.’
Cameco’s Cigar Lake Mine has also suspended production due to Covid-19 infections. Increased market purchases by Cameco are expected as the company announced, ‘due to the suspension, we plan to increase our purchases in the market to secure uranium we need to meet our sales commitments.’
Conclusion
Promising outlook aside, the global spot uranium market remained quiet entering the first quarter of 2021and UxC noted in its 11 January 2021 Weekly, "Since December 18, overall spot U3O8 demand interest has been very restrained. The notable lack of demand has continued over the first full week of 2021 with almost no activity reported in any component form."
It could be that as the market moves further into the first calendar quarter of 2021, demand picks up across all principal buyer categories; nuclear utilities, uranium producers and traders/intermediaries.
Large uranium producers such as Cameco have already declared their intention to enter the market to procure material to fulfil existing multi-year delivery commitments.
And, ultimately, the uranium price remains too low to support existing production or to incentivise the ramp up of idle capacity. There is little appetite to begin new mine development at these price levels.
If Yellow Cake’s shares continue to trade at a discount to NAV then it will likely initiate another buyback programme. It’s an unusual company that in my view will either do well or continue to go nowhere. And it is totally at the mercy of the uranium spot price. Holders might get bored of waiting for the re-rate.
As such YCA will probably never be a conviction hold for me - I prefer a management team to have a little more operational control over trading prospects - but if you’re looking for a way to play uranium, then this one’s always worth bearing in mind.
.
All done for today, see you tomorrow!
Regards, Paul & Jack.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

126 comments
Thank you so much to everyone who took the time to reply, I really appreciated it. I actually do not want others to do the heavy lifting, but it's for my wife's SIPP, and having already invested most of her SIPP into shares, she wants a bit of diversification!
I will look into both IT's and the portals you mention, thank you all!
Good evening stock pickers. I don’t see why this lateral move for Debenhams brand/platform is good news for Boohoo (LON:BOO) shareholders. I think it throws shade on the strategic focus, management and corporate motivation of boo. Apologies if I’m repeating material from above but I’ve only skimmed SCVR today.
Here goes some quick points. I do not claim I have particularly good insights here and I also acknowledge that boo has had an impressive trajectory to this point:
(Apologies that there's a bit of repetition above and could do with editing...time)
I’m not saying that boohoo is about to keel over. They are clearly successful in their current niche. I believe that this acquisition is probably quite portentous in terms of signalling. Not necessarily ominous but from a fundamental perspective it requires careful assessment. Boo have excess cash to acquire but neither is £55m nothing and probably requires significantly more capital to turn it into more. How likely is it that boo can replicate its capital recycling into high ROCE growth with a mainstream shopping brand. Isn’t this going to be a less fruitful use of capital?
I find the ‘like Amazon’ comparisons regularly made by investors to be lazy. Amazon is an exception rather than a comparison for anyone. If the analogy applies to boo then its when it sticks to online fashion retail...not some UK Amazon-lite built from boob tubes rather than books.
Current market conditions show that with revenue growth (cash flow more optional but boo does have it so real positive for them), ‘platform’, high multiple and investor belief/enthusiasm then ostentatious goals are achievable. Enough belief in the personalities selling the dream and changes in direction and strategy are tolerated, even cheered. Up to you decide whether the boo management attain this exalted status... I believe they have still to prove they have arrived there so I don’t think they have a long hang rope if they misstep in a new area...that could get troubling for valuation and margins.
DYOR. I know many of you guys love Boohoo (LON:BOO) ...so my scepticism may not be welcome. Some of you couldn’t care about the above issues as you’re in it for the price ride and out if it corrects x% from here. But some of you are true believers...Kamanites...you guys can put me right ;)
Your mojo out
PS very long...so I've put up as standalone post here https://www.stockopedia.com/co... . That means its also easier to find in future and discuss (I'm probably way off beam!)
it feels a bit to me that Boohoo (LON:BOO) might have felt the need to do something but obviously couldn’t compete with the bids for Arcadia etc. Of course maybe they were showing restraint re the latter and that would be commended but to buy DEB feels like a poor second best to me. Seems a shift in logic to flog cropped tops etc successfully to teenagers and then shimmy over to a failed brand for fuddy duddies (no offence to any customers on here). “Marketplace” talk seems like an excuse for becoming a jack of all instead of remaining the master of selling cheap clothes to worldwide teens/20 somethings.
Whilst I would've liked them to buy some bits of Arcadia, actually that is just more of the same.
This gives them many more opportunities and directions in which to increase the top and bottom line.
They've pretty much nailed the cheap clothes business. Sure they can keep growing and rolling out brands across the world but where's the challenge in that - they've proved they can do it.
I think the Boo acquisition looks really interesting - bought 300m visits for 55m ie 18.3p per visit - that looks to be very good value.
I put the £ sign in front of the ticker SPE but it did not work?
Copy and paste:
Jack I first bought Sopheon (LON:SPE) in Feb 2019 at 1140p. It was
I'm on the website on a laptop. I have a feeling it is the app on a mobile that causes problems.
Jack I first bought £SPE in Feb 2019 at 1140p. It was very poor timing. I did not have a stop loss. Last year for the first time ever I phoned the CFO at Sopheon and to his great credit he phoned me back. I was impressed and the one thing I remember him saying was "you will not see any of us selling our shares" By that he clearly meant the management team.
I think this is a quality Company born out by a Stockopedia Quality Ranking of 92.
I do think they will be taken over at some point especially as in the last 12 months they have won some very lucrative contracts with big players like Mondelez, LG & DuPont.
Boohoo (LON:BOO) 's shipments to EU are being levied with tariffs unless the paperwork can demonstrate 50+% country of origin of goods is the UK. With red tape and tariffs Boohoo (LON:BOO) will lose market share to companies based in the EU. They'll not be able to easily relocate their suppliers' Leicester sweatshops to the EU either and these same suppliers will have to deal with the Brexit red tap too which will vaporize their meagre margins.
I have felt for some time that the failure Tesco to continue to dominate everything, would be replicated on the High Street, and that people would eventually tire of homogenous high streets and plastic shopping centres.
It would appear that the failure of many local authorities to grasp this, has accelerated the demise of department stores, and in some cases the high street aided and abetted by the war on cars, and totally obliterated by covid directly, and the financial implications of the massive borrowing being undertaken at present by the government.
I remain hopeful that local authorities will become a little more enlightened and encourage smaller and more localised business to take up some of the empty commercial spaces as we exit covid lockdowns, but I am also fearful that the economic implications of the lockdowns on the will be considerable and painful.
I post this to ask if fellow subscribers have actually developed an investment strategy to account for these factors.
At this rate, only M &S and WHSmith will be left, out of all the shops that there used to be, and John Lewis, itself starting to struggle with it's own business model.
Afh Financial (LON:AFHP) - I know Paul and Jack don't frequently cover financials but just to note that, following the recent takeover theme, US owned company Cortino Bidco (indirectly controlled by Flexpoint Ford LLC) have offered 463p cash bid. Are there any other holders here? I'd be interested in your thoughts.
463p doesn't seem particularly good to me for a decent 'Growth At a Reasonable Price' company - post recent results (which still showed organic revenue growth despite the pandemic) we were up to around 400p. Afh Financial (LON:AFHP) has been growing very nicely thanks to a strategy of buying up small local wealth managers for single digit multiples of their profits. I already had 450p down as a reasonable price target for this year so 463p doesn't seem massively attractive and brokers had estimated EPS of 32.6p for FY21 according to Stock data - which I think is likely to be the basic diluted EPS based on the fact this is the figure Stocko seems to use although this share often gets valued at its underlying EPS I find which will be higher still.
What is intriguing is the CEO has decided he is going to sell out most of his shares anyway (10% of the company) at the offer price. Without knowing his personal circumstances this seems a bit odd to me given the potential for other bidders to show interest.
The other major shareholders are institutions so no guarantee this will go through. Personally, I am minded to vote against.
Good morning,
Just one question ,What does PER29.5for Treatt mean? Defination of PER.
Hi Sady,
It means 'Price to Earnings Ratio'. PE ratio and PER are the same thing. So in this case, if you divide the share price by that earnings per share figure, you will get 29.5.
Good afternoon to you all,
I don't comment much here, so apologies if my comment doesn't belong in this section. I currently have all my investments in shares, but I'm now keen to also put some money into funds. I'm therefore wondering if anyone can recommend a good platform for SIPP fund investment? I use Hargreaves Lansdown for my shares ISA, but they are incredibly expensive when it comes to funds. I'm looking at putting the whole investment in just one or two different funds. Any help would be appreciated.
hagon - as you say, probably not the right place, but why "funds" why not ITs if you want to rely on others to do the heavy lifting? Plenty of choice and HL charges are the same as for shares.
hagon - this BB might help u - seen many questions regarding funds over there - u may want to post it over there - https://www.reddit.com/r/UKInv...
I use A J Bell, who have been specialist SIPP providers for a long time. Then I invest in Investment Trusts, not open ended funds. You can also buy ETFs. In that way, the charges are low.
I use HL for non pensions investments, so that I spread the risk across two providers.
As Laughton suggests Investment Trusts might be a better vehicle for you. If you have some Funds in mind, unless they are obscure you will almost certainly find an IT that will be similar if not replicate the holdings of your Fund and the chances are they will be a lot cheaper because they are treated by HL as 'shares'.
Hope this helps.
Richard
But not all funds are available as ITs?
Is Fundsmith fund available as an IT?
There is a Fundsmith IT but it nothing like the fund.
I use HL. You need to compare the discounts they get on fund charges with other providers to get a true picture. I would look at interactive investor though. Depends on portfolio size of course but on a recent comparison i did for a £650k sipp you would save about £1.3k a year in charges on ii compared to HL using six funds as a comparison. In the end I stuck with HL (or rather the other half did) because of the ease of use and being able to keep an eye on everything through a linked account plus the bigger name. Might consider switching the whole lot at some point though.
Hi Hagon - Vanguard offer a range of fairly safe low cost trackers and funds (and I hold one directly with Vanguard). This recent review provides a good intro and some comparisons with other providers https://moneytothemasses.com/s...
Put funds in A J Bell and get their Shares magazine for free (£5 weekly) and is very good for funds stuff and some good tips actually inc the US of A. Have a shares account for a bit of fun (you deserve it as well as your kids) but don't trade too much as a bit costly. IG when get a bit of confidence and then can go spread betting which is the 'roller coaster' of fun.
Boohoo (LON:BOO)
Debenhams
I don't understand how this will aid with the group's international expansion, which is surely where their focus needs to be over the next few years.
Debenhams.fr doesn't seem like the sort of thing a French person would type into google - if there are any French, or indeed Europeans, out there who disagree with me, it would be great to hear from you and my profuse apologies for daring to guess what an entire nation would or wouldn't do.
European Sales
I sold out this morning based on a belief that European sales will materially decrease in the short term, due to:
Note the following email from Boohoo Customer Services received on Sunday 24th January.
I can't imagine many teens/20s customers will be pleased or content to do the above.
In my opinion Boohoo (LON:BOO) will need to set up a European-based distribution centre to alleviate the problem, which will take time and money.
Note that 15% of group sales are to Europe.
-------------------------------------------------
Anecdotally I once got hit with a €20.22 charge by the local postal service for a delivery from China to Portugal that had cost me €23.80.
The split was customs of €8.22 and postal admin fee of €12.00.
I've no idea who pays for shipping if a European customer chooses not to accept the order.
I saw reference somewhere that the limit before charges hit is €200, but that might not solve the postal admin fee mentioned above, which may or may not still apply, and this limit was certainly not mentioned in the reply from Boohoo.
The last trading update (Jan 14th) mentioned teething European sales issues, but I wonder whether that was too soon to know if bigger problems were afoot.
For full disclosure, I sold out this morning on potential short term sales and/or increased CAPEX expectations, but I fully expect the company to thrive in the long run.
Cheers
A
EDIT: Next (LON:NXT) (I hold) and Asos (LON:ASC) (no position) do have European distribution hubs, so I imagine they will be less impacted by recent events
Debenhams did/still do have a good position in some markets eg the Gulf via franchise partners. It’s the easiest pivot in region where e-commerce is much less evolved, but it is an opportunity.
In my opinion Boohoo (LON:BOO) will need to set up a European-based distribution centre to alleviate the problem, which will take time and money.
It's a bit odd that they haven't already, although I haven't looked at their European sales figures. Paying VAT and import fees for customers presumably isn't a long term option so investing in a European distribution centre is the obvious step. Buy European logistics companies?
I've no idea who pays for shipping if a European customer chooses not to accept the order.
Ditto - although it's happening a lot, it seems. And there are even more duties if they're actually re-imported: about a third of goods are being rejected and the suggestion is to burn them rather than pay the duties to bring them back. Completely crazy.
https://www.independent.co.uk/...
Must be a nightmare being an SME exporting to Europe right now.
timarr
it goes both ways UK customers who purchased clothes from European sellers prior to brexit will start buying from UK to avoid the import taxes and handling charges. The BBC ran a story recently about someone buying a cheap coat then being hammered for duty for £70 with charges, and she didn’t accept the delivery and won’t be ordering from them again.
Articles only seem to present one side at the moment depending on what suits them.
So Boohoo (LON:BOO) might loose a good proportion of the 15% European market but will pick up UK buyers keeping their money onshore to avoid the same costs.
I think it’s a good move and see them becoming an online ‘shopping centre’.
Paul, from a female point of view: and we shop differently from men on the whole, and can enjoy our shopping trips. Personally I hate online shopping and tolerate it but avoid where possible as I much prefer seeing (feeling) the clothes and trying them before paying. In a shop I might try on 14 things and buy 1 or 2. There is no fun in online shopping even the staple shops you need to try for size particularly as women there’s so many shapes. I like GAP shirts because they’re long in the back and the arms aren’t too short a perennial problem with women’s clothing, but the ones they delivered the other day, ‘my usual size’ were for a square person. I then had to repack, drive to the next town, queue ,and return.
I think there will still be a need for high street presence or I’ll only be shopping from the independent boutiques - maybe this will revive that sector, the high street was getting very samey. I would prefer a mix . Bring back the clothes shopping experience!
Boohoo (LON:BOO)
Hi TStubbs
It's a good point you make, and a valid one.
I guess the issue is that I can't think of many international players who don't already have a logistical presence in both geographies and so won't be impacted by the recent changes; Asos (LON:ASC) , Inditex and H&M spring to mind.
I'm not sure what portion of UK sales Zalando has, but I imagine a much larger portion of their sales is to European countries. In any case they seem to operate in a slightly different niche to Boohoo (LON:BOO) .
Also note on the zalando.co.uk website it states that "There will be no additional VAT or duty charges requested on delivery by our carriers." I'm not sure how they are able to do this as I don't believe they have a UK distribution centre.
Are there any others who operate in the fast fashion niche who might benefit from reduced Boohoo sales in Europe?
It will be interesting to hear how things are going when Boohoo (LON:BOO) next updates the market.
Cheers
A
Also note on the zalando.co.uk website it states that "There will be no additional VAT or duty charges requested on delivery by our carriers." I'm not sure how they are able to do this as I don't believe they have a UK distribution centre
Hi abtan
I believe Zalando have pushed the problem onto suppliers who need to obtain clearance before supplying their European warehouses. How that works I don't know, sounds like a nightmare.
They've also made suppliers handle returns - they have to go directly back to the supplier rather than via Zalando. You'd imagine a lot of smaller suppliers will give up and look elsewhere in Europe.
I don't think any other company is quite like Boohoo (LON:BOO) - which makes the Debenham's acquisition look a bit odd to me (although I get the marketplace angle). But their ultra fast fashion approach is why they're vulnerable to the ESG hawks - it's almost impossible to pivot away from their current model without blunting their edge.
For me the technological edge and amazing targeted marketing make them a hold, but I do question my own ethics in doing so.
timarr
it goes both ways UK customers who purchased clothes from European sellers prior to brexit will start buying from UK to avoid the import taxes and handling charges.
Boohoo (LON:BOO) will be fine, and will pick up some more UK business short term to offset lost EU trade, but ultimately they need to sort their European distribution in order to address the European market which is five times larger than the UK. They also need to address their rules of origin issues where they source clothes or materials from outside the EU - again this also applies to EU companies shipping to the UK but, again, they have a much bigger market to source from.
By and large raising trade barriers favours large companies over small ones so most of the larger quoted companies in either the UK or the EU will be OK and will pick up business at smaller competitors' expense. Smaller companies in both markets will suffer disproportionately but UK ones more than EU ones as the latter have a larger addressable market to pivot to. It'll also favour marketplaces who can aggregate sales and manage duties and taxes on behalf of smaller suppliers.
Broadly, in anything other than the short term, it won't impact larger companies much but it'll hurt smaller ones quite badly.
timarr
Mobile Streams (LON:MOS) I am almost hesitant to even mention this as it is now only a £3m market cap so a micro tiddler and presumably therefore highly illiquid and certainly speculative so "not for widows or orphans" is an understatement......but they released some news during the day on friday that piqued my interest (and so I bought some at around the 0.26p level for full disclosure).
Cash is £1m so EV is actually £2m and they reckon that gets them to breakeven? It's a new management and where they seem to be going with this is data driven analytics and AI via a product called Streams. This was launched only a few months back and is aimed at the long tail of SME businesses. At the time of launch (I used to hold a few - not my finest investment btw!!) I dismissed it as a gimmick. Launch of a new business, buzzword "data".....blah, blah, blah. But news on Friday from the AGM pricked my ears.........
The new business (two components including a SaaS model) only launched in June and Oct respectively so were 5 & 2 months in to launch by Dec are already generating £9k p/m. Not much when annualised at the moment granted but that's decent growth from a standing start and given the pipeline the company now says it expects to reach breakeven in the next financial year, which by my reckoning looks to be maybe £80-100k p/m (appears to equate to cash burn) so that would be some growth rate if it happened!
Now I'm well aware of the highly chequered past of Mobile Streams (LON:MOS) so don't bother telling me about their rubbish history under the old management :) BUT has anyone on here come across the new Streams product? Winning clients, generating 5 figure monthly revenues very early suggests there actually may be the early stages of something of value here so I'd appreciate any insight if anyone has any. As I say I bought a few just in case it flies, so little more than a punt at the moment frankly, but now I'm looking a bit more closely. I'd like to know why they are winning business, is there any moat or is it just a gap in the market etc etc. so any insights welcome.
Very long and legalistic announcement from Amino Technologies (LON:AMO) today - sending out letters to customers re a scheme to limit and manage a mis-selling scandal . Unfortunately, that letter does not have the support of a 'letter of no objection' to scheme from FCA.
Truthfully, beyond my ken in detail but whenever, paragraphs are very long and clearly written by the Legal team vs the PR agency it is time to beware! If, as I think it will, Amigo eventually goes belly up will this bring down with it the whole Guarantor Loans model ? ie whereby person X guarantees person Y's loan, enabling Y to get loans at 49% vs >100% pa interest - a big improvement if you need the loan and eg have a thin/poor credit file eg recent graduates without well off parents with capital to spare. Not to everyone's taste but in my view/experience it does meet a need if sold correctly.
I dream of the Woolard review exonerating guaranteed loans as a concept whilst punishing wrongdoing in execution by Amigo and (to a much) lesser extent £NSF (which I hold and which would be a big beneficiary if Amigo failed.)
Another one to watch!
Zipmanpeter, I'm confused as you started with Amino Technologies (LON:AMO) and then went on to talk about Amigo Holdings (LON:AMGO) so would there be a typo somewhere within?
I hold Amino Technologies (LON:AMO)
It was Amigo Holdings (LON:AMGO) and not Amino Technologies (LON:AMO) that made the announcement.
Thanks Silver Moon - missed the g in the company short code (AMO vs AMGO). I did indeed mean Amigo.
I take it you mean Amigo Holdings (LON:AMGO), not Amino Technologies (LON:AMO).
Boohoo (LON:BOO) these are not necessarily my opinions but some alternative comments I have been given this morning which in parts made me smile and which may have some elements of truth.
"They are paying for the Debenham's name. As you say, they will relaunch the site.
The IP is not worth £55M. Yes, it's a well-known brand but it's dated and no longer relevant. For £55M they could have built something new instead of giving life-support to something that is already dead. And what rubbish about saying it will allow them to enter markets like cosmetics. They don't have to spend £55M buying the Debenham's name to do that.
These new kids on the block (like Mike Ashley) get a kick out of taking over what were once giants of the high street. They like adding these brands to their collection - it makes them feel good. It is to serve their egos and nothing else: "Look at me, I buried Debenham's and now own it - my grandmother used to shop in Debenham's and she would not have believed it". I would love to hear the load of bollocks they would spew when trying to defend how it will be transformational"
"For what it is worth, whoever gets Topshop, that could be truly transformational. Topshop was the jewel in Philip Green's crown.
"Topshop may not be what it once was but it still has a pulse. It isn't dead like Debenhams. A lot of young people still love Topshop. It could be truly great once more and remember, it has a big presence in the US. People think Topshop is cool there because it is British. Probably the most appropriate company to have purchased Debenhams would have been Saga or Co-op Funeralcare!"
So what does this show? Just that different people can have very different views and that is one of the reasons why the price of shares can go up or down.
I reckon Kamani is shrewd enough to know what he is doing.
For a start I can see make up / beauty brands doing well for Debenhams online + with 1.4mn registered beauty card holders = easy targeting. I reckon that this will be EBITDA accretive within 12-18 months which coupled a multiplier will lead to MV enhancement. Perhaps Kamani wishes to enter the ladies' beauty / make-up brands market - juicy market here. Your Estee Lauder / Clinque / Clarins. Someone has to market for "middle England" - might as well be Debenhams. If Kamani gets this right- this would be worth the price alone and much much more!
The rest of the pieces - im no expert, but Boohoo probably will be going through trial and error to see what works and not. Monteray and other inhouse Debenhams brand are definitely not "in" (if I stopped wearing them 8 years ago that's a fashion statement!) so perhaps Boohoo (LON:BOO) will end up selling these to Sports Direct ;)
Debenhams can be rebranded! It’s long overdue
....the IC take on today's Boohoo (LON:BOO) story:-
A once mighty high street reduced to a carcass being picked over by some of the worst in fast fashion is an ignominious end
Oh dear.
Sadly IC appears to be following FT down the pan :(
As I understand it IC and FT are part of the same group.
Boohoo (LON:BOO) Just reading through the Zeus note (https://www.research-tree.com/...) (house broker but always v conservative.) They write:
“Its database includes six million beauty shoppers, with 1.4 million members registered to its Beauty Club loyalty scheme.“
My understanding is that “beauty” is hugely profitable business generally. If this was all they were buying it would give a cost of £10 per shopper or £39 per club member. The former, in terms of customer acquisition cost, seems (in my limited knowledge of this area) pretty good value?
Further in the same note they give the PE(f) for 2021 and 2020 of other online players:
ASOS 36.1/32.3
Zelando 107.3/104.2
Revolve 57.2/53.3
Amazon 68.3/55.6
THG n/a/37.2
Ocado n/a n/a
AO World 43.7/32.9
BOO 38.5/28.5
It is beyond me why Boohoo is on a lower PE(f) to AO World and has a market cap a quarter of that of Ocado.
I hold
AO world is looking to take some of the £11bn market from Currys as it is only £1.6bn in revenue at the moment, so it is expected to have high top-line growth. So the story goes, I don't own it and I'm completely on the fence about it but it does seem like covid has presented it with an opportunity to gain share.
Ocado does looks very expensive, their fully automated warehouse is quite amazing - if you haven't seen videos of it then I recommend watching them - and they plan to license that tech globally. I don't hold Ocado either and whether that justifies their valuation, who knows.
Ocado may be hopelessly overvalued. What I do know is that we have used them for around 15 years and we have always found their delivery service to be second to none. Having dealt every week with a company with whom we were very impressed I was always perplexed by the huge shorts as the price continued to march upwards. When I find a company I really like it always gives me that much more confidence.
AO's premium lies in its staff culture - this the secret recipe! :)
On Customer Aquisition Costs
A quick google : https://www.propellercrm.com/blog/customer-acquisition-cost
indicates about 10-20 in 2017. 6 million x 10 ~60m so they have not done too badly at all off just the customer db.
One downside is the level of overlap. I doubt you will know until you look.
On the general wisdom of buying debenhams, I am in two minds.
+
Major aid to growth
I would hope they resist trying to become amazon (a storefront) and keep a lot of short run own-label
-
Big new shiny thing to suck management attention from the day job.
Physical department stores start looking a bit tired a few years after the last refurb
Online stores start looking a bit tired a few weeks after the last refurb
Useful information thanks. (I hold) Boohoo management are shrewd and I think Debenhams will be very beneficial to Boohoo. I don't have access to the Research Tree information but know that homeware can also be very profitable and Debenhams were well positioned here . We have to remember that Debenhams was starved of investment over an extended time and I think a number of their brands can be developed with some investment into worthwhile brands on their own. We can see how Up Global Sourcing Holdings (LON:UPGS) has been able to buy some older brands and successfully relaunch them very profitably within the homeware space. Boohoo (LON:BOO) will be hoping to do the same but sell direct (unlike UPGS) so can be very price competitive and also leverage their existing young customer base as they age and start to move into their own homes needing to furnish and equip them.
Hi Paul.
Where do you think Debenhams sits as a brand in terms of age range. I assume Boohoo (LON:BOO) is mainly targeting younger women, but rightly or wrongly I associate Debenhams with an older demographic.
Am I wrong and does this shift Boohoo (LON:BOO) market reach, and/or will it challenge their market knowledge?
£BOO I know you directed your question at Paul but to jump in I think Debenhams is for an older demographic but Karen Millen is also and for a higher income bracket.
I don’t think it will challenge their market knowledge.
I wrote a year or two ago (and got knocked down for it, may have been here or a comment in the FT) that I believe Boohoo (LON:BOO) could end up being “the Amazon of fashion”, in that it is the place that people default to when they go shopping for anything fashion, beauty etc related. I know that if I am looking to buy something I check Amazon first and only go elsewhere if I cannot find it on Amazon. I almost never go to a bricks and mortar shop (Covid or no Covid) for anything, though I am not your archetypal shopper!
The purchase of Debenhams “brand” by Boohoo only reinforces my belief that they have ambitions beyond just being purveyors of fast fashion to young women.
I hold.
I know what you mean by 'the Amazon of fashion', but in theory Amazon is a neutral platform (though I know some suppliers will not use it because they are afraid it will steal their ideas once they see traffic data).
Arguably, these on-line acquisitions have more similarities to older form of acquisition, in that they may also require capital, administrative, marketing and technical overhead. I suppose the theory is that the marginal cost could be less than physical stores.
The commercial realities of this remain to be seen. How many times have we seen old fashioned cross-selling been used as justification for an acquisition. The reality I have experienced is that cross-selling is a much harder proposition because of cultural differences, and lack of investment etc at least in the old models of acquisition.
For the on-line world maybe this may be less true, but I would apply a note of caution for now in assuming that it all will fit easily into an on-line presence. At least the price for £BOO is not too damaging.
Gaming Realms (LON:GMR) are up 10% today at the time I’m writing. (I hold).
This seems to be market reaction to this morning’s RCS about the agreement with BetMGM in the USA to integrate their content. This expansion builds on their work in New Jersey.
I find Mr Market’s reaction a bit strange as this is only an RCS, rather than an RNS, and I had thought that companies use RCS announcements to disclose new information that the market should know but that they don’t think is materially significant to the company’s performance.
However, it does build on the good news flow here about their new license in Michigan and a good trading update in December indicating strong sales growth and a license in Pennsylvania being imminent too. December’s update gave a positive EBITDA figure. Without knowing the adjustments I find it difficult to know if that means they are now making a profit. They’ve been loss making so far, but it looks as though this strong revenue increase will move them into profitable territory if not by their year end then soon this year, hopefully positive free cash flow too.
So, I’m getting good feelings about this one. Assuming their results will show that they are now profitable and growing fast, this could generate a big uplift in the share price from here as the institutional investors who only invest in profit making companies may then take an interest.
What is an RCS? Investigate shows an RNS (6645M) issued this morning at 07:00 titled 'Direct-integration agreement secured with BetMGM'
If you look at the news page for Gaming Realms (LON:GMR) it calls it an RCS
This indicates that it is from RNS Reach rather than a regulatory RNS
https://www.londonstockexchange.com/news-article/GMR/direct-integration-agreement-secured-with-betmgm/14838217
My understanding is that the Reach communications are for non-regulatory announcements. Things that are significant enough to materially affect a company’s results I think are supposed to be disclosed by a normal RNS so the corollary of that is that if it from the Reach service the company doesn’t consider it materially significant.
https://www.lseg.com/areas-expertise/market-information/regulatory-news-service/reach
"If you're not interested in BOO, then skip this bit."
Always good to start the day with a joke, Paul.
LON:BOO - Could someone shed some light why Stocko rated BOOHOO in Oct2020 as 'High Flyer' at the then price of 279p ,and these days when priced at 340 , Stocko is rating it as a 'Falling Star' - bizarre? .PS I am holder
It’s to do with the “Value” figure.
High Flyer / Falling Star flip flop is common amongst momentum shares, especially those growing very fast.
When the next set of results get plugged into the number it should update the value figure and maybe flip back again to High Flyer
I think it's because the momentum figure has fallen rather than the value changing. Momentum now is only 42, it was 66 back in October.
High Flyers have low value figures and high momentum.
Hi Paul
Re Treatt (LON:TET)
“ (he mentioned Guidavan a Swiss competitor), “
Would that be Givaudan?
“He's always seen it as a one-off company, with nothing similar in the UK market”
I’m amazed that Lord Lee said that as he’s known the company for so long. International Flavours and Fragrances (AKA IFF) are just down the road in Haverhill and have been for years. Givaudan bought Quest and as a result have a factory at Ashford in Kent. Perhaps he meant there are no other UK quoted companies in this space. If so, I’m not sure I see the relevance of that as it’s an international market place with multi-national customers. Perhaps he was referring to a particular segment.
Firstly, many, many thanks for taking the time to speak to Lord Lee on Treatt. I haven't seen much in writing from him recently but he always seems open and sensible. As my original interest was spiked by an FT article from him many moons ago I feel I owe him. I only spoke to Treatt once, probably five years ago, and the lady to whom I spoke was very open and receptive to questions. I remember her describing the business to me and that IFF was not only a competitior, but also a client, as I believe was the bigger Swiss company to which you both refer. But it was the openness shown towards me, a paltry retail investor, which remains with me. I might also add that I really enjoyed Paul's interview with Tamsin on pi a few weeks ago. Another candid responder to questions, completely without dissimulation.
*****MELLO MONDAY TONIGHT****
If any of you want to join the show and indeed receive a recording as fully appreciate they are four hours long so needs a lot of stamina then us the half price ticket code for Stockopedia subscribers here...
https://www.stockopedia.com/content/mello-mondaya-second-january-show-this-monday-746844/
Good morning Paul,
May I ask... where do you get your RNS' from? Stocko or a separate source? I hope you don't mind me asking but I'm still setting up all my own sources for things and obviously value your opinion/personal choice.
Hi Lee, Stocko's RNS is okay, but its difficult if not impossible to filter out things you don't need to see (such as IT NAVs etc). If you're prepared to trawl through every RNS, Stocko should give you what you need. However, if you have Sharepad, you can filter and customise their RNS so I find it vastly improved and easier to just see the important stuff. There may be other RNS services too.
Really?
I use separate folios for shares I hold, shares that I’m watching that are serious possibilities, shares that I term blue sky and shares I’ve sold (to monitor if I sold well). Looking at the news tab for each of those gives a good filter of the RNSs. Other than that the daily summary from the indefatigable Mr Contrarian plus Paul and Jack’s reviews pretty much cover it.
But if you’re attempting to review the whole market each day.......
I've set up a stocko folio just to track RNS notifications, shows up happily on the main application page as "news" . If I want, I can add stocks to that folio to track them or remove. Works well for me.
Hi Lee, I find the best source for RNS's to be investegate.co.uk . Two reasons 1) You can just look at all the RNS'S for the day, or you can search for a particular company or keyword. 2) The original format of the RNS is well maintained. So any tables will be easy to read. On Stocko the tables tend to get messed up so that they can become very difficult to make sense of.
There's also the LSE for an RNS feed https://www.londonstockexchang.... Set them up as email alerts. I have both Investegate and the LSE (which I initially set up because the Investegate feed suffered from some glitches a while ago). This now seems to have been sorted but I left them both running. I generally find that the LSE feed arrives earlier than the Investegate feed.
Boohoo (LON:BOO) I think the comment about making Debenhams a marketplace site are interesting. Starting to get a crowded space, with the Hut Group, Next and John Lewis already doing this and M&S planning too, as well as big bad Amazon. That’s quite a competitive space!
The Hut group - remind me what their sales were. £7Bn market cap last time I looked, why on earth would you pay up for something with no track record of success versus Boo? Barking mad.
Thg (LON:THG) 16 years old, £1.6bn revenue with 52% gross margin, EBITDA margin 10% and 51% y-on-y growth with all segments growing at an increased rate in Q4 2020 and y-on-y.
vs
Boohoo (LON:BOO) 14 years old, 1.4bn revenue with 51% gross margin, EBITDA margin 10% and 40% y-on-y growth with Europe ex. UK growth falling from 57% to 32% growth and UK and US growth dropping 2% Y-on-Y in Q4.
Not sure "no track record" is a valid statement.
Always happy to be corrected :)
THG (LON:THG) does not make a profit in the 2020 year and only forecast to make around £12m net profit next year.
Boohoo (LON:BOO) makes £63.7m net profit 2020 and forecast to make £105.7m in 2021.
According to Stockopedia figures THG (LON:THG) has very low margins. Where do you get the those margin figures from?
Thg (LON:THG) financial statements and trading updates.
Net profit includes depreciation and amortisation, of which Thg (LON:THG) has a lot because of the IP it has acquired (Myprotein etc.) and they have a lot of fixed assets and are adding more. At the end of 2019 depreciation was £39m and amortisation was £40m. We should get an updated 2020 number before long and I would expect this to be much higher and that is a good thing long term because it is part of investing in their operations for the future.
They just finished an 800,000 sq ft distribution centre in Poland and are currently building a 2 million sq ft site by Manchester airport, along with the many warehouses they are adding in the US and Asia. I would look more at EBITDA for true business performance trends and wouldn't read too much into net profit for companies which are expanding their operations so quickly. As the new assets are utilised to full capacity, the net margin will grow.
Hi swanhunter,
Just to clarify, the Debenhams website is already a marketplace for other brands. BOO is just going to expand it.
Regards, Paul.
If you want to see the crazy valuations attached to fashion marketplaces, look at the share price of FarFetch in the US!
Just listened into Boohoo (LON:BOO) webcast, a note on the Debenhams marketplace relaunch, which will hopefully give our established brands greater exposure. Do we think this increases the opportunities/chances for further acquisitions of individual brands that we can then funnel through the Debenhams.com site? French Connection (LON:FCCN) comes to mind, then DP, Miss Selfridge etc.
Quick look at the Boohoo (LON:BOO) chart for anybody interested, just ignore if you're in the camp that thinks this is akin to reading tea leaves :)
Despite the fairly wild swings, I think the chart is actually looking quite constructive, forming a wedge going back to june 2020. I'd be looking for a break above 375p, giving an initial target of 600p on a purely technical basis.
Always interested what TA/chart has to say though I don’t I understand it. :-) I came to the same conclusion when writing about my prospects for Boohoo (LON:BOO) in my start of year holdings review of my portfolio when I wrote:
“I believe the share price could over shoot on the up side to £5 or even £6 in 2021 and my long term (three to five years) price target is £10.73.”
The latter figure (£10.73) I will now have to re-work.
Regards
Michael
I have had one eye on this as well for some time. Waiting for the breakout before adding, otherwise holding.
Further Zeus writes on £BOO :
“...457p per share, which implies upside of 37% versus current share price, before accounting for the significant longer term growth potential offered by the soon to be launched ecommerce marketplace platform. Assuming a perpetual growth rate of 4.0% to reflect the scalability of the marketplace implies a share price of 580p, or 74% above current levels.’
So I think £6 doesn’t look unreasonable once the market wakes up to the value here.
Regards
Michael
Hi Michael,
I came up with an intrinsic value of 417p, albeit this was my first DCF, but the news today makes me a lot more comfortable with keeping the growth rate high over the long term.
As an aside I've seen a lot of comments relating to research tree and wondered if you/others think its worth signing up for the paid version?
Thanks a lot
Jack - re: insider ownership of Sopheon, Sopheon (LON:SPE) , you've left off the biggest shareholder, Rivomore / Myrtledare , which if I remember correctly are BVI companies where I'm guessing insiders are the beneficial owners. So it's possible someone like Mence owns 45% .
Thanks for that Sam, I'll dig into this Rivomore / Myrtledare stake later.
Best,
Jack
Thanks Jack. I'm torn on Sopheon: either it's a minnow that will bumble along without potential for exciting growth and slowly be squished by competitors. Or...
-if the BVIs are insiders, then those insiders are really playing the long game from when they bailed the company out many years ago (I may be completely wrong here)
-Silcock, the 5% shareholder on your image, has been there for 3 decades there himself. I think he turns 73 this year? The others similar tenure and not much younger, several with $millions tied up in an illiquid AIM company with no obvious exit.
-Fragmented industry where Sopheon's client list is fairly impressive. Is there value in Sopheon to a competitor than is beyond the PE ratios etc that we look at?
-Private equity long involved with Sopheon's main competitors (Planview, Planisware etc). PE snapping up companies all over the place.
etcetc
re: Sopheon (LON:SPE)
That caused me to have a look at Rivomore and Myrtle, both IoM companies who previously appeared as Norman Nominees (also IoM) first appearing in the 2003 a/cs as holders of 6% Convertible Loan Stock 2005.
That is as far as I got but while there I had a look at the board - not likely to pass the G(overnance) of the now in vogue ESG. The Executive Chairman and one of the NEDs have been there since they founded the company in the 90s. The CEO and CFO were both appointed in 2000. That leaves one other NED, an American consultant, who is the new boy on the Board - he only joined in 2002!
That leaves me still looking for a "something new" factor in this company.
Saga (LON:SAGA) is down 5% as I write. Yet FT reports today some trading news from the cruise division (that has not appeared in a RNS) "sales doubled in first 2 weeks of Jan" (against first 2 weeks of December, etc). See:
https://on.ft.com/3ca38WW
as a medium term buy (assuming we continue to vaccinate the elderly), Saga (LON:SAGA) feels like a very good bet as a recovery bounce. I'd almost go as far as to say we should see a recovery here ahead of the drinks/meals companies since their customer base is going to be able to get out soonest of all of us.
there's a risk that mutations and such reduce the viability of the vaccine but so far the health/science news doesn't indicate that as a likelihood.
much as I don't like to see the price drop for my holding, for those who don't already have a stake - this is what others might call a buying opportunity I think.
Also think a very good medium term buy. But perhaps short term price affected as stated recently that initial cruises will have limit of 800 on board. So will take longer to get payback on the loans on ships than might have anticipated.
Saga update tomorrow.
Prior to actual resumption of any cruise ship operations - I'd imagine that the management will need to make sure that the mutations / vaccination aspect is sorted out properly - just imagine that the cruise goes fully into operation with staff / supplies only to get a case of mutation leading to bad tv publicity exposure, quarantine etc like what we had in Spring 2020 - this would lead to further costs / disruptions / cancellations / initial advertising costs down the drain etc.
Plenty of reasons for drop in Saga (LON:SAGA) today:
What makes me bemused is that the share price is mimicking the wider travel sector shares, yet currently makes £0 revenue in travel, and even with the two ships, the majority of revenues will still come from other non-travel divisions!
If compulsory hotel quarantines are still in operation when Saga cruises hope to restart then your points are valid. The hope is, if supply shortages don’t become a major issue, that by the time Saga holiday business anddtheir cruises are up and running, hotel quarantines should be over in many Countries desperate to revive their tourist businesses.
Maybe we’ll know better when Saga update tomorrow.
Re £SAGE
"Government plans for 10 day hotel quarantine. Can't see it not extended to cruise. Otherwise its a massive loophole (jump on a ship in Belgium, France, or Spain and get into the UK without quarantine)"
Why doesn't the Government declare sealed cruise ships as hotels?...
Two problems solved in one: The customers get their COVID free holiday, and do so within a large isolated bubble with the sea around the edge.
So long as the ship doesn't dock and no boats come along side (nor helicopters, parachutists, or passing drifters in dinghies), it's probably more bio-secure than a Premier Inn with a fence around it.
I'm certainly not excited about Boohoo (LON:BOO) buying Debenhams in all honesty. It has been known as the zombie store of the highstreet for over 10 years.
Boohoo (LON:BOO) are buying the brand but it is a brand known for poor quality clothes, going into administration several times and terrible stores - including their service.
I remember being in Debenhams once with my partner and standing in the shoe department asking the person in the coat department for a size, the response was 'I don't work in the shoe department' and the store assistant then just ignored me. I couldn't help but laugh!
Anyway I digress a little.
Looking at Debenhams online sales mix isn't all that encouraging for me either.:
46% clothes, 32% furniture, 16% toys, 4% food and personal care, and 1% electronics and media.
I don't get excited about the thought of Debenhams clothes or furniture because, like I said, it has an awful reputation. Personal care could have been the interesting one but 4% of £200m? That is £8million. Boohoo (LON:BOO) sell more than that of their own brand personal care so it doesnt strike me as a deal to see them compete anywhere near Next, Lookfantastic, Feel unique or even House of Fraser.
Maybe Debenham helps them reach an older audience, maybe, but I'm unconvinced.
Is it a good deal or a big deal? Good deal, maybe because it is cheap but that doesn't always warrant the deal, especially given the issues I raised above and I just can't see a clear logic in it. Is it a big deal? I certainly don't think so personally.
Boohoo (LON:BOO)
I expect that the purchase of the Debenhams brand and IP implicity takes the acquisition of Top Shop and sister brands off the table, which is diappointing.
I haven't been keen on the idea of TopShop either but I would certainly favour that to Debenhams.
The one positive Topshop has to Debenhams is that Debenhams sells 96% in the UK and Topshop is much more global.
In all honesty, Boohoo made its brands from nothing, so why buy zombie brands? Why not just create your own new distinctive personal care brand and bolt it on to Boohoo and PLT etc. like they have done so far and had success with?
There are even a number of fast growing up-and-coming personal care brands which they would probably be better served paying a little bit more to acquire or just work with and use the Boohoo e-commerce platform and customer base or direct it to a whole new brand if you want to hit a new market demographic.
However, I'm not on the board and can only be an ex-shareholder so I can't tell them what to do and it is just my ranting. :)
Past anecdotal comments are always of interest but for me the focus is what BOO management can do in the future for the Debenhams brand. Just look at what PE did for Dr Martens. Jack Welch's core management belief was that high performing management can turn around almost any business.
Contrary to Jack Welch's belief , there is this from the "Sage of Omaha"
Warren Buffett said, “When a management with a reputation for brilliance tackles a business with a reputation for poor fundamental economics, it is the reputation of the business that remains intact.”
A comparison of GE (Jack Welch) and Berkshire Hathaway (Warren Buffett) suggests that Warren must be taken seriously.
Fortunately, in this case, I think that it can turn out well as Boohoo (LON:BOO) has not taken on the lousy Debenhams business but only the brand names
Just for context, Thornabian is long Thg (LON:THG) who just got a major, major competitor with an outstanding record of success.
Debenhams sold £8 mill in personal care online last year and Thg (LON:THG) 's Lookfantastic sold £298mill and Dermastore in the US (their new acquisition) sold $180 mill last year.
I don't think Debenhams is Thg (LON:THG) 's main concern at the moment. :))))))
Its both good and cheap IMO. I thinks a very smart move. The Brand is pretty strong, a bit like M&S, like it loath it , its a big name, broadens the customer base massively and diversifies product. Its those awful archaic stores that have been the outdated incumbent that needed replacing. Look how M&S are trying to close all its drab old stores and invest in bright new ones where the footfall is highest. Boo won't need to take on any of that expense. I would never have invested here just for Boohoo but this creates a force to be reckoned with, plus I have seen one or two well performing small trust investing here.
I agree. This move is smart and takes £BOO into personal care with instant scale - a very natural adjacent market to fast fashion, especially as it has built its brand range up from low cost items for 16-23 year olds to include more sophisticated/older/more expensive brands. (This expansion is not not yet significant but well underway.) However, I think there is a very big prize now in teen focused personal care products globally. These are high value to shipping cost/high margin products but need specialist knowledge. The real value may be in the personal care links and expertise they are buying as much as the brand.
However, the offsetting risk is therefore whether upmarket brands like Lancome will stay with "Debenhams" under a BOO ownership or will shift elsewhere (note this is emphasis as they will likely not go exclusively with any one marketplace). Debenhams was something of a go to place for product launches in high end personal care/perfumes seeking first mass exposure.
If I were £Nxt I would be scheduling an urgent top-2-top meeting with the likes of Lancome to discuss plans for their store-supported, real-world beauty bars, especially for the older consumer with a bit more time/money
Perhaps we end with (in UK especially) BOO providing an exclusively online marketplace for younger fashionistas; Next for the middle class, slightly older group with the only successful multi-channel strategy; all in an predominantly online world in which Amazon and Direct-to-Consumer don't go away.
Personally, I think that big scale advantages accrue to these marketplace concepts so the weaker ones outside top 2-3 will fail (M&S, whatever Ashley cobbles together etc)
Fascinating stuff. I had sold out of Boohoo (LON:BOO) on a spike but have to re-consider now - which I would not have done if it had simply added Topshop etc
I was a bit wary of Boohoo (LON:BOO) buying Topshop, as more fashion brands (in broadly similar market segments) for (it seems given the competition) a lot of money. This move by boo to buy Debenhams and so make a big entry into the beauty market appears to be an excellent strategic move. Beauty is a very large market with suppliers, huge customer lists including ‘The Beauty Club’; it also allows nastygirl (for example) to develop beauty products to be leveraged onto their existing brands...and of course is an international market.
Then you get into marketplace for home goods, etc. There is obviously competition, but:
JL, excellent service, but operates in different market segments
M&S, still surprisingly rubbish service quite often
HoF, appears to have gone very bling and extravagantly pricey but still has poor website and service
Dunelm, don’t know personally, but they appear to be a strong competitor on home wares for Debenhams
Homeware is a new large market, which boo will utilise their marketing and logistics skills. This is a fascinating opportunity.
If that wasn’t enough it also picks up some Debenhams clothes brands that it could develop further, eg Faith appears to be specifically Shoes and bags, a potentially useful niche. Plus it picks up important relationships with brands who (and potentially want to) sell via Debenhams...further interesting opportunities.
It will be fascinating to see how this will all develop over the next few years.
Martin
(I hold)
Morning Paul. There’s a trading update out for H & T (LON:HAT) this morning (I hold). Would be very grateful if you could give us your interpretation on that please :)
To those more patient than myself ... Cross inference to Ramsdens Holdings (LON:RFX) ...... likely to be similar performance to £HAT - if not better given that many of £RFX's shops are up for lease renegotiations (I do not hold Ramsdens Holdings (LON:RFX)) without the FCA issue.
Re Ramsdens Holdings (LON:RFX) vs H & T (LON:HAT) - bear in mind that Ramsdens Holdings (LON:RFX) has higher exposure to fx and I don't expect there's been much/any of that business over the past year.
In the H & T (LON:HAT) report they said fx was ahead of expectations, >60% if I remember right of what it was the previous trading period.
From memory, Debenhams was actually doing pretty well online, it was the physical stores that were bringing it down. It also has/had a significant presence in the beauty market. So, if I am Boohoo (LON:BOO) then I’m picking up some bolt on online clothing business in a part of the market that I have little presence in currently and I’m entering the beauty market in a meaningful way too.
Looks like a good strategic move.
yes I suspect you're right, I think Debenhams (from memory) never really recovered from being taken over by Private Equity, loaded up with debt, and having their freehold sold off or removed, and then refloated, this might well have been tough without the long term changes in the high street, and covid being the final nail in the coffin, Bet the old management wish they had sold to Ashley with hindsight, bed he wished he hadn't sunk 150M into shares only to be snubbed by the board, and then loose the lot !
£boo is certainly a very interesting announcement. I'm not sure the CEOs saw this one coming when it was a 1 brand c.£300m mkt cap company back in 2015.
I've been bearish on the prospects of Debenhams for pretty much all of that time but having voiced this several times to my shopaholic friends I've been interested to find that there is much affection for Debenhams, especially their beauty offering. It's a testament to this affection that Debenhams has lasted as long as it has and I imagine a stripped out online offering could suit boohoo down to the ground. I'll look forward to q1 2022 with great anticipation.
Good morning Paul, upbeat update from H & T (LON:HAT) this morning that might be worth casting your eye over if time permits.
Sure, either Jack or me will take a look at £HAT , I expect. Bit pre-occupied with BOO, but I'll get onto some small caps shortly!
appears to be a very positive update. I thought the 3 fold increase in Western Union revenue during lockdown was interesting, perhaps foreign workers sending money to family overseas where COVID-19 support measures have not been adequate. SP has gone up a bit today but I've been surprised by the relative underperformance given that the company has been trading profitably throughout lockdown and the shares are only worth around tangible book value. The FCA investigation uncertainty may be holding it back and Artemis recently cut their holding.
The FCA investigation will hold back any potential upside in the SP of H & T (LON:HAT) until Q2 it looks like - quite some time away.
Also, if you look at the pledge book, its massively down YoY, due to lower new pawnbroking activity. This is what drives the revenues/profits - if the pledge book is low, the next 6 months of revenues is going to be a struggle, to try to recover to pre-COVID levels.
Synairgen (LON:SNG) Synairgen has announced that it’s inhaled interferon beta Covid treatment is to be included in a US outpatient trial as part of Operation Warp Speed.
The Boohoo (LON:BOO) acquisition of Debenhams looks potentially very interesting especially the diversification into new product areas and expansion into new demographics. I suspect this is not good for Sosandar (LON:SOS) as the Debenhams demographic is similar to theirs.
cheers
Francis
I suspect it won’t impact Sosandar (LON:SOS) , it’s not like Debenhams weren’t already a major online player. Additionally the RNS states they want to turn Debenhams into a marketplace, so SOS will be able to add their products to this store.
People need to stop thinking Boo is just clothing and start thinking of Boo as a nascent Amazon. Lots of execution risk though in moving to homwares etc.
Oops, edit: long Boo - my biggest holding.
I think its poor news for Sosandar myself.
Few, if any of the Debenhams in-house brands got any promotion. They do have some small residual value, but now we can expect them to be given the Boohoo treatment.
Sosandar to me is still a story stock, that the co-CEOs could predict what the market wanted better than the rest.
Personally I think this doesn't add up, and their breakthrough reflected that the markets were relatively untested with competitors not making much effort for this segment.
It's a bit like the burger market. McDonalds don't make the best burgers, but they make the best selling burgers, a vast difference. There is little point of having the best if you can't sell it profitably.
SOS listing on sites like Next/Debenhams is short-termism I feel.... a bit like Amazon what happens is that the host site gains all the metrics and ends up releasing something themselves which they are able to promote more as they control the display.
Funny how in every town there’s at least one trendy burger joint, where the people who a bit older, savvier and with a bit of coin and style go to eat. McDonalds serves a purpose, and does it profitably, but it’s, well, Monday morning breakfast not Saturday night dinner party.
Of course.
I'm taking an investor view rather than a foodie one.
Maybe Byrons describes the alternative place you say, but they aren't a very good business, I wouldn't invest.
Most BOO holders don't care they are in the Mcdonalds position in the market, rather the business model. Just because there are companies that make superior clothes doesn't mean they are better investments.
I never suggested they did, merely that there’s space in the market for all sorts and there being one big player doesn’t make it impossible or even unlikely others can thrive
Sthree (LON:STEM) FY20 results today. Obviously a hit due to CV19 with revenue, although they feel they'll emerge a stronger business, and are still set to become the #1 STEM talent provider. Alex Smith, CFO is leaving after an orderly handover. Video & podcast.
it will be interesting to see how Asos (LON:ASC) get around the store estate issue with Topshop if they do end up acquiring the business as they reportedly only want the digital business. It could be damaging reputationally given the thousands of jobs that would be lost if the store estates aren’t bought by them/another buyer.
This, along with the demise of Debenhams, Paperchase and others are just more nails in the coffins for shopping centres. Hard to see any value in companies like Hammerson (LON:HMSO) and Newriver Reit (LON:NRR) shares at the moment.
Great point, these two businesses going down without a buyer taking on any shops would represent a significant number of jobs. I thought one of an administrators roles was to protect jobs (the other being getting value for shareholders). There could negatove PR for the buyer if all jobs go and conversely good PR for whomever picks up the shops, suspect the usual suspects Mike Ashley, Next and other strong brands with physical shops (Zara/Primark/H&M ect) will pick up the best shops and the rest will remain closed. Will be interesting to see how this plays out
My morning smallcap tweet:
Ricardo (LON:RCDO) Sopheon (LON:SPE) Mothercare (LON:MTC) Minds Machines (LON:MMX) Filta Group (LON:FLTA) Inspiration Healthcare (LON:IHC) Plant Health Care (LON:PHC) Norman Broadbent (LON:NBB) IG Design (LON:IGR) Proteome Sciences (LON:PRM) Anexo (LON:ANX) Fireangel Safety Technology (LON:FA.) Journeo (LON:JNEO) H & T (LON:HAT), Anexo (LON:ANX), Maintel Holdings (LON:MAI)
Ricardo (RCDO) trading in line. CEO will leave after replacement found. [SP=390 Cap=243m]
Sopheon (SPE) guides FY(Dec) flat at c. $30m after Q4 rev up. Adj EBITDA $5.6m ($6.4m). "Revenue visibility for 2021 is already at $22m ($18.9m) giving cause for optimism regarding the year ahead." [SP=865 Cap=88m]
Mothercare (MTC) Q1-3 net worldwide retail sales down 38%. Guides FY net worldwide retail sales at least £320m, down 59%, and a small EBITDA loss. Proposes move to AIM. [SP=11.45 Cap=43m]
Minds + Machines (MMX) settles recent alleged warranty claims, which it thinks are are without merit. Pays $1m. [SP=4.72 Cap=41m]
Filta (FLTA) guides FY(Dec) margins back to Q1 level but no rev figure. "In the US, demand for our services in the second half came back quicker than initially expected, helped by the acquisition of new customers. With stadia, corporate dining and universities, all major contributors in the past, still in lockdown, there remains some significant future upside to trading revenues." Encouraged by the pick-up in franchise enquiries in H2. [SP=93.5 Cap=27m]
Inspiration Healthcare (IHC) guides FY(Jan) rev at least £36.5m and EBITDA at least £4.9m, both above market expectations. Cites neonatal intensive care ventilator sales. [SP=83.95 Cap=57m]
Plant Health Care (PHC) guides FY rev up 9%, positive EBITDA and cash for the first time. In line? [SP=18.2 Cap=46m]
Norman Broadbent (NBB) guides FY(Dec) net fee income down 18% and gross margin 79% (66%). In line? [SP=4.71 Cap=3m]
IG Design (IGR) Q1-3 rev up 35% but down 9% excluding CSS acquisition. This is stronger than expected but still guides FY in line. [SP=512 Cap=496m]
Proteome Sciences (PRM) guides FY(Dec) rev flat at £4.6m. Pretax £0.03m (£0.2m). Op costs higher due to "increase in business activities for both business units, particularly proteomics services." But rev not higher. Outlook: "further growth in TMT® and TMTpro™ and expects strong progress for proteomics biomarker services with purchase orders worth over £0.8m carried forward into the first quarter of 2021". [SP=4.18 Cap=12m]
Anexo (ANX) guides FY(Dec) rev above mgmt exp but no figure. Adj pretax in line with mkt exp. Pic'n'mix your comparisons. "The Group continues to increase the number of cases involved in the legal action against Volkswagen AG (the 'VW Emissions' case). The Group is currently actively engaged on approximately 14,356 claims. As previously announced, all costs associated with marketing and the processing of claims are expensed as incurred; investment in case acquisition in FY 2020 totalled £2.9m." [SP=132.44 Cap=154m]
FireAngel Safety Technology (FA.) guides FY(Dec) rev down 12%. "Whilst the operational and market impact of Covid-19 inevitably dominated the Year, resulting in the Group reporting reduced sales and a delay in making substantive progress on its Connected Homes strategy, the recovery in the Group's markets in the second half of the Year and subsequent positive trading trajectory has been encouraging." [SP=22.45 Cap=29m]
Journeo (JNEO) wins £1.8m 1-year extension to a framework agreement with First Bus UK. [SP=56.8 Cap=5m]
H & T Group (HAT) guides FY(Dec) pretax ahead of market expectations. [SP=270 Cap=108m]
In line: Anexo (LON:ANX) Maintel Holdings (LON:MAI)
Good morning Paul,
I would welcome your comments on the trading update from Sopheon (LON:SPE) this morning as they transition to a SAAS model. Looks as though they are making progress and adding more clients too.
Just wondering if it was a Freudian slip in your reference to Dedenhams in the second line of your intro this morning!
Morning shopping365,
Just wondering if it was a Freudian slip in your reference to Dedenhams in the second line of your intro this morning!
Ha! Good spot. I'll correct the (rather appropriate) typo now.
Thanks, Paul.