Small Cap Value Report (Thu 20 Aug 2020) - AO., IGP, VTU, LOOK, FUL, CHH

Good morning, it's Paul here with the SCVR for Thursday.
Today's report is now finished.
As usual, this is initially an empty article, so that subscribers can add your comments about the 7am news releases. Then I'll be writing up the main article, section by section, throughout the morning. Official finish time is 1pm.
Today I will be looking at;
Ao World (LON:AO.) - brief comment on strong revenue growth
Intercede (LON:IGP) (I hold) - more colour given on recent big contract win with US Dept of State
2 car dealers reporting today, so I'll review both - Vertu Motors (LON:VTU) (I hold) and Lookers (LON:LOOK)
Fulham Shore (LON:FUL) - update
Churchill China (LON:CHH) - interim results
Van Elle Holdings (LON:VANL) - Final results - sorry I ran out of time, so didn't look at this in the end.
I probably won't have time to catch up today on a small backlog, because my niece is coming to stay for a week, so I have to get everything organised for her visit. Hence an early start today, and 1pm finish at the latest.
.
Brief comment;
Ao World (LON:AO.)
196p - Mkt cap £925m
Trading Statement - this online electrical retailer has issued an impressive update this morning, in terms of sales. As you would expect, with competitors' physical stores closed, it's done well during lockdown. I'm not sure what growth rate the market is expecting, but this does look impressive;
The trading momentum announced at the time of our preliminary results in July has continued and the significant change in demand for AO's products and services has been maintained. As a result, in the four months ended 31 July 2020 we have recorded strong year-on-year revenue growth in the UK of 58.9% to £401.3m and of 91.5% to €74.3m in Germany1....
The demand for AO's products and services has been sustained since competitor stores started to re-open at the beginning of July. This reaffirms our belief that this is a structural shift in demand where customers have found a better way to shop the electricals category.
Competitors also have websites. of course.
Medium term uncertainty due to covid & Brexit.
Nothing said about profitability, or market expectations - that's the crucial information we need to see!
As also mentioned in results statement on 14 July, covid has also resulted in increased costs
My opinion - this share has always looked wildly over-priced to me. It's really just a low margin distributor of mainly generic products that you can buy anywhere else. The CEO's gushing, over-the-top enthusiasm for such an ordinary business, has always struck me as a bit nauseating. How can anyone get wildly excited about delivering electrical goods?
Pre-covid, growth was unimpressive, e.g. UK LFL growth FY 03/2020 was only +8.2% - not enough to justify the high valuation.
Having said all that, today's update shows superb revenue growth due to covid, and it's encouraging that this has continued after physical stores re-opened. If it meets profit targets (today's update is silent on that, which is very unhelpful), then it might at long last start making a profit.
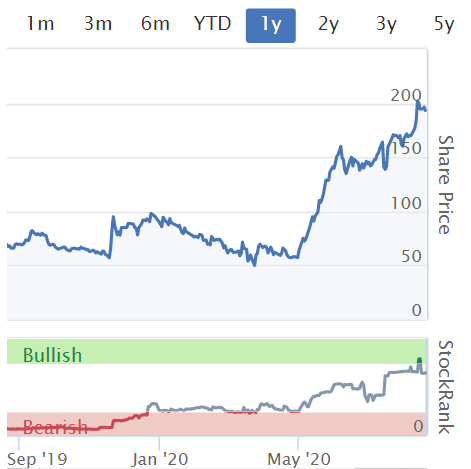
The price is high, but rapid revenue growth means it's starting to look interesting on fundamentals - reflected in a near 4-fold rise in share price since the March low. Well done to holders! Note how the StockRank has soared from deep in the red, to almost in the green, over the last year.
.
.
Incidentally, I've got a new oven arriving on Sunday from AO.com so I'll let you know next week how effervescent the delivery driver is.
.
Intercede (LON:IGP)
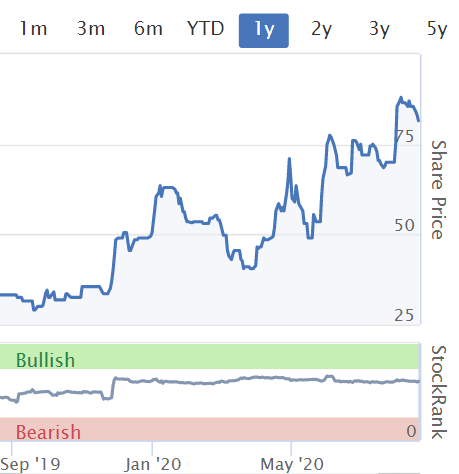
85p (up 4%, at 08:15 - mkt cap £42.7m
(I hold)
Contract Win - Initial Progress Order - this is an update re the contract recently announced - I commented on it here on 30 July 2020. Today we are given more detail;
Initial order for >$1.0m - I like the word "initial" - as this is a "ten year, multi-million dollar contract", then it should produce good revenues & profits. IGP's large contracts tend to be very sticky, and product strong recurring revenues, plus follow on orders, and plenty of consultancy work.
Intercede expects to receive a further order for software licenses and associated development, professional services and support & maintenance within the next few months; a portion of which will be recognised in the current financial year ending 31 March 2021.
As previously announced, the client is the US Department of State (foreign policy, headed by Mike Pompeo) - one of many contracts with the US Govt - reference sites for security software don't come better than this. It's very encouraging to see the IGP is winning new business, for next generation systems. This eliminates the criticism from bears on the share, that it's legacy software. That's clearly wrong.
Forecasts - as mentioned last time, this contract was included in the budget for this year, so it's reassuring, rather than earth-shattering;
The contract was included within the directors' expectations for the current financial year ending 31 March 2021.
My opinion - remains very positive. This has been one of my top holdings since 2018. I see a lot of potential here, but time will tell if mgt are able to deliver the strong growth that seems possible. Recent news has been reassuring. The market cap strikes me as still quite modest, given the upside potential under new management. Very illiquid to buy/sell.
.
.
Vertu Motors (LON:VTU)
Share price: 24.5p (up c.11%, at 09:00)
No. shares: 369.2m
Market cap: £90.5m
This is a chain of car dealers, one of two reporting today.
Key points;
July trading "significantly stronger" than expected - robust recovery in customer demand (I think there must be an element of catch up in this, e.g. for overdue servicing/MoTs. Also a reluctance to use public transport could be boosting demand)
Record month for used car profits - good demand and margins
Aftersales (servicing, repairs) also doing well, and high margins
Fleet market subdued,offset by strong demand elsewhere
Adj profit before tax (PBT) of £7.4m in July (£1.3m boost from furlough grant). All staff will be back at work by end August.
Profit impact of covid is surprisingly small, and now profitable YTD for FY 02/2021;
The Group incurred an adjusted loss before tax of £5.2m in the March to June period and so has now made year to date an adjusted profit before tax of £2.2m.
Overall;
The Group is in a significantly better position than anticipated during the lockdown, both in terms of profitability and cash flow generation....
There's lots more detail in the RNS, which I won't cover here.
My opinion - looking good.
I mentioned here on 14 July that this looks a good time to look at bombed out shares in car dealers, as demand is coming back. That remains my view. Despite all the gloom we hear every day, this seems one of an increasing number of sectors that are seeing encouraging trends, and returning to close to normal. It remains to be seen how sustainable that is, and how much is pent-up demand being released.
Most car dealers have lots of freehold property, so you're getting the balance sheet support from that, in addition to earnings that are now recovering from the covid slump.
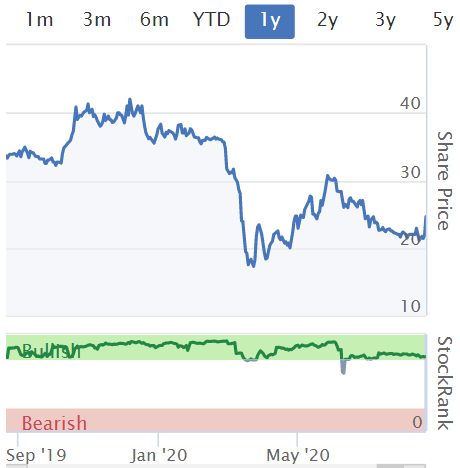
I thought I had a long position in this share, so allowed myself a fleeting warm glow at the rise in share price today, but unfortunately I must have closed the position to meet a margin call, as there are none in my trading account. Never mind. As mentioned before, I like doing the research, but am hopeless at managing my own portfolio! I'm tempted to buy back in, as there's probably quite good upside here, with only a limited bounce so far;
.
.
Lookers (LON:LOOK)
Share price: suspended at 21p on 1 July, due to accounts being late
Update on 2019 Accounts - a further delay in publication, beyond anticipated end August 2020. More problems accounting discovered.
The Board continues to believe that the likely magnitude of the potential restatements referred to above will not prevent 2019 from remaining profitable at the underlying profit before tax level.
What is the "likely magnitude" then? We're not told. The above means nothing, if all the accounting corrections are put through as exceptionals, and/or prior year adjustments
The Company remains in close dialogue with its banking partners.
I bet it does.
Trading update - a separate announcement, which reads well. June & July trading strong. Selling off freeholds to raise cash - this could save the day, freehold property can be a life-saver for companies that get into trouble. Big reduction in staffing, through 1,400 redundancies.
Loss-making in H1;
The Group expects to report a material underlying PBT loss for H1, after receiving c£29m from the Government's Job Retention Scheme.
My opinion - as it's suspended, shareholders can only wait, and hope for the best. The risk is that it's sold off, to enable the bank to recover its money, leaving equity holders potentially with little to nothing.
EDIT: having another think about this, there doesn't necessarily seem immediate risk here, because net debt has reduced so much due to stretching creditors like VAT/payroll taxes. Net debt at 30 June 2020 was only £13.5m (LY: £74.3m). That's not panic stations by any means, especially with a property portfolio of over £300m. So I'm probably worrying too much about solvency. It says that refinancing options will be explored in Q4 2020, which suggests to me that the existing banks might not be keen to continue lending. End of edit.
That may or may not happen, I'm just saying it's a risk. With the shares suspended, nobody can buy or sell anyway, so let's move on.
I think it's usually best to sell on the opening bell whenever accounting problems emerge. In many cases, the first announcement is the thin end of a much larger wedge. People had plenty of time to sell LOOK before it was suspended.
.
Fulham Shore (LON:FUL)
Share price: 10.0p (up 18%, at 12:29)
No. shares: 573.6m + 36m placing shares = 609.6m
Market cap: £61.0m
Completion of banking facilities & trading update
This is a chain of casual dining restaurants, mostly Franco Manca pizzerias, and The Real Greek.
I covered its refinancing recently, here on 6 Aug 2020. Despite liking the business a lot, I baulked at paying 6.75p, and now look a complete numpty given that it's risen nearly 50% in just 2 weeks! Never mind. I can only pay what seems a reasonable price for me. If other people want to pay more, that's up to them. The focus in these reports is analysing the fundamentals, not trying to predict short term market sentiment - I'll leave that to the traders amongst you, who are better at it than me.
Equity fundraise of £2.25m has completed, just a formality, as we already knew all about it.
Bank facilities - enlarged (very large for size of company) bank facilities of £25.75m have also now "become unconditional in all respects". It's interesting to note that this is;
...as a result of the Directors' participation in the Fundraise
That's quite significant to me. It sounds like the bank is basing some of its confidence in the business on the Directors dipping into their own pockets (already large shareholders). That means that outside shareholders are benefiting from the Directors willingness to put in more of their own money. I see that as a big positive.
Trading Update - no figures given, but trading in August has been "markedly up" due to the Govt "Eat Out to Help Out" scheme, with the second week of August being "one of its highest" turnover weeks, despite some restaurants still being closed.
Nearly all sites will have reopened shortly, with 3 central London sites remaining closed.
Landlords/rents - agreements with 40% of landlords to defer, reduce, or waive rents. The trouble is, that covers such a wide range of scenarios, that it's largely useless information. We need figures, not waffle. Why would other landlords offer rent concessions, now that they know the company has refinanced? That can be a drawback for listed companies.
I remain concerned that FUL will be at a considerable disadvantage, since many competitors are doing CVAs/pre-pack admins, hence achieving much lower rents, and jettisoning all their loss-making sites. Whereas FUL has to struggle on with its existing leases, some of which will now be too highly rented.
Other restaurants going bust will often, paradoxically, create new, refreshed, more profitable competitors, as closed sites then re-open under new owners - who will be benefiting from cheap rents, and long rent-free periods, on new leases. Although FUL can also grab a slice of that, by opening new sites, which is mentioned in the last update from 6 August, including possibly some former Carluccios in prime sites, which would not otherwise be available. Hence part of the attraction of FUL now, is that it's got the bank facilities to expand when good quality sites are plentiful, and unusually cheap.
My opinion - no change really. I missed a 50% rise, but certainly wouldn't chase the price up at this level.
As Tasty (LON:TAST) said the other day, August is doing great because of staycations, the VAT cut, and EOtHO. However, Tasty also said it is "extremely cautious" about trading in September. I suspect the Govt could extend the EOtHO scheme, as it's worked so well, and is probably a profit-maker for the Government. After all, giving away £10 per diner in subsidy, is probably paid back in additional payroll taxes, from all these restaurants bringing back staff from furlough. Like all these temporary support measures, it's difficult to see how they can be withdrawn.
At this stage re covid, I wouldn't want to be buying shares in restaurants, since once it's cold, and people are indoors again, then who knows what might happen re new lockdowns, etc? Or, if you think the vaccines could be around in early 2021, then that might be a risk worth taking, if shares are cheap? The trouble is, FUL isn't cheap, so risk:reward doesn't feel right to me at 10p per share.
.
Churchill China (LON:CHH)
1050p (down 2%, at 13:03) - mkt cap £116m
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce its interim results for the six months ended 30 June 2020.
The forecasts on Stocko look old, as they haven't shown any reduction over the covid period, hence we need to disregard the forward-looking valuation metrics. Or, look at them as what would have probably happened, if covid hadn't occurred, thus a potentially useful indicator of valuation in the future.
Interim results - largely meaningless, as this covers the lockdown period. Overall though, not too bad - it eked out a small £0.5m profit, down from £4.2m in H1 LY.
Outlook - markets recovering, but slowly by the looks of it. Expecting production to be 70% of 2019 levels shortly, a new base level. Cutting staffing. No guidance given.
Balance sheet - it's striking how far receivables have fallen, indicating business must be very slow.
Very strong balance sheet overall, so I have no concerns over solvency. Plenty of cash, although that's likely to fall in H2, as receivables (hopefully) build up again, as sales increase.
My opinion - I reckon the breakeven-ish H1 result probably flatters underlying performance, if we were to strip out the benefit of furlough payments.
Also, I'm concerned that markets don't seem to be recovering enough, or quickly, unlike some other sectors that we've seen strong rebounds from.
Therefore, this share looks as if it might need patience. The hospitality sector is really struggling as we know. Give it a couple of years though, and business could be back to pre-covid levels, who knows? I imagine this share might gradually recover over the next few years, so it could make a reasonable entry point now for people with a longer term perspective?
.
That's it for today, I didn't have time to look at VANL in the end, sorry about that.
See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Hi Paul - Always grateful for all your meaningful comments, clear & to the point
Thanks Graham!
Revolution Bars (LON:RBG) and Bigdish (LON:DISH) both covered in small cap dog of the day
https://www.stockopedia.com/content/small-cap-dog-of-the-day-bigdish-dish-648973?order=createdAt&sort=desc&mode=threaded
BSV
Jack, welcome to the regular team, with Paul. I have enjoyed your previous contributions, and look forward to more frequent ones.
Perhaps you would tell us what are your strengths and weaknesses; e.g Paul's great strength is retail, a he rarely does financials. mining, or oil and gas.
Richard
Redrow (LON:RDW), Springfield Properties (LON:SPR) and Crest Nicholson Holdings (LON:CRST) are the main stocks that qualify here. Crest Nicholson Holdings (LON:CRST) is a special sit - it has created its own disaster and is by no means out of the woods. Its house prices fell 17% last reported, very odd and it has debt. It makes perfect sense it has underperformed all others dramatically. That doesn't rule out it being a recovery candidate.
For the other stocks the answer really isn't that complicated. Despite always being the most expensive Persimmon (LON:PSN) has shown itself to be deserving of its rating and relative standing. It preserved cash through the Covid experience, helped by the timing of its period end. Never the less they go into H2 with plenty of cash and conservative land buying policy.
The others incl. Redrow (LON:RDW) and Springfield Properties (LON:SPR) are different flavours of weaker balance sheets. All the builders talk of balance street strength but the truth is far from that. I now remember why I flipped my Springfield Properties (LON:SPR), they carry quite an aggressive net debt position and it would not be a surprise if they raised additional funds. Taylor Wimpey (LON:TW.) moved early and carried on buying so they diluted the equity 10% and played a more aggressive recovery from the off. This could be right... time will tell. I have always considered Bellway (LON:BWY) well run, but its net debt position is zero with facilities broadly balanced by land creditors... and so whilst they could draw on Govt facilities if things deteriorate, I think raising equity would be preferred. That leaves Redrow (LON:RDW), which is smallish. They have net debt of £126m plus a £350m revolver. They are scaling back London and have had to take impairments. Shifting strategy mid Covid is not ideal.
So the quick and dirty conclusion is that the market has only really been willing to back Persimmon to get through the current crisis. If Covid is over then for sure, the others will follow and close the share price performance gap. However, you certainly cant rule out equity raises should we suffer again in H2. Even Taylor Wimpy has pretty much spent its additional funds and so if its strategy remains to stay in the market buying land then further equity raises cant be ruled out. They may be best positioned after Persimmon though.
My conclusion is that Persimmon strength does not necessarily encourage me to throw money at the sector until Covid II retreats. I would go liquid and probably look at Taylor Wimpey and Belway first, followed by Redrow and Vistry. Crest would require much more work.
Hi Paul,
What are your thoughts on Covid providing peak to internet/streaming companies?
Do you think this is a high point watermark for the likes of AO, Netflix, spotify ect?
If you didn't get Netflix during covid when will you ever get it? If you didn't use AO during covid when will you ever use it? etcetera.
Regards,
Michael
I like the new photo.
I like the new photo.
Body language doesn't look great though! Why the crossed arms? Paul's sheepish smile tells me Jack told him what he really thought about Revolution Bars (LON:RBG) :)
All the best, Si
Revolution Bars (LON:RBG) and Bigdish (LON:DISH) both covered in small cap dog of the day
https://www.stockopedia.com/content/small-cap-dog-of-the-day-bigdish-dish-648973?order=createdAt&sort=desc&mode=threaded
BSV
Revolution Bars (LON:RBG) and Bigdish (LON:DISH) both covered in small cap dog of the day
Why are you replying to me? Do you think I care about your thinly veiled wind up attempt at Paul? Or for that matter anything you write? I don't!
Si
apologies I thought you had an interest in £RBG. I've posted it separately from you now.
BSV
Interesting intra-day release of half-year results by Norish (LON:NSH) if of any interest. I expected some Covid related disruption but the results are a little softer than I was expecting; that being said I can see scope for some recovery over the year. Quite an interesting, inexpensive and boring business - essentially the operation of cold stores plus a developing dairy business. Very, very illiquid. I have a little position that i was looking to add to, but may now wait to see how the rest of the year pans out. All the best, Will
You usefully list a large heading of all the 'tickers' of the companies that you will be covering. If not too much of a problem, it would be a great help to novices such as myself, if you also included a sub-heading with the actual names of the companies.
We all have companies in which we have extra-special interest, and thus would be sure to return later in the day if we saw their name.
I wonder if anyone else agrees with me.
Many thanks
John
If you had an "extra-special interest" surely you would know the ticker?
Depending on the device I suppose, but there is also a "securities mentioned" section to the right which shows those shares in long form and just ticker form which is probably useful enough rather than Paul having to remember to do it.
Alternatively, since Paul will in the vast majority of cases, be talking about companies with some form of news or update, these will very likely be listed in one of the first few comments of the day by a couple of individuals who also selfishly summarize these releases.
I think you may mean selflessly?
I have investments in about 60 companies, so my brain is not up to learning 60 tickers. But your tip, about going to the right hand panel, and scrolling down a bit is, is really useful. I wish I had spotted that before.
Nettle, why don't you try opening a new tab by right-clicking on, for instance, the link Intercede (LON:IGP), to bring up the Stock Report. You'll be seeing the Company name as the header. Further more it is a great learning tool to get to know tickers.
Silver
Hi John,
it would be a great help to novices such as myself, if you also included a sub-heading with the actual names of the companies.
Fair point. I sometimes put in a list of the company names near the start of the article, so I'll try to remember to do this every day.
The reason I use tickers in the main header, is because that field is limited in length, so when putting full names in, there's only room for a couple.
Best wishes, Paul.
A great many thanks. When you put the list of companies near the start, that is excellent, and a sufficient help. Especially to lazy people such as me!
Morning - a request for help.
Premier Foods (LON:PFD) released holdings in company and director shareholding. Non Exec has transferred short position to another broker.
how can a director be short of the company - is that allowed?
thanks in advance
When you are a Director you need internal compliance sign off on any long/short transactions. A request for a short position would most likely require a reason. There are also the usual insider rules, he can't front run bad news.
Perhaps he is hedging shares he already holds to lock in a price for a planned sale in the future.
I see - Thanks very much.
A divorce or house purchase perhaps, where he has a need for a defined value of money against a variably priced asset (the shares)
Paul, will you have time to describe your call with Sosandar this week by any chance? Thanks for all your amazing hard work!
Hi danyou,
Thanks! Probably not today, as I'm very busy, but I've earmarked tomorrow (usually Fridays are very quiet for news) to write an update on Sosandar (LON:SOS) following my call with them.
Regards, Paul.
RA International (LON:RAI)
They have announced this morning (there was a delay in this news showing up in my stocky feed for some reason) they have been appointed as preferred contractor to provide accommodation services in Eritrea - expected (not signed on dotted line yet) that this will be over $20 mill of revenue spread over a couple of years. Added to the $60 mill confirmed contract from last week thats some decent newsflow of late.
The RNS came out at 0801, for some bizarre reason.
A good contract update from Intercede (LON:IGP) this morning although since they state "The contract was included within the directors' expectations for the current financial year" perhaps this should have been an RNS-R.
finnCap has increased TP to 100p.
Up 5% at the moment - as Paul has pointed out before this one is horribly illiquid.
£FUL provided a trading update just after market open
Thanks, I'll add Fulham Shore (LON:FUL) to the list, as it's an interesting company.
Thank you all for comments and feedback re the house builders - I will do some more work starting with Crest - I nearly bought this on their warning ahead of Brexit getting sorted. I instead plumped for Springfield which I subsequently flipped at no loss and now it sits 25% lower. I quite like Springfield as a long term play on affordable housing, village development and non SE England housing.
Sherborne Investors (guernsey) C (LON:SIGC) put out a half year report this morning. I have not mentioned it here since I am biased / long / wrong. The worst to listen to. Anyway the facts are its a vehicle that owns one investment - Barclays (LON:BARC) - and the shares trade at about a 25% discount give or take. As Barclays has been so weak the stats get quite interesting... Sherbournes in price is about 200. Barclays (LON:BARC) trades at 110. Barclays itself trades at a huge discount to NBV. Sherborne Investors (guernsey) C (LON:SIGC) is pretty illiquid but assuming the world doesn't end ... and Banks shares slowly recover pre COVID levels... then Sherborne Investors (guernsey) C (LON:SIGC) could 3x. Today in the statement Sherbourne state they continue to expect to achieve their traditional return on this investment. For those that don't know...this is 100%...and therefore would give an asset value to Sherborne Investors (guernsey) C (LON:SIGC) of 200. With these potential returns on offer you can afford to wait a long time, and still achieve a very good annualised exit. The situation is illustrative of market willingness to put discounts on assets even though the underlying is rather liquid. So I would never be surprised by the emergence of a discount. Never the less the significant fall in Barclays plus the discount on SIGC throws up a decent return prospect just from a return to normal. The small move in bond yields is a helpful step.... but clearly all the risk in the shop window.
Incredible thought how they have turned 700m into 250m in three years.
The latest Randall & Quilter Investment Holdings (LON:RQIH) acquisition looks interesting, they seem to be executing some kind of roll up strategy. Wonder if its worth a look? Seems to screen quite well. Any thoughts on this one hugely appreciated?
My morning smallcap tweet: car dealers rev up sales
Lookers (LON:LOOK) Pressure Technologies (LON:PRES) £7DIG Equatorial Palm Oil (LON:PAL) Fletcher King (LON:FLK) Fastjet (LON:FJET) Gfinity (LON:GFIN) Active Energy (LON:AEG) Vertu Motors (LON:VTU) EKF Diagnostics Holdings (LON:EKF) Immedia (LON:IME) Mothercare (LON:MTC) Starcom (LON:STAR) EP Global Opportunities Trust (LON:EPG), Shearwater (LON:SWG)
Lookers (LOOK) Trading in June and July has been better than expected in both vehicle sales and aftersales. Momentum has continued into August. [SP=21 Cap=82m]
Pressure Technologies (PRES) CFO leaving Oct. She is thanked. [SP=91.77 Cap=17m]
7digital (7DIG) wins contract with a global technology company. No £££. [SP=2.41 Cap=59m]
Equatorial Palm Oil (PAL) £400k placing at 0.4p, a 38% discount, to explore corporate opportunities and keep the lights on. [SP=0.7 Cap=2m]
Fletcher King (FLK) Q1 bad as expected. Also its Professional Indemnity insurance has more than doubled, up c. £200k. Guides H1 loss. [SP=36 Cap=3m]
Farcejet (FJET) curtain closing on this long-running pantomime. A long-winded update, reminds holders that it delists on Monday. [SP=0.03 Cap=1m]
Gfinity (GFIN) launches virtual motocycle racing website with news for followers of that sort of thing. [SP=3.9 Cap=30m]
Active Energy (AEG) £1.5m placing at 0.6p, a 23% discount, to keep building the CoalSwitch reference plant and keep the lights on. [SP=0.8 Cap=10m]
Vertu Motors (VTU) July trading continued June trend and was significantly stronger than mgmt exp with adk pretax £7.4m. Adj pretax loss was £5.2m in March to June. [SP=22 Cap=81m]. I hold.
EKF Diagnostics (EKF) $5m investment into Trellus Health, a resilience-driven (huh?) digital health solution for complex chronic conditions. Its initial focus is Inflammatory Bowel Disease eg Crohn's. [SP=57 Cap=259m]
Immedia (IME) £1.1m placing at 10p, a 31% discount, to repay some short-term loan finance and pay abortive transaction costs but mainly to keep the lights on. [SP=14.98 Cap=2m]
Mothercare (MTC) to save working capital by franchise partners paying manufacturing partners directly. Also completed contractual arrangements for Boots UK to be UK and Republic of Ireland franchise. FY accounts delayed. [SP=5.84 Cap=22m]
Starcom (STAR) H1(june) rev down 25%, pretax -$716k (=$505k). "Positive signs for improvement in H2." [SP=1.05 Cap=4m]
EP Global Opps Trust (EPG) NAV 294.4p down 8% in half. SP dicount to NAV inc to 9%. [SP=266.6 Cap=105m]
In line: Shearwater (LON:SWG)
Mr C,
Love your super fast analysis and wit.
Re Ekf Diagnostics Holdings (LON:EKF) I also thought “resilience driven” sounded like bullsh*t, but the announcement merits a read. It includes the following
“Resilience-driven care incorporates positive psychology principles into all aspects of chronic disease management, with a focus on building acceptance, optimism, self-regulation, self-efficacy, and social support. Proven health benefits of resilience include increased longevity, cardiovascular, immune and cognitive function, as well as physical well-being and reduced risk for depression and anxiety.
In a recent study published by Inflammatory Bowel Disease (IBD) Journal4, findings demonstrated that high levels of resilience are independently associated with lower disease activity and better quality of life in patients with IBD. The study also suggested that resilience may be a modifiable factor that can risk-stratify IBD patients to identify those prone to poorer outcomes. ...”
I would love it if Paul could take a look at Ekf Diagnostics Holdings (LON:EKF) if he had time. (I hold).
Regards
Ricardo
It’s probably best for Paul to wait for the interims in September before analysing EKF Diagnostics Holdings (LON:EKF). I think those will be rather good, as will the outlook and N+1 Singer have said they will be upgrading their FY forecasts (again) at that juncture. I hold
Cheers
Simon
As you say, N+1 Singer’s forecast for Ekf Diagnostics Holdings (LON:EKF) (I hold) assume that there will be no follow-on orders for PrimeStore MTM contract manufacturing, after current orders expire in September. This seems unlikely as Covid is not going away, testing is increasing and they have previously had orders renewed. Hence, I understand why you would expect further upgrades for FY20. Indeed, I would assume it more likely than not that PrimeStore MTM orders will still be going out in FY21 - and so far there have been no upgrades by the brokers of FY21 numbers.
Still the key question is it right to value the company on basis of a multiple of its traditional diagnostics business plus the value of its stake in Renalytix Ai (LON:RENX) (plus now Trellus Health) plus the DCF of the PrimeStore MTM business (viewing it as a one-off project)? I think this probably is the right way to value the company and on this basis I think the current share price can be justified.
If the market decides that it wants to value the PrimeStore MTM profit stream also on a meaningful PE multiple - which is possible (justified or not) if the contracts keep getting renewed - then I think the share price could rise considerably further.
Morning Paul, firstly thanks for the recommendation to watch "All the money in the world" - we saw it last night and really enjoyed it.
If you have time I'd be interested in your thoughts on Vertu Motors (LON:VTU) - todays statement seems to suggest a pretty strong recovery.
Thanks, Alex
Car dealers are looking cheap so agree would be great to get Paul's view! Vertu Motors (LON:VTU) looks like it's going to have a good July-September. I am wondering whether with fewer big holidays abroad and concern about using public transport there may be an uplift in car sales at the moment - e.g. from commuter towns where previously households may have had no car or shared a single car. The big issue though is what happens as unemployment rises and trade deals are negotiated, so Vertu Motors (LON:VTU) probably won't immediately go back to recent pre covid highs over the next year. (I hold Vertu Motors (LON:VTU))
"I am wondering whether with fewer big holidays abroad and concern about using public transport there may be an uplift in car sales at the moment"
I was considering the same and I think that is a fair assessment, although I would take a complete guess that they might just maintain a flat rate in sales from this point forward, I.e. I wouldn't expect to see an uplift from here. I think the longer term economic damage to the economy could be enough to weigh heavily on this sector. The uncertainty that Covid brings would be enough for some people to keep their motor for a little bit longer.
A review of CHH would be nice;)
Find This Project
Good morning! Below covers todays regulatory and potentially price-sensitive announcements
The Group now intends to invest in excess of £100 million in its digital elevation strategy. With a particular focus on Flannels and an enhanced customer experience, this investment will be integral in supporting the continued growth of our online channels. This commitment will support the Group's wider ongoing elevation strategy. With digital transformation now at the forefront, the successful reopening of our stores after the Covid-19 lockdown and continuing strong web performance, we are confident in achieving between a 10% and 30% improvement in underlying EBITDA
Find This Project