Small Cap Value Report (Thu 5 August 2021) - SCS, TTG, BRCK

Good morning, it's just Paul here today, with the SCVR for Thursday.
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's section:
The IPO Survival Guide - in case you haven't seen it, this is a major research project, spearheaded by Keelan Cooper at Stockopedia HQ. It's fascinating stuff, and as always with Stockopedia, relies on data to arrive at important conclusions about IPOs. I won't spoil it by revealing any of the results here. You can download the eBook here. There's an introductory blog about IPOs here. Well worth checking this out. It confirms my thoughts on IPOs, which is reassuring!
Scs (LON:SCS) (I hold) - ahead of expectations trading update, for both FY 07/2021 and FY 07/2022. Tons of cash on the balance sheet. This looks far too cheap to me still.
Tt Electronics (LON:TTG) - decent interim results, I go through the numbers. Looks a good company, with a positive outlook. Valuation looks about right to me.
Brickability (LON:BRCK) - accounts for FY 03/2021 look resilient in a pandemic year. Decent margins, acceptable balance sheet, I can't see anything wrong with this. The valuation looks reasonable too.
Paul’s Section
Scs (LON:SCS)
(I hold)
290p (yesterday’s close) - mkt cap £110m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update for the 53 weeks ended 31 July 2021, ahead of announcing its preliminary results on 5 October 2021.
Preamble - This is one of my favourite value shares, which still looks irrationally cheap to me. As we’ve discussed here extensively before, the balance sheet is a thing of beauty, rammed with cash. Furniture retailers have favourable working capital flows, where cash from customers comes in before suppliers have to be paid, and inventories are low because most product is made to order. Receivables are also low.
Dfs Furniture (LON:DFS) demonstrates how it is possible to take advantage of this to operate with heavily negative working capital. Scs (LON:SCS) however operates with an overly prudent balance sheet, hence why I remain of the view that it’s a sitting duck for a takeover bid, because a bidder could load it up with debt, and strip out the cash pile (£91.8m at the interim results), which would largely pay for the acquisition of the company. If you don’t believe me, just compare DFS & SCS balance sheets side by side, which demonstrates the point.
The pandemic revealed to us how companies coped in extremely negative conditions. SCS showed that its very strong balance sheet provided a large margin of safety, and no equity raises were needed. Unlike DFS, which due to its stretched balance sheet, had to do an emergency fundraise, and was lucky to have supportive shareholders.
Another key takeaway was that furniture retailers proved highly resilient - enforced store closures obviously hurt, but some sales shifted online, and powerful pent-up demand quickly became apparent, with lost sales being quickly recouped on re-opening of stores. Lockdowns also encouraged many households to revamp their homes.
On the downside, sector-wide problems have been seen with supply chains, raw materials shortages & price inflation, and freight costs/delays.
Today’s update -
Summary -
Continued strong trading; full year performance for FY21 and outlook for FY22 ahead of market expectations
Order intake - there’s a slightly confusing table showing LFL order intake over the various lockdown-impacted periods. Remember that order intake is not the same as revenues, due to the time lag between taking an order, and actually delivering the goods, which can be weeks or months).
We like to simplify things at the SCVR, so the annual total is the key number -
26 July 2020 to 31 July 2021 | 1 to 53 | (1.5%) | (6.5%) |
This shows that LFL (i.e. stripping out effect of any new, or closed stores) order intake was down 1.5% compared with last year, and down 6.5% on the year before that (pre-pandemic year - the most relevant).
In my view, to have only lost 6.5% revenues, in a year when the stores were closed for long periods, seems remarkably resilient.
Despite our stores being closed for 17 weeks in the FY21 year, our full year like-for-like order intake was down only 6.5% on 2019.
Recent trading - the last 7 weeks of FY 07/2021 saw LFL order intake up 23.7% on pre-pandemic 2019 numbers. That’s well down from the +79% in the previous 3 months after re-opening, but I would expect demand to normalise once pent-up demand has been digested. +23.7% is still very, very good of course.
Comparisons with 2020 are meaningless in my view, as both this year, and last, were disrupted heavily by lockdowns, with different timings.
Order book - the large order intake after re-opening means that the year end order book is massive! £86.3m (I’ve stripped out the VAT, it’s £103.5m incl VAT). Remember that this is not all stronger demand, some of it will also reflect longer supply timescales.
Cash pile - is ginormous at £87.7m at 31 July 2021, and there are no borrowings. That is equivalent to most of the market cap, of £110m. As supply chains normalise eventually, who knows when, then I would expect cash to reduce somewhat. It’s the stand-out feature of this share though.
Outlook - ahead of expectations for both FY 07/2021, and FY 07/2022 -
The Board is encouraged by the strong trading performance since reopening and therefore believes that the Group is in a strong position as we enter the new financial year. The next few months still hold a level of uncertainty, with the tone of government messaging at present being one of caution. However, given recent trading and the strength of the current order book, the Board's expectations for FY21 and FY22 are ahead of current market forecasts.
Diary date - 5 Oct 2021, for FY 07/2021 results.
Broker consensus - I’ve been saying for ages to anyone that would listen, including here, that the broker forecasts looked way too low for SCS, and did not tie in with the resilient trading updates.
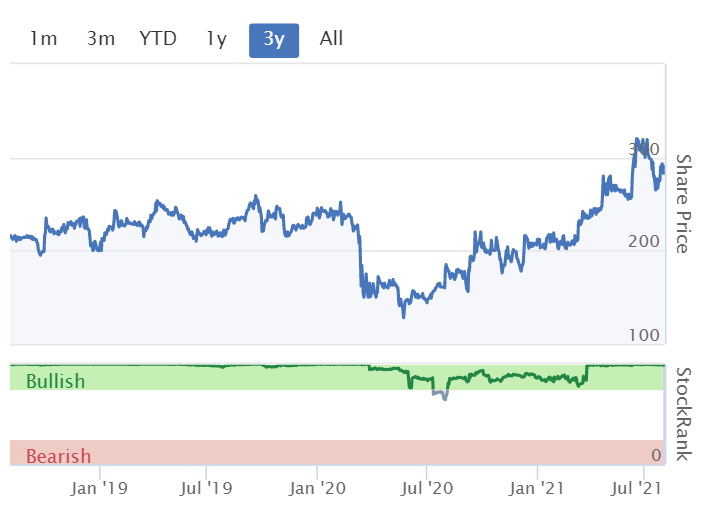
However, I hadn’t spotted this, but in the last couple of months, broker consensus has shot up, especially for FY 07/2022 (the lighter line). Around 28p EPS is now forecast for both years, FY 07/2021 and FY 07/2022.
Therefore, today’s update telling us that the company is trading ahead of both these raised forecasts, is really encouraging. If we guess that EPS might be say 33p, then at 290p per share, the PER is only 8.8 - that’s crazy, considering all the cash on the balance sheet too, which could safely be used for something else, due to the way working capital stays permanently favourable to the company - people miss this point when they net off all the creditors against cash, you don’t need to do that because it revolves permanently.
My opinion - it’s the wrong price! This share should be 400p+ based on the fundamentals, in my view.
EDIT: I forgot to mention dividends. With such a large cash pile, and strong trading, the company has tremendous capacity to pay divis in future, and historically was a good divi payer. There was no mention of divis in today's update. We could even get a special dividend, and/or share buybacks, because shareholders won't be happy with the company sitting on a huge cash pile forever. As long as it's not frittered away on something daft, then it should be fine. Again, I think existing broker forecasts are too cautious on divis. The company could easily afford to pay out 20p in divis, which would be a yield of 6.7%. Hence I'm perfectly happy to sit and wait, because patience should be rewarded eventually with both a re-rating of the share price, and a flow of generous divis in future.
A friend reminds me that SCS has already reinstated divis, see trading update on 16 June 2021. A 3.0p interim divi was declared.
Note also that SCS has repaid £3.0m furlough monies to the taxpayer, good for them!
End of edit.
.
.
Tt Electronics (LON:TTG)
(I no longer hold)
276p (up c.3%, at 09:24) - mkt cap £482m
TTG issued a positive trading update which I covered here on 13 May 2021 when the share price was 248p, I liked the look of this share at the time. Unfortunately, I closed my spread bet on TTG when hit by margin calls recently, which is a pity as it’s gone up to 276p since.
Interim Results for the half-year ended 30 June 2021
Strong momentum, good margin progression and further increase in full year profit expectations
As a general point, companies are now annualising against soft comparatives covering lockdown 1 last year. Hence I make a point of always checking back to last year’s results, to see how bad they were. That sets the context for stronger numbers being reported this year - i.e. this year’s numbers might look like strong growth has been achieved, but it’s often just recouping, or even partially recouping, last year’s shortfalls.
For TTG, last year’s interim results showed a 45% fall in both underlying (“u/l”) profit before tax (PBT) to £9.5m, and u/l EPS fell to 4.8p. Hence to recoup that this year would require a 83% increase just to get back to 2019 levels. It’s striking how percentages work - after a big % drop, you need a much larger % rise just to get back to the starting position.
Adjusted PBT is up 25% (33% at constant currency, note that forex movements are having quite a big effect at many companies at the moment). However, there are 2 complicating factors -
(1) Last year’s H1 numbers have been revised up from £9.5m adj PBT, to £11.3m. Taking the original £9.5m PBT then this year’s £14.1m is a 48% rise. Therefore, it has recouped most of last year’s shortfall in profits.
(2) There’s been an acquisition called Torotel, funded by a placing of 10m new shares at 200p. Therefore lots of moving parts here - H1 2021 revenue & profit will be boosted by the inclusion of Torotel, but the share count has gone up, so profit is spread over a larger number of shares. This is getting complicated!
Adjustments - are quite material here. If there’s a big difference between underlying profit and statutory profit, I always investigate to make sure I’m comfortable with the adjustments before buying any shares.
There’s a reconciliation provided between adjusted and statutory profits, and the adjustments look reasonable - relating to restructuring costs of £3.3m (was much higher in H1 LY at £11.4m), and acquisition-related costs & amortisation. It’s customary to adjust out these items when looking at the underlying performance of the business.
Divisional performance - the stand-out performer is Sensors and Specialist Components, which has almost doubled adj operating profit to £7.4m, and its adj operating margin is up from 7.0% to 12.8%.
We are seeing very strong demand from the automation and electrification market.
Outlook - I particularly like the measures taken to increase the adj operating margin (currently 6.7%) to double digits. Also very good visibility in H2 - full year revenues already in the bag it seems (could this lead to another positive surprise, if more orders are won in the rest of this year? Maybe not, because the commentary says all sites are fully booked for this year) -
· Order and sales momentum continue; 2021 expected revenues already fully covered
· Confident in medium term outlook and further modest increase in full year profit expectation
· Anticipate strong improvement in adjusted operating margin and cash conversion in H2
· Increased visibility in our path to deliver double digit Group operating margins
Materials cost inflation - another key point at the moment, is whether companies can pass on higher costs to customers. TTG reassures on this point -
Price increases are being put through to reflect the recent cost inflation and we are already winning material new orders at the higher price points.
Balance Sheet - NAV is £313.4m. Intangible assets total £209m, plus bizarrely the pension scheme is shown as a £65.4m asset, despite clearly being a liability that requires £5.4m cash injections each year. It really is long overdue for pension scheme accounting rules to be fixed, as they’re a complete nonsense at the moment.
For that reason, I would remove the £65.4m pension asset, along with the £16.2m deferred tax liability (which usually relates mainly to pension schemes).
Putting all that together, I get NTAV of £55.2m, which is OK.
The gross debt is very high, but partially offset by £100.6m in cash, which looks a bit odd.
Overall, I think it’s OK, and the working capital position looks very healthy, so no concerns here overall from me.
Cashflow statement - there’s quite a large £(18.9)m working capital movement, which might be seasonal perhaps, as it was £(11.2)m in H1 last year (“LY”)?
Capitalised development spending of £1.0m in H1 is not excessive.
Pension schemes gobbled up £2.7m in cash every half year, a material amount, so needs to be adjusted for in the valuation of this share.
Net debt - looks too high to me, at £107.3m. Although there is plenty of headroom on bank facilities, plus there is £75m of fixed rate loan notes over 7-10 year maturities, a much better/safer form of borrowing than bank debt, in my opinion. Cheap too, at 2.9% interest rate.
Valuation - Stockopedia shows 14.4p EPS broker consensus forecast for FY 12/2021. That’s been tweaked slightly higher to 14.6p by one broker this morning, so we’re in the right ballpark. Rising to 17.6p next year.
What PER to use? I think about 16 feels right, taking into account the pension scheme cash outflows, and the net debt. Which gets me to a 282p share price target as looking reasonable - very close to the current market price.
My opinion - I’ve only pulled out some key points, there’s loads more detail in the commentary, which reads very well I think.
This looks a good company, at a reasonable valuation. I like it.
The fact that its factories are already fully booked for 2021, and it’s successfully passing on cost increases to customers, suggests the company is in a sweet spot, making products that are in strong demand, or even in short supply. What competitive moat it has, longer term, I do not know.
The planned increase in operating margin is also attractive.
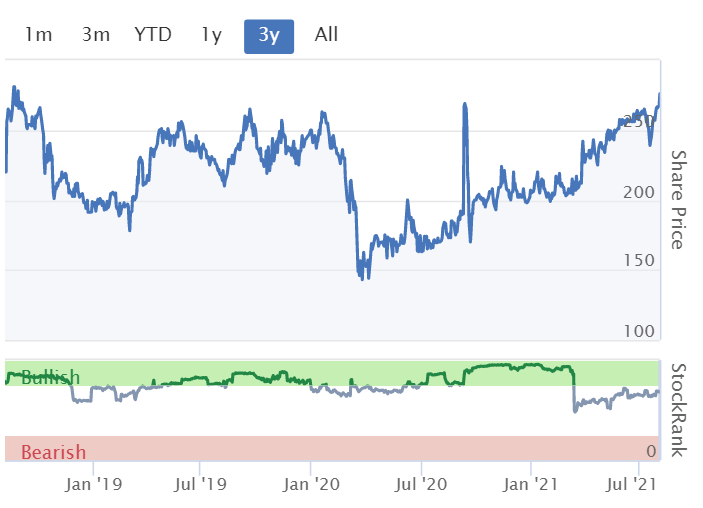
Overall I think the big rise in share price is fully justified, and this share still looks reasonably priced, given the positive outlook. Not sure I’d want to chase the price much higher though, for now.
.
.
Brickability (LON:BRCK)
101p (down 3% at 11:51) - mkt cap £300m
Here’s our previous recent coverage of this brick distributor -
2 June 2021 - large Director selling (£38m) & placing (£55m) at 95p, to fund a big acquisition (£63m)
20 April 2021 - ahead of expectations trading update, but failed to mention that profits are down on last year!
9 Feb 2021 - positive trading update, raises guidance for FY 03/2021
.
Moving on to today, we get the (rather late) accounts for FY 03/2021 -
Preliminary results for the year ended 31 March 2021
Brickability Group plc (AIM: BRCK), the leading construction materials distributor, is pleased to announce its preliminary results for the twelve-month period ended 31 March 2021.
Strong performance despite economic challenges
Considering all the chaos caused by the pandemic/lockdowns, these numbers look good to me.
- Revenue down 3.2% to £181.1m, although that’s flattered by acquisitions
- Adj PBT £15.0m, down 11.8% - not bad at all, considering pandemic disruption, so this looks a resilient business
- Adj EPS 5.56p (down 23.5%)
- Adjustments look fine to me, and are mainly acquisition-related amortisation
- Dividend held flat at 1.95p
- “Trading in first quarter of FY2022 encouraging”
- “Acquisition pipeline going forward looks promising”
Balance sheet - FY 03/2021 figures now pre-date the big placing,in June 2021, so the figures will have changed. However, given that an equity placing funded the big acquisition, then the basic structure of the balance sheet won’t have changed that much. Debt won’t have worsened, which is my main worry with acquisitive groups.
The stand-out number is how low inventories look. I’ve queried that before, and it’s because BRCK has a drop-shipping model, where customer orders are often fulfilled directly by the manufacturer. Very nice, if it can be sustained like that long term.
Overall the balance sheet looks OK to me. BRCK has managed to avoid the danger from multiple acquisitions of depleting its NTAV. In this case, that’s still positive, NTAV = £8.6m - not much, but the lack of need for inventories makes a big difference, meaning BRCK can operate with much lower working capital (and lower costs) than other companies which need to carry enormous inventories in expensive warehouses with lots of staff.
Broker update - many thanks to Cenkos for providing an update note on Research Tree.
Adj EPS is forecast to rise to 7.3p this year FY 03/2022, and 9.2p the year after.
So at 101p this share looks good value, assuming nothing changes in the macro outlook, or competitive pressures.
My opinion - I can’t see anything wrong with BRCK, it looks a good company at a reasonable price, based on the information I have today.
Major Director selling is a concern though, but they still retain big stakes.
Also it must be a helluva job to integrate and manage all the bolt-on acquisitions.
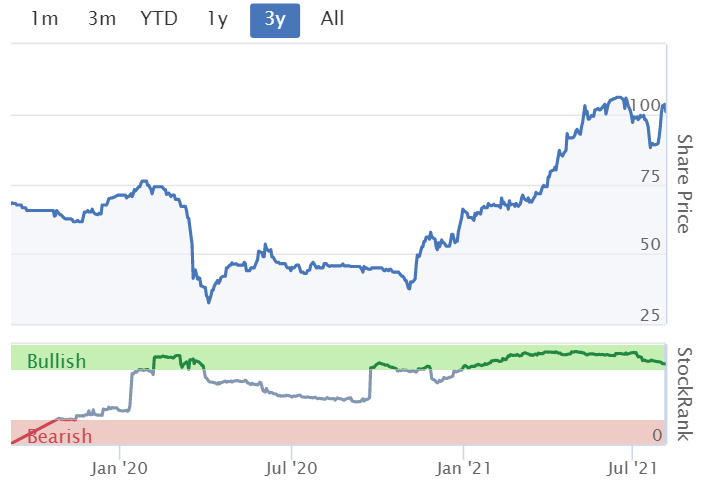
Assuming all that works out OK then, this share looks potentially interesting. High StockRank too.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Fonix Mobile (LON:FNX) the SR fell below 50 at around 145p.
It would be good if there was an update, on the Investment Club when stocks are stopped out. Pity they don't have fantasy funds on the new site, then it would be so easy to track the Investment Club performance.
I see that Fulham Shore (LON:FUL) have changed nomad and broker with immediate effect to Singer.
My hunch is maybe a fundraising. They have debt. But they also want to rapidly expand. Not enough existing cash flow to self fund rollout.
They did manage to fund raise last August at a 2% premium to share price though. But that was when it was 6.25p...
Fulham Shore (LON:FUL)
I wander if fulham shore brand(s) would be better suited to a bigger entity with more firepower to roll out the brand?
having said that at least if they do raise funds themselves rather than put themselves up for sale the shareprice is reasonaly bouyant. £20 mil to spend on expansion would probably go a long way at present compared to 3 or 4 years ago.
Any chance of a lookback at Lsl Property Services (LON:LSL) results from yesterday? Happy if it gets covered tomorrow. Results are very good but difficult to compare LfLs as the property market is so different this year to last year and LSL have also been busy acquiring and divesting operating units as they align themselves behind a pivot to a greater financial services orientation.
Perhaps one for Jack following his reviews of Belvoir (LON:BLV) and Property Franchise (LON:TPFG)?
LSL as you probably know is a mix of owned and franchised Estate Agents and Surveying, Valuation and Mortgage services. Probably more like BLV than TPFG and will indeed be providing mortgage services to much of the TPFG estate under a recent agreement.
I see this as undervalued on a read across. May be down to the historically lower margins they have achieved or simply them being a little under the radar. I'm hopeful the new focus of the management team will bring them in line with PEs for BLV (14.9) and TPFG (13.7)
LSL stats currently on Stocko as SR 91; Super stock; Forward PE 11.3 and PEG 0.7.
Just posting breaking non-smallcap news that Daily Mail And General Trust P L C (LON:DMGT) has agreed to sell its RMS business to Moody‘s (yet another US buyer) for £1.425 billion.
https://www.investegate.co.uk/....
Looks to be a pretty full price at about 37x trailing EBITDA.
Gus.
Hi Paul,
Reach (LON:RCH) (I hold) announced H1 results last week. I don't think these were reviewed. I appreciate you can't cover everything, but wonder if it's on your 'to do' list?
Regards, Raj
Morning Raj!
Sorry no, Reach (LON:RCH) is not on my to do list. The shares have done incredibly well, so the market now is £1.24bn, and we don't normally go above £700m here (recently raised from £300-400m).
Also, to be honest, I don't buy the bull case on RCH. The reason being that the company has a slowly dying print business that seems to make the big profits. They don't split out what profit the growing digital business is making. So it's impossible to value as things stand. Hence valuing it on a PER basis just looks wrong to me. It needs to be split in two, and have the print business on a very low PER, as it's a fag-end business, and then value the digital business separately. I haven't seen any information to be able to do that.
Also the real world cash injections being sucked into the pension scheme are massive.
But who cares what I think, the shares are going ballistic, so enjoy the ride :-)
Best wishes, Paul.
Paul, thanks for clarifying and for your thoughts on RCH. I'm really grateful for the fantastic work you and Jack do.
I agree I am still not convinced the digital side will ever fully offset the decline in the print side, although the market clearly thinks otherwise ATM and well done to anyone still holding.
Fonix Mobile (LON:FNX) does anyone know why the shares are up 11% today, can't find any news?
Fonix Mobile (LON:FNX) ST tip in IC alpha.
Upbeat trading update
Fonix Mobile (LON:FNX) there is no update today, the latest one was on 21st July.
It's been tipped in the IC with a target price of £1.90; that is almost certainly the cause of the spike. LON:FNX. I stupidly sold earlier this morning just as it started to rise. Ho hum!
Fonix Mobile (LON:FNX) OK thanks, I don't read the IC. 190p would be nice, I nearly sold out this morning also.
I also sold Fonix Mobile (LON:FNX) this morning. D’oh! Not my smartest/luckiest of moves. Not quite as bad as the time I sold Sportingbet. I sold it in the morning a couple of hours before it was the subject of a takeover bid!
Fonix Mobile (LON:FNX) tipped by Simon Thompson in the IC Alpha subscription.
ST's the reason for the rise - and don't forget that Jack Brumby got there much earlier in his write-up here on Stocko for the Investors Club. Well done, jack!
Well done Jack indeed for his pitch on Fonix Mobile (LON:FNX) although when he made his original presentation the shares were up at 166p (I should know, I bought them at about the same time!) so today‘s rise is still chasing to make up lost ground.
Gus
Has the Club not been stopped out of Fonix Mobile (LON:FNX) as price fell to 124p?
Naked Wines (LON:WINE) is pleased to announce it has won a record set of awards at the Decanter World Wines Awards ("DWWA") 2021, the world's largest and most influential wine competition. In total, the Company's exclusive wines received two platinum, seven gold, 48 silver and 105 bronze medals.
Received this today from the local wine bar The Humble Grape."You may have read the press coverage about the ‘perfect storm’ of Brexit and Covid resulting in 200,000 current, unfilled hospitality roles. After an incredibly difficult 18 months of Covid-related closures, the hospitality staffing crisis is now our biggest problem. With so many vacancies across Humble Grape, it’s difficult to operate at full capacity and as a result, our expansion plans are on hold. Which is where you come in…!". Makes me again question my share holdings in the hospitality industry.
Yup, going to a painful next few months for hospitality. Either lack of staff and therefore lower revenues, or lower margins if they pay more. But medium term, prices will have to go up as all businesses pay more for staff, so margins will bounce back and arguably absolute revenues and profits will grow from inflation.
Re Scs (LON:SCS) - the current position is excellent I accept and I see the argument for a PE-backed takeover. However, betting on the latter happening is risky - its been "ripe" for some time. Absent that, the attraction has to be the dividend as long term growth is likely to be difficult.
Their market is not going to grow much faster than population (adjusted for inflation) and as a retailer, only just over 10% of the business was online at the interims. That arguably leaves them open to disruption from digital first businesses (Made.com), the online marketing scale advantage of DFS or others following a cheap & cheerful product supply strategy - IKEA, Debenhams in a couple of years (!). The only structural offset is squeezing the remaining independent sofa people and lower property prices.
Good points re £SCS. However, I’d take stated online sales of sofas with a pinch of salt. Having just been part of the pent up demand, and spent some months sitting on 100s of sofas, I suspect the ‘online sales’ only occurred after physically landing a derrière on cloth. The online sale only occurred as a convenience after sleeping on any decision. Any Online only competition is little threat imo, they are too big an expense, too big to return, too hard to judge comfort/feel, to allow purchase from pictures, online or not.
Agree I think online threat in this space is limited as people will want to have a look and feel of the real thing. Also one of their big competitors (Harveys) went bust so they could pick up some of their business.
Morning Zipmanpeter,
Re Scs (LON:SCS) - the current position is excellent I accept and I see the argument for a PE-backed takeover. However, betting on the latter happening is risky - its been "ripe" for some time.
I would say a takeover bid for SCS is just the cherry on top, and not the reason I would invest. When you see something that's a complete no-brainer for a leveraged bid, then it confirms that the fundamentals are too cheap, in my view.
As you say, if there's no bid, then we're likely to get a reliable flow of generous divis instead. Head we win, tails we win, I love situations like that!
I know you liked Made.com (LON:MADE) but personally I think the overlap with SCS is probably little to nothing, because SCS is very much at the cheap & cheerful end of the market. I think it has a huge advantage over loss-making internet furniture companies.
I was looking at Wayfair's StockReport here last night (I'm lucky enough to have USA data too, a perk of the job!) and it only moved into a modest profit after previous heavy losses, after achieving $14.1bn in annual revenues! It's valued at £18.8bn (sterling) mkt cap. Seems nuts to me!
Lots of very highly priced eCommerce businesses have sold off recently, as the lockdown-related boom in online shopping seems to be washing through, inevitably. ETSY plunged after hours last night, after reporting good Q2 figures, but a sharp slowdown in outlook for Q3.
So obsessing about the ESG issues at the eCommerce business which cannot be named, could all be a red herring - it's more likely a sector-wide de-rating, globally, for fast growth eCommerce companies.
Regards, Paul.
Paul,
Wasn't me supporting Made.com ! I just quoted the first (of many) new internet-only players to came to my mind plus internet-savvy bigger companies ion the space. (I thought about including Debenhams which under BooHoo might well go for fashion-first, cheap on trend furniture but was trying avoid the new B-word on SCVR main page! )
But my view is that consumers are rapidly becoming more comfortable with online purchases or even big ticket items as long as they believe in the returns policy. This favours big budgets and specialists. I don't think SCS will disappear - just they might be priced right as they might not be able to gallop from here.
does anyone know why broker forecasts decline 17% for 2023?
Paul,
Thanks for the speedy analysis of £SCS.
Some weeks ago, you treated us to a summary of your largest holdings and your current views on them. When there's a quiet day, it would be really interesting if you had time for an update.
Martyn
Good morning Paul, not sure if you have Tt Electronics (LON:TTG) on your list today, but your thoughts would be appreciated if you get chance. Thank you.
Just to shed some light on why TTG might be interesting to look at: (always helpful for Paul)
Interim Results for the half-year ended 30 June 2021
Strong momentum, good margin progression and further increase in full year profit expectations
Record order book and continued strong order intake with good visibility building for 2022
Re. Tt Electronics (LON:TTG) , I’d also add to your points of interest list that it’s also a good prospect for a possible bid given the growing interest in aerospace and defence as targets reference Meggitt (LON:MGGT) and Ultra Electronics Holdings (LON:ULE) ).
Gus.
Yes I'll look at Tt Electronics (LON:TTG) next. Not much else going on today, but I still have a couple of backlog items from last week to look at, so will manage a full report by lunchtime :-)
I was really impressed with the report in Creightons (LON:CRL) and the acquisition of Emma Hardie provided added interest as it is a business I am aware of. I have just watched the video on PI World about the acquisition.
Am I missing something? Creightons (LON:CRL) have paid £6.5m for a business that made a £40k net profit and £200k EBITDA. Their justification is what they may be able to do with it.
The deputy MD is their Sales and Marketing director. She chatted on with buzz word laden chat that was far from convincing.
My worry is market positioning. Creightons (LON:CRL) are a mass market company looking to buy their way in to the premium brand space. They believe they can expand Emma Hardie by using their existing sales network and also their in house manufacturing. Their is a big risk hear of damaging that 'premium' brand.
Emma Hardie simply has not performed. Yet Barry Cooke the MD has been kept on as MD. That doesn't really make much sense to me either.
To me it seems like they have paid well over the odds and the acquisition is high risk in terms of integration.
I like Creightons (LON:CRL) in terms of revenue growth, EPS growth and ROC.
However, this acquisition concerns me. Am I missing something?
I think you're right to ask those questions of the acquisition. I assume Creightons (LON:CRL) see opportunity to expand profit margins but at face value the numbers don't look great. The market might be excited by how if the company doesn't reach 125p share price within the next 12 months it will need to pay Emma Hardie owners more - perhaps indicating the company is pretty confident the share price will be above 125p. Also Simon Thompson did a write up recently which may have boosted the share price too.
I think you're being a bit harsh on the deputy MD. She seems excellent to me on the company webinars I have watched - on top of her brief and the market trends and she fills me with confidence.
I like Creightons (LON:CRL) a lot but sold out recently as I think the share price has got a bit ahead of itself given the company didn't seem to talk about profit increases for FY22 in most recent webinar and it also will lose the one-off benefit from hand hygiene sales it saw in FY21.
Thanks Patrick. Maybe I am being a bit harsh on her. Given the high price paid I thought the case would have been more compelling.
As I said I know Emma Hardie quite well and I was talking this through with a contact of mine. He said there was another beauty product business with a turnover of £5m that had never made a profit. That sold for £12m recently.
He said the thought process is that the risk is in the early stages of building a brand and it's awareness. It is cheaper to buy the established brand and then to try to grow sales, expand in to new markets and cut costs to drive profit. As such the valuation is based on what it is worth to Creighton rather than what it was worth under it's previous ownership.
It kind of makes sense.
Wow Paul - Thanks for such a speedy SCS update - Excellent - Much appreciated - Enjoy the rest of the summer :)
Thanks matylda! Where I see something cheap, and ahead of expectations, I try to rush out a section before the opening bell, but it's difficult to balance speed & quality! (especially first thing in the morning, I'm not a morning person)
Best wishes, Paul.
Hi Paul
Have you got an opinion on Quiz plc?
Seems to be wrongly priced ( probably should have been at least 30p+ )
Thanks in advance
If you go to the Stock Report and press the Discussions button on 4th line down of £Quiz Stock Report you get a list of previous mentions on Stockopedia. Paul reported on it on 12th July https://www.stockopedia.com/co...
Yes, I'm very bullish on Quiz (LON:QUIZ) and have bought 2% of the company over the last year. It's doubled from my average buy price, so am very pleased with progress. The market seems to finally be waking up to the fact that it's not a basket case, in particular - strong balance sheet with net cash, family still owns c.50% so interests aligned (hope they don't take it private though!), loss-making shops ditched in a pre-pack administration a year ago, new leases signed are short (average 2 years) and on turnover rents about half the previous rents. Established online offering. Experienced rag traders who know what they're doing. Quiz's niche is special occasionwear, which got killed by lockdowns. Now people are buying that type of gear again, e.g. for weddings, parties, etc.
Last trading update was pretty good, and cash actually rose, so looks like the company is cash generative again.
I'm not saying it's the best brand or operator, because it isn't. A bit of an also-ran. However, the valuation is still strikingly cheap. A fraction of the price of Sosandar (LON:SOS) (I hold) and In Style (LON:ITS) for example, despite being a bigger business than either. Although SOS & ITS are growing faster than QUIZ.
As always, DYOR obviously. I've tried not to mention QUIZ too enthusiastically here before, because it can trigger a spike up in price, people chase it up, then it goes back down again. But this time, it seems to be gaining some traction.
I have no intention of selling any, and have pencilled in a 40-50p upside target price. Would be very nice if that works out! But it may not, it will depend on the newsflow.
Bear in mind there's been no dilution, so in theory it could recover to previous highs, if performance improves dramatically. They have lost most of their concession sites of course, since Debenhams closed. Also overseas shops were a distraction & have been closed I think - international is now just Republic of Ireland.
Regards, Paul.
yiannos1
QUIZ (LON:QUIZ)
Have you got an opinion on Quiz plc?
Seems to be wrongly priced ( probably should have been at least 30p+ )
Can you advise why you think it is wrongly priced - it's pretty unhelpful saying i undervalued without explanation of why briefly?
Here are my random thoughts.
They had underlying loss for 6 months to 30/9/2020 of £5.6 mill
Latest update advise they had less than £3 mill net cash (at least its positive !)
The group has not given any idications that i am aware of that they are making profits - so i am presuming they are still loss making (i know of no current forecasts ref current year profits so may have missed something)
IMHO this is highly risky investment - chance of close to 100% wipout if things go wrong - the business is IMHO "priced accordingly at present" to factor in these unknown "material" risks.We all know that the markeet hates uncertainty and you should expect basement price when nowt is know.
The flip side is that upside is great if for example they can get back to £2 mill to £3 mill profits + per year - not sure why you should think its more before any real recovery has happened and we have been told didly squat about how much profit they "won't" do this year.
If there are any estimates for current year i am not aware of that could change things.
finally in addition there is the elephant in the room i that the Ramzan's hold a large % of the shares - so small shareholders may not have a future say in what direction the company takes. What is potentially good for the main shareeholders family could be really bad for minor shareholders - ie they could easily be wiped out if business needs funds and they remove their support.
QUIZ's cash position latest info -
As at 12 July 2021, the Group had a £2.7m net cash balance (31 March 2021: £1.5 million). In addition, the Group has £3.5m of bank facilities available which are currently scheduled to expire on 31 October 2021, which the Group intends to renew.
So net cash rose from £1.5m to £2.7m in last 4 months. The undrawn bank facilities are in reserve, but I doubt will be needed now the shops have re-opened. The family are absolutely loaded, so can probably get an unsecured overdraft for the business with ease.
IMHO this is highly risky investment - chance of close to 100% wipout if things go wrong
I think that's completely wrong. If you dig into the figures, and check out the strong balance sheet with net cash, and plenty of liquidity, and a rich family backing it (they took out something like £90m in the IPO, from memory), plus lease liabilities extinguished, then I think real world risk is quite low!
Still, it takes all sorts, and your view was the general market view until recently, which enabled me to buy dirt cheap after crunching the numbers ;-) (cheeky, but I couldn't resist, please forgive me!!)
When talking to investor friends about QUIZ, nobody was interested. Everyone thought it was a basket case, and wouldn't even look at the numbers. That's the opportunity here I think.
Best wishes, Paul.
QUIZ (LON:QUIZ)
PauI
I think that's completely wrong. If you dig into the figures, and check out the strong balance sheet with net cash, and plenty of liquidity, and a rich family backing it (they took out something like £90m in the IPO, from memory), plus lease liabilities extinguished, then I think real world risk is quite low!
I accept your points that this is not the worst balance sheet in the world but IMHO i would say it is not particualrly stong in the context of ongoing unknown lossses and large payables figure so i think we will have to agree to disagree here.
Per the last interims they had £10 mill of payables ignoring lease liabilities - so please correct me if i am wrong but are they not 100% reliant on the payables bods being happy to offer credit to the extent that its not payables that need no credit ratings?
So net cash rose from £1.5m to £2.7m in last 4 months.
Its easy to pimp cashflow and they confirmed they benefited in period from inven
Note i hold quiz and am positive on the prospects and i think from the low point the upside potential more than compensated for the downside risk. But i am not nieve enough presume this is not a risky investment with less than £6 mill headroom and presumably losses still being made.
"and a rich family backing it (they took out something like £90m in the IPO, from memory)"
Ok specific question in this regard if they are happy to chuck in £5 mill via rights issue - surely they have the option to coimpletely screw over small sharehgolders here if they and other larger institutions choose to do things on terms that suit them.
This may work out very well like Saga where the main bods have ensured shareholders have not been screwed over , but there is always the potential they coluld raise at highly diluted numbers for curent sharholders (like £RBG) - it may work ok if you have spare funds to add extra later - but not everyone plans on doubling up on the size of their initial investment to stay where they were.
So net cash rose from £1.5m to £2.7m in last 4 months.
In this regard they specifically advised also
During the Period, the Group benefited from the Debenhams concessions trading for a short period prior to their closure allowing for the clearance of most of the Group's stock associated with these concessions.
If you dig into the figures,
I have dug into the figures cheers - i dont generally post thoutghts without having done that - i just have a slightly different outake from what has ben presented.
Finally ref me being comepletely wrong in my thoughts/calcs.
The last word i will leave with the auditors whose comments included the following text included in the interims release - i don't know the context of this quote (please read full text to clarify) and whether this is concerns that would apply now - but untill they provide clean bill of health this is the latest i can see ref going concern - and it it is clearly uncertain at best !!
The uncertainty this created in the Group's ability to accurately forecast trading cash flows and continue to trade within their current facilities indicated that a material uncertainty existed that may cast significant doubt on the Group's ability to continue as a going concern.
Hi rmillaree,
Fair points, well made! As you say, we can agree to disagree, but it's always helpful to hear an opposing view.
I take on board your point about the potential risk if the founding family decide to stuff outside shareholders. But to my mind, the fact that they haven't done this so far, means it's a receding risk. I'm hoping they see it as a matter of pride/honour to restore the company's fortunes. Also, it just doesn't need to raise any fresh equity.
in the context of ongoing unknown lossses and large payables figure so i think we will have to agree to disagree here...
That's the key point, that now the shops have re-opened, on cheap turnover rents, it should already be profitable. I wouldn't be interested otherwise. The historic numbers don't matter now, because that was based on old, expensive leases, then periods of lockdown when the shops were closed. I think we probably now have a business that could settle at revenues of maybe £80-100m p.a., and perhaps £5m-ish profits? If I'm right, that would be worth more than £20m market cap.
Regards, Paul.
QUIZ (LON:QUIZ)
Paul
That's the key point, that now the shops have re-opened, on cheap turnover rents, it should already be profitable.
Lets certainly hope so - i always think that as soon as a company are back into confirmed sustainable profits from losses they are likely to let us know sooner rather than later. Not aware they have given us the good news yet - and they certainly have had issues up to about now time - so hopefully not long to wait for confirmation now that your assumptions are correecty. I expect the doomongers may then depart the scene - despite my prior posts i still see the bigger picture that they have in the past shown that when conditions are normal they do know how to run a decently profitable business.
Yes Paul. Thank you so much for your early read on Scs (LON:SCS) and I was in there with you at 0700. Got in near the 0800 bell and bought some more. I agree with you that the message was not all that clear. What company would leave it till well down the report to say that they were forecasting to beat market expectations? More and more companies put that in the headline, never mind the first para!
I have read all the later comments during the day, and I have a few extra points to make which are in no particular order.
There are changes at the top in the management team. I seem to remember listening to a double act webinar where the new incumbent was talking about expanding the range into e.g. outdoor furniture, so maybe there will be expansion beyond the hugely financially successful model we see today. However, such expansions can fail as well as succeed as we have seen elsewhere many times.
I believe I have seen somewhere that SCS production is primarily in this country. That may be advantageous or not in the current situation of supply and inflationary pressures. The raw materials have to come from somewhere, so it may be that the bottleneck is further down the material supply line for SCS than other competitors. However, if international transport is in short supply and very expensive it takes less space to transport materials than finished articles like sofas etc.
The cash pile does stand out like a beacon and with so much M&A activity it must be a real threat - or opportunity, depending on where you are sitting. You Paul, have pointed out the freehold asset backing of companies like Vertu Motors (LON:VTU) and occasionally on much bigger companies like Wm Morrison Supermarkets P L C (LON:MRW) have. The share price did respond, then in come the vultures and the SP heads for the heavens. In a way it is so predictable, assuming that some organisation wants to bid for Scs (LON:SCS) and go through that process. As you say, it could be worth 400p which would be a smaller premium than some of the recent takeover bids we have seen. The one for Meggitt (LON:MGGT) for example after their results and pretty downbeat outlook was breathtaking!
That's it. Thanks again, Paul.
Scs (LON:SCS) (no position)
Hi Ridavies
Adding to your comments on international sourcing, I thought I'd add a comment I read recently from Haverty's, a US-listed/based furniture company.
They're very similar to Scs (LON:SCS) , and here's something that was mentioned in their press release last week:
"Our suppliers have recently paused their manufacturing operations in Vietnam due to COVID-19. These closures, if not resolved in August, may begin to impact our merchandise available for delivery in the fourth quarter."
https://www.havertys.com/furni...
As you say, it looks like SCS get most of their products from the UK and EU, but it's unclear if the supply chain extends to the Far East. I looked at the DFS annual report, which stated that 25% of their goods are sourced from there.
If I'm honest, I don't think this would make a difference to Scs (LON:SCS) - customers will just wait longer and accept that these are different times, though it was an interesting point that isn't really mentioned in the UK listed firms (that I'm aware of.)
Good luck all holders
A
Mark Slater explained many years ago in a talk at the UK Investor Show why he rarely invests in IPOs, presenting data to demonstrate the overall poor performance of these. So, it will be interesting to see if the IPO survival guide is saying anything significantly different and I will definitely look at it.
Either way, given some of the high profile IPO disasters of recent times it should make for interesting reading.
Interesting, that must bode well for Supreme (LON:SUP), which floated in February. Mr Slater holds nearly 5% of the equity.
Hi jonno,
Interesting, that must bode well for Supreme (LON:SUP), which floated in February. Mr Slater holds nearly 5% of the equity.
That's a really good point actually. When I read Admission Documents for new AIM floats (not very often, as there isn't enough time), I sit up and take notice if Marlborough (Canaccord) which is Giles Hargreaves outfit, Slater Investments, and one or two other shrewd funds are taking meaningful stakes. Because they're known for their long-term track records, and depth of research, so effectively they've done a lot of the due diligence for me!
As regards Supreme (LON:SUP) I was really impressed with the energy & entrepreneurship of the CEO on a recent webinar. The CFO seems pretty grounded too, and there was a good dynamic between them - it's easy for an owner/manager to be too dominant, but there seemed a mutual respect between these two.
Accordingly, I've dipped my toe in with a starter size position (about 1% of my portfolio). Probably not likely to be a multibagger, but with a long track record of identifying & executing on money-making product niches, and a founder that still owns c.57% of the company, then I reckon it's more likely to be a long-term winner than a loser.
Someone here did comment that they think the vaping side of the business looks vulnerable, not sure why? In terms of growth, I like the sound of the vitamins & sports nutrition products. The CEO seems to have a talent for spotting lucrative niches, where incumbents are making excessive profit margins, then introducing more competitively priced alternatives & grabbing a decent market share.
I particularly liked his story about how Supreme overcame resistance from retailers to its new vaping product a few years ago - Supreme gave it away free with the initial launch product to Poundland, and said give us a call when you want to re-order! Sure enough, within a couple of days Poundland rang up Supreme to say it was flying off the shelves, and they wanted to re-order! Since then it's become Supreme's best product category I believe.
Regards, Paul.
That just prompted me to flag that Phoenix Copper (LON:PXC), which is not in your natural investment universe, got significant investment from Giles Hargreaves at its placing back in March. It was one of the factors that confirmed to me it was different to the usual AIM mining company. We can all be confident in our own views, but it really helps to see our elders and betters thinking along the same lines.
Might be a bit late to invest in PXC.
Michael Taylor flagged it up in the I.C end of July and it's gone from 53p to 80p in a week!!
Ok for G.H though as I think the placing was at 35p.
Phoenix Copper (LON:PXC) today announced the launch of an ADR programme by end September to give US investors improved access to the shares. No dilution (!)
Edit: Thanks to Donald Pond for bringing this share to our attention back at the end of April. It’s confirmation that there is more to Stocko discussions than just the SCVR.
Phoenix Copper (LON:PXC) The Michael Taylor tip was around 65p, shares went up to 72p and then fell back on the day to around 65p.
Hi Paul, I watched the prelim presentation on Equity Development and was also impressed. I think Supreme (LON:SUP) will do well, but as always in equity investing there are no guarantees. Supreme (LON:SUP) also fits very well with Andrew Hollingworth's view of scale/economy businesses, he cites Weatherspoons and Ryan Air as examples, whereby as the business grows it returns more to the customer in terms of price paid. For me, examples being the price at which Supreme (LON:SUP) is able to profitably retail its wellness and vaping products. Andrew discussed this concept in his recent PIWorld interview with Tamzin.
I have a reasonable starter position in £SUP. Time will tell if Mark Slater is correct. Anyway I am in good company and hopefully Supreme (LON:SUP) will be a successful investment.
Regarding Scs (LON:SCS), I don't hold but will take a good look.
Thank you and Jack for the detailed and very informative write ups. Worth the annual subscription on their own. Well done to Ed and all the team.
All the best
STB have had a lovely first half of the year, interims out today. I'm sure Paul will appreciate the clear profit guidance which is a refreshing change.
Yes Secure Trust Bank (LON:STB) results look superb, still at 15% discount to book value even after recent rise but now delivering 18% return on equity.
Secure Trust Bank (LON:STB) Philip999. Yes - strangely muted Mkt response at the opening
I guess it has risen a lot recently, up around 25% over last month, but still looks good value IMV
My morning smallcap tweet: Sniffing the market's lower end
£OPT SCS (LON:SCS) Restore (LON:RST) Camellia (LON:CAM) Maestrano (LON:MNO)
OptiBiotix Health (OPT) guides H1(June) rev (from LPLDL and SlimBiome) £1.1m, up 44%, ahead of mgmt exp. Effusive outlook. [SP=NA Cap=NA]
ScS (SCS) guides FY21 and 22 ahead of market forecasts. FY(July) order intake LFL down 1.5%. [SP=290 Cap=110m]. I hold.
Restore (RST) writes an essay on why it rejected Marlowe's approach. [SP=500 Cap=683m]
Camellia (CAM) sells Abbey Metal Finishing.No £££. [SP=6800 Cap=188m]
Maestrano (MNO) five-month Proof of Concept (MNO) contract for its LiDAR & AI technology for scanning HS1. "We are confident that once this trial is complete, it will be adopted on a longer-term basis." [SP=11.85 Cap=20m]
No mention of Secure Trust Bank (LON:STB)?
Camellia (LON:CAM) has always intrigued me. Sprawling agriculture group that also did private banking and aerospace components in the past too I believe.
Always an amazing discount to NAV, which is very nicely land-backed, as well as always having a healthy net cash position. But hard to see the catalysts and the CEO and CFO having been in their roles since 2015 are in no rush to unlock value for shareholders...
Interestingly, neither CEO or CFO owns a substantial amount of shares, nor do they have a LTIP or options programme at all! In addition, they only get base pay and not even annual performance cash bonuses. One of the rare few companies where the C-Suite are not incentivised to drive shareholder value?
£ScS positive trading statement. £87.7m cash and no debt. SP sitting on the 50 MA support and MACD Zero so nicely placed.