Small Cap Value Report (Thur 22 Nov 2018) - Howard Marks, FA., CMCX, MTC, Mello/ShareSoc. WYN, KLR

Morning all,
There is a strong supply of updates, so I hope you'll help me with a few suggestions in terms of what to cover today!
Yesterday featured great results from Creightons (LON:CRL), which is now 6% of my portfolio. I am tempted to add more of it, but 6% feels heavy enough for this micro-cap.
I am increasingly bullish on the UK market, seeing as it remains so weak. It's down another 1% today, and Stockopedia's median forecast P/E ratio for UK stocks (one of my favourite macro indicators) is just 12x. That number tells me there must be plenty of value opportunities, and I've been trying to find fresh candidates for the portfolio.
In addition to Rightmove (LON:RMV) (added earlier this month), I've also added B.P. Marsh & Partners (LON:BPM), the insurance investment vehicle, to my portfolio. I'd like to be more active in the insurance space - there are plenty of interesting and overlooked candidates in the sector. For example, the FTSE 250 component Lancashire Holdings (LON:LRE) is completely ignored by most investors.
Anyway, given my view on equities, I'm nudging up my portfolio allocation and becoming more and more "risk-on". My portfolio is now 82% equities, 14% bonds and 4% cash.
For the Howard Marks fans in the audience, I'd recommend this YouTube video published last week by his company.
It's a 25-minute interview outlining his overall views on macro topics. He is quite cautious about the 10-year US "recovery", thinking that we must be closer to the end of the good times than the beginning. But he also acknowledges that US equities have been growing into their expensive valuations over the past year (the stock market hasn't budged while earnings have been growing very fast).
Other points from the interview:
- Private assets have more attractive pricing than public assets. All publicly-traded assets are expensive.
- The crypto boom is mostly based on people hoping to find greater fools to sell their coins to (but I would note that hardcore crypto advocates don't fall into this trap).
- ETFs may provide the illusion of liquidity where the underlying holdings are illiquid, e.g. junk bond ETFs. He asks the question: if junk bonds are illiquid, then where does the liquidity of their ETFs come from? He warns us that this liquidity is going to prove illusory in a time of crisis. (I would agree and would suggest that these ETFs will trade a discount to official NAV in a time of crisis. I hold IS SHRT DUR HY CRP BD USD (DIST) ETF (LON:SDHG).)
Now let's take a look at some company updates.
Today I am looking at:
- Fireangel Safety Technology (LON: FA.)
- CMC Markets (LON:CMCX)
- Mothercare (LON:MTC)
- Wynnstay (LON:WYN)
- Keller (LON:KLR)
Fireangel Safety Technology (LON:FA.)
- Share price: 33.5p (-25%)
- No. of shares: 46 million
- Market cap: £15 million
The saga of disappointment at Fireangel/Sprue Aegis continues. Some of you will remember when the share price was north of 300p.
This profit warning is related to a delay and higher short-term costs of production at FA's manufacturing partner.
This is a new partner, after the relationship with the previous one ended in disaster.
There was also a delay in core product sales recovering to "acceptable" levels. So results for 2018 will be materially below expectations.
New legislation in Scotland in H1 2019 is expected to increase demand. Fair enough. UK and German sales have recovered to some extent and so we get some reassurance for the 2019 result:
"A number of other large connected proposition tenders and legislation driven opportunities are now expected to make a positive impact during the first half of 2019 thereby underpinning the Board's expected recovery to profitability in line with market expectations."
My view
If what the update says is true, then today's 25% sell-off is overdone.
The problem is that there have been so many false dawns. It's worrying that a fire alarm company can be so accident-prone!
We also need to bring the right amount of scepticism toward its plan to shift from the traditional hardware-based business model to the "connected homes" provider it wants to be.
I'm not motivated to study it in any great detail, as I'm not convinced that it has an enduring competitive advantage and I have no faith that it will execute its plans.
The balance sheet has equity of £25 million (June 2018) but £18 million of this is intangible. So it's still too soon to rush in for a value investing opportunity, I fear.
CMC Markets (LON:CMCX)
- Share price: 115p (-3%)
- No. of shares: 291 million
- Market cap: £336 million
A mixed bag of headlines for CMC, the spread betting/CFD provider. Its arch-rival IG Group (LON:IGG) remains an important holding for me.
Key points:
- H1 operating profit has collapsed by 74% to £8 million. This is caused by the operational leverage inherent in needing to pay for c. £60 million of operating expenses.
- More meaningfully, net trading income fell by 18% to £70.6 million. The company is trading in line with guidance for a c. 20% reduction in CFD/spreadbet net revenue.
Times have been tough for spread bet firms with range-bound markets and the new ESMA regulations on leverage (since August).
While it's still too early to determine exactly how retail clients will react to these rules, CMC says "the most common behaviour to date has been for clients to continue trading but with lower exposure and trading activity".
Expenses rose by 6%. This is understandable seeing as new business lines are being opened, particularly in Australia.
My view
I view this share as underpriced. It has many of the same attractive financial characteristics as IG Group in terms of cash generation, return on capital and a strong balance sheet. It also has a Value Rank of 91, and you can hopefully see why:
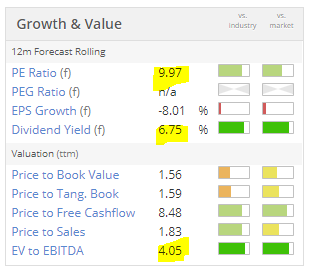
For me personally, I have enough exposure to this sector already, so I don't feel I need any more. On top of that, I like to buy the #1 company in any segment rather than the #2 or #3. But I do admire CMC, and I agree with Stockopedia that it's underpriced.
It passes five screens, although one of these is a short-selling screen based on earnings downgrades.
Mothercare (LON:MTC)
- Share price: 16.4p (-7%)
- No. of shares: 342 million
- Market cap: £56 million
This struggling retailer had a fundraising at 19p and a CVA earlier this year. Let's catch up to date with trading to early October:
- UK like-for-like sales down 11%. "Wider market uncertainty" (?) is blamed, along with negative media coverage around the refinancing.
- Total revenue down 13%, adjusted EBITDA down 60% to £5 million
- Pre-tax loss of £14.4 million (H1 last year: pre-tax loss of £16.8 million)
- net debt £21.5 million
Key points about the transformation plan/CVA:
- fewer than 80 stores left by April 2019
- 32 of the remaining stores will have leases expiring within three years (that's still nearly 50 stores beyond three years - doesn't seem very encouraging to me).
- Head Office to be made leaner. Dreaded "consultation exercise" with employees.
- £19 million p.a. cost savings to be exceeded.
My view
Perhaps some clever financial modelling could forecast that this company is going to get back into profit before long. But does anybody think that the Mothercare brand is of much value to consumers? Do parents really want to pay more for goods in a Mothercare shop, instead of getting a similar item at a cheaper price elsewhere?
Another way of looking at it would be: if Mothercare didn't exist, would anybody want to create it? I think the answer is no, at least not in its current form. If someone wanted to create a premium brand in this niche from scratch, they would almost certainly make it an online-only brand, and not bother with any physical stores.
When it comes to Mothercare's UK online sales, trends are negative there, too. While negative press coverage may have contributed to that, an 8% fall is still very disheartening.
Even if the restructuring gets the company a positive performance for a couple of years, I don't see it surviving in its current form for the long-term and I expect that existing leases will continue to drag on performance.
Away from the UK, the international operations are doing much better, using a Franchise model. If there is a bullish case to be made for the stock, maybe it rests on the international business.
It has staved off bankruptcy for the short-term so congratulations to it for that. And good luck to shareholders. At the end of the day, I just don't see a lot of value in the brand. So I'd steer clear unless the enterprise value (currently c. £80 million) looked very cheap against prospective earnings.
Mello London / ShareSoc MasterClass
Just a few days left until Mello London and the ShareSoc Masterclass. I'm looking forward to meeting many of you at these events over Monday and Tuesday.
Of course not everyone can make it due to work commitments, geography, etc. but they should be good fun and insightful/educational for everyone.
The Masterclass will include Professor Glen Arnold, Maynard Paton, Leon Boros (and me!), and will be chaired by Gareth Evans (founder and MD of Progressive Equity Research). You'll have lots of time to ask us difficult questions and see us debate various things. And it's for a good cause - it helps to fund ShareSoc's activities throughout the year.
The main event will include presentations by our very own Paul Scott and Ed Croft, Glen Arnold, Lord Lee, Keith Ashworth-Lord, Gervais Williams, and loads of company CEOs. It's Mecca for investors, basically.
Also, if you're around on Sunday evening, there will be dinner and a quiz with Lord Lee. What more could you ask for!
Wynnstay (LON:WYN)
- Share price: 411p (+2%)
- No. of shares:
- Market price:
The Board of Wynnstay, the agricultural supplies group, is pleased to provide the following update on trading for the financial year ended 31 October 2018.
Agricultural supplies... now I know why this name is unfamiliar to me.
Let's see what it does.
Agriculture
- Feeds - animal nutrition.
- Fertiliser
- Seeds
- Agrochemicals
Specialist Retail
- Rural retail outlets
I immediately know that this isn't something I'm going to be spending a huge amount of time - not my area of expertise, and in any case it looks fully commoditised.
There is good news: the company is trading ahead of current market forecasts. Agricultural output prices are up, boosting the mood for Wynnstay's customer base. Dry summer weather also helped to increase the demand for feed products.
Checking the archives, Paul said last year last year that he thought a P/E ratio of c. 9x would be appropriate for this company (the share price then was 572p).
With the share price now at 411p and earnings having improved, the P/E ratio has reduced to 10.7x.
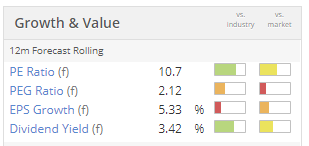
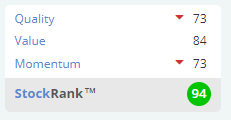
It's not for me purely for sector reasons. It could be of interest to those with sector expertise or using a StockRank strategy:
Keller (LON:KLR)
- Share price: 603p (-3%)
- No. of shares: 72 million
- Market cap: £434 million
Things at Keller are proceeding in line with expectations.
What does it do?
Our products are used across the construction sector in infrastructure, industrial, commercial residential and environmental projects.
You can go here for a list of its areas of expertise. Today's update informs us that it is abandoning certain activities in Singapore and Malaysia.
It had net debt in June of some £367 million, following an acquisition. So the enterprise value is £800 million.
There is or has been some customer or project concentration:
In EMEA, our businesses have performed in line with expectations, demonstrating year on year profitable growth, excluding the reducing beneficial effect from the significant projects in the Middle East and the Caspian
I don't get involved in this type of business - construction/engineering support services. But again, as with Wynnstay, I can see some attractions. It is "cheap".
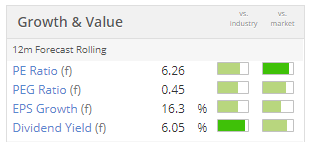
The quality score is not too impressive, e.g. operating margin was only 5.8% last year. So I will leave this one for others to research in greater detail.
All done for today, thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Graham,
There's actually a more recent and IMHO better interview with Howard Marks at UCLA here:
https://www.youtube.com/watch?v=6ATUoZ6qjpIre
Just like his memos are required reading, this is essential viewing for all investors, particularly those who get over-excited when the market goes up and suicidal when it goes down :-)
All the best, Si
Graham
With reference to you comments about insurance orientated equities you might want to look at Randall & Quilter Investment Holdings (LON:RQIH). It has recently completed a strategic revamp and looks an interesting and potentially rewarding investment. Like many small cap stocks the share price has fallen back close to 20% recently and is worth a look. I hold.
There are some useful reviews from Equity Development and the Capital Access Group available on Research Tree.
don't like to say it but i think mothercare gunna go same way as woolworths did,,times are changing. i remember when we had man come round renting vhs film tapes once aweek,,also the lemonade drinks man.. wow i feel old lol,, but i guess need to move with the times. even if sad
I'd have big reservations about including a global general insurer such as Lancashire Holdings (LON:LRE) in a list of undervalued UK stocks. The insurance cycle is pretty independent of the UK economy. Look at US hurricanes and wildfires for a better measure.
Isn't that a good thing, John? Weak correlation with pretty much everything else in the index.
Graham - yes, in the context of 'uncorrelated assets', it is. But thinking more of the UK economy and looking for catch-up opportunities?
I'm periodically tempted by housebuilders such as Taylor Wimpey (LON:TW.) with its yield, but then remember falling house prices, rising interest rates, etc. and hold off for another day!
As a relatively new parent I can't speak highly enough about £:MTC . We have always found the staff to be brilliant and they took a great interest in us and our story (we've adopted a girl). When it comes to things such as buying prams, doing it in person really does make a difference. You can "test drive" the pram if you like in store and get clear demonstrations on how to set things up and pack things. Believe me physical demonstrations are much easier than trying to under videos online. Also seeing things in person is much better for making a choice on what is right for your child.
Staff have also been brilliant and come to help us with the child seat on a non-purchase visit too.
Compare Mothercare to the Mamas and Papas (which are next door to each other near us) and it is clear that Mothercare is better on price and range.
Admittedly knowing that Mothercare was in financial trouble made me want to shop there more. In spite of what Graham says I don't think there is anything close to it on the high street and I would feel really bad for all parents if it disappeared.
I read recently that consensus US EPS for 2019 had been reduced by 9%. If that were correct, then maybe one should not have too much confidence in UK consensus for next year as small cap in particular do not appear to have many revisions between announcements.
Re: Mello
I am very much looking forward to attending this year and meeting other fellow PI's there. And I'll be presenting the Investor Sentiment research findings at 14.20 on the Tuesday - do come along if you can and say hello. If not, I'll write-up the report and post it shortly afterwards here.
cheers
Francis
Wynnstay is in a business with no moat, and in which no one makes any money. I used to compete with them and the whole industry is pitiful
Yes bobo, anyone with a barn and an HGV licence can set up in this game. We should also remember that Wynnstay (LON:WYN) (and NWF (LON:NWF) ) are essentially retailers, that is members of an unloved and arguably receding sector. Both also depend for their business on farmers and the horsey set. The former may well yet be negatively impacted by the UK leaving the EU. This might be an area to stay away from for now.
Thanks for another good report Graham. I always enjoy your understated humour - "It's worrying that a fire alarm company can be so accident-prone!"
On another note, at 9am this morning Patisserie Holdings (LON:CAKE) "
Subsequent edit: I also just stumbled across this interesting article about On The Beach (LON:OTB) ambitions for growing its staff which is a good sign of the current confidence of the business: https://www.ttgmedia.com/news/...
I hold and am off the view it looks attractively priced at the moment after a bit of a sell-off in a lot of travel stocks due to some reporting falls in revenue due to the warmer weather and football during the summer.
Rec Mothercare (LON:MTC)
We are expecting our second child and my wife looked at Mothercare but found the same products much more expensive than other retailers.
Amazon and most other stores you can get the same product but 10-20% cheaper, so am not surprised they are seeing such a sales decline.
Hi Graham - a large reaction to the FW Thorpe (LON:TFW) trading update. I do not hold but follow given its a well run biz that has a good following amongst private investors. worth a look?
Hi Graham - Thanks for the update...
Do you know why B.P. Marsh & Partners (LON:BPM) doesn't have any stock rank or ranking in universe etc in the stock report?
Maybe this is one for me to ask support about...
It's classified as an Investment Trust, so no StockRank.
timarr
Graham any chance of looking at Mothercare? Interesting to see if a CVA can fix an old brand, doesn't seem so yet but bound to have been impacted by noise around recapitalisation
Had a look at MTC. thanks HB!
I think the impact on Mothercare is as much about staff morale as customers reading about them in the papers. My daughter had jaw-droppingly bad service in her local store trying to buy a child car seat. They didn't want to fit it because it was drizzling outside.
When you are writing about CMC Markets (LON:CMCX) I wonder if you could include any additional thoughts on Plus500 (LON:PLUS) from their update earlier this week - they seem to be doing rather better than CMC Markets (LON:CMCX) unless I am perhaps comparing apples with oranges
Hi andrea, the Plus500 (LON:PLUS) update didn't have much content so not much to say about that. I haven't changed my mind about it - I'd see it as a v. dangerous investment in comparison to IG Group (LON:IGG) and CMC Markets (LON:CMCX).
Hi Graham,
What's your opinion of Wynnstay - seems lowly rated, quality stock and moving in the right direction.
Michael
Hi Michael, I'll check that out after lunch (along with £KLR). cheers!
Hi Graham,
Did you get the opportunity to look @ Keller (LON:KLR) trading update - appreciate you have plenty of requests so cannot always get round to everything!
Hi AC. Yes, I have managed to put together a few poorly-informed comments on Keller (LON:KLR). Happy to be educated on its merits! G
Thanks Graham - not sure there are any at the moment! Performance of Keller (LON:KLR) would seem to be one more nail in the coffin for my version of NAPS this year! I didn't go for Plus500 (LON:PLUS) (really does look too good to be true!) and Volvere (LON:VLE) (a favourite of yours I believe) and the performance of these two stocks (along with Drax (LON:DRX) to lesser extent) have reduced Ed's NAPs/SNAPs portfolio selection % losses by a significant margin.
It's worth noting that Howard Marks video was recorded on July 18th even though his firm just put it up on their website.
After profit warning and 30% + fall in share price earlier this year is Keller (LON:KLR) (one of Ed’s SNAPS and in Roland Head’s SIF portfolio)) now in small cap orbit? If so be would be interested in views on today’s trading update. Looks like a major retrenchment across the business with job losses, exit from loss making ASEAN business, contract problems in USA ,a successful refinancing and a mixed outlook. All in all looks like a much reduced business going forward and lens support to Stockopedia profit warning guide - get out at first sign of trouble!
Morning Graham
Just wondering if you have any further thoughts on yesterday's interims from Creightons (LON:CRL) to add to Paul's commentary on the results.
re: Creightons (LON:CRL)
Morning jonno, I don't have anything to add on that front. Thanks for suggesting anyway. G
Jonno. piworld will be publishing the H1 results presentation by Creightons (LON:CRL) in the next few days. Worth watching, so you can reach your own conclusions. All sounded very positive in their world, and they run with a lot of common sense - which is always commendable, IMO!
My morning smallcap tweet: Bad news from 5 smallcaps in a bumper report.
Fireangel Safety Technology (LON:FA.), Integumen (LON:SKIN), Juridica Investments (LON:JIL), PCI- PAL (LON:PCIP), Hornby (LON:HRN), Veltyco (LON:VLTY), Mothercare (LON:MTC), Ebiquity (LON:EBQ), Wynnstay (LON:WYN), Redcentric (LON:RCN)
FireAngel Safety Technology (FA.) FY trading. Another warning. Ongoing production mproblems has delayed supplies and added short-term costs. Also "core product sales within the Company's UK retail and German trade segments have only recently, during Q4 2018, recovered to acceptable levels." Brave face. Uninvestable.
Integumen (SKIN) Subscription and Placing to raise £355k at 0.44p, a 14% discount.
Juridica (JIL) proosed delisting to save money during fund wind-up. I hold.
PCI-PAL (PCIP) agrees to pay sacked CEO his contracted entitlements plus £100,100 in full and final settlement of all other claims.
Hornby (HRN) poor H1, current sales are behind budget. squeezing costs. H1 rev down 18%, U/L pretax -£3m (-£4.6m). "There is still a large amount of stock at retailers that was sold at aggressively discounted prices. Some of the large blocks of stock of "bread-and-butter" items that were sold represented more than a year's supply for our entire market." Brave face: "There are some incredible [really?] products in the pipeline that will finally get us back on the front foot and give us the ability to take back the market share that we have given away."
Veltyco Group (VLTY) continues to struggle with cash collection in the online financial trading marketing vertical, has reduced marketing activities in this vertical to zero. May write down receivables. Cash only €0.6m. "If the Company is unable to increase its overall cash position, its ability to provide the level of marketing spend to support the launch of its own regulated online financial trading brand...in December."
Mothercare (MTC) H1 adj pretax -£6.2m (-£2.6m). "UK like-for-like sales decline of 11.1%, reflecting wider market uncertainty and negative brand coverage in connection with the Group's refinancing." There's been no trading stmt for 4 months! Expects performance to remain volatile.
Ebiquity (EBQ) guides FY operating profit materially below current market expectations.
Wynnstay Group (WYN) guides FY profit head of market forecasts.
Redcentric (RCN) H1 rev down 8%. Reinstates div 0.4p. "Our contract win rates have been lower than expected and the quality of the new business pipeline has reduced. While our new sales director, Brendan Lynch, has made good initial progress in implementing the required changes, it is taking time to rebuild a high-quality sales function." Also "Health & Social Care Network contracts...not expected to deliver the anticipated revenues in the timeframe previously expected." What a load of waffle to say sales are slow.
Waffle indeed at that point from Redcentric (LON:RCN) but they were a little more to the point on sacking the CEO:
"The results announcement today, whilst showing Redcentric's resilience, does not demonstrate progress with regard to sales, delivery and execution. The Board has therefore decided that Redcentric's growth ambitions would be better served with a change of leadership. We have therefore taken the decision that Chris Jagusz will leave us forthwith. We would like to thank Chris for his efforts".
Charles Stanley (LON:CAY) H1 results today. From the RNS, 'solid set of results' ... 'turnaround strategy starting to bear fruit' ... 'fully committed to our vision of transforming CAY into the UK's leading wealth manager.'
Here's the CEO and CFOs giving an overview on what's been achieved, and what they hope to achieve going forward.
https://www.piworld.co.uk/2018/11/22/charles-stanley-cay-interim-results-november-2018/
Morning all,
I couldn't sleep, so got up at 4:30am and wrote up a new section on recent results from GAME Digital (LON:GMD) - which can now be found at the end of yesterday's report here.
Readers have been nagging me about this for a while, so am glad to have belatedly got it done!
Best wishes, Paul.
Thanks Paul
I’m one of the readers grateful for your GAME Digital (LON:GMD) thoughts.
Jon