Small Cap Value Report (Tue 6 July 2021) - CHH, GTLY, IKA, PURP, ALFA, KINO

Good morning, it's Paul & Jack here with Tuesday's SCVR.
Timing - today's report is now finished.
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Churchill China (LON:CHH) - continued good trading, it's back to pre-pandemic 2019 revenue levels in both May & June 2021. Could this be benefiting from pent-up demand as restaurants re-open, and is it sustainable? Valuation fully factors in recovery, so where's the upside from here?
Gateley Holdings (LON:GTLY) - accounts delayed a week. Strange trading update, which doesn't confirm market guidance for FY 04/2021, but instead strangely refers to FY 04/2022 performance. I think this could be a typo. Have lodged a query with the company, and its broker. I'll update here if they respond.
Ilika (LON:IKA) - a quick, and fairly pointless look at the accounts for FY 04/2021. It's blue sky, and valued at £248m, so not something I can meaningfully analyse.
Purplebricks (LON:PURP) - quick review of results for FY 04/2021. This is starting to look interesting again, in my view.
Here are recordings of a couple of recent webinars which I found particularly interesting (no sections below, these are standalone) -
Cake Box Holdings (LON:CBOX) - FY results webinar from last week. I'm impressed with entrepreneurial management & the business model. A bit pricey now though. On my watch list, and I might buy on any weakness in future -
.
Studio Retail (LON:STU) (I hold) - excellent results, and it looks stunningly cheap (PER of less than 7!). Could soar if management succeeds in growth plans. Mike Ashley's Frasers stake is an overhang, so I suspect this Capital Markets Day (CMD) was to drum up some buying interest. I'm still researching this, but might add to my position next week. Andy Brough of Schroders likes it, and is second largest shareholder -
.
Jack's Section:
Alfa Financial Software Holdings (LON:ALFA) - shareholders got hurt here in an overvalued IPO back in 2017. The top 10 shareholders own around 82% and the spread is sizable for such a big company, but trading momentum is encouraging and a Quality Rank of 99 suggests Alfa might be worth a fresh look.
Kinovo (LON:KINO) - Formerly known as Bilby. Illiquid, risky micro cap in turnaround mode, but a market cap of c£22m on annual revenue of more than £60m suggests that the shares could rerate at some point if management can execute.
Paul’s Section
Churchill China (LON:CHH)
1712p (last night’s close) - mkt cap £189m
Half Year Trading Update & Interim Dividend
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to provide an update in relation to trading for the six months ended 30 June 2021.
My summary of today’s update -
- Improved trading previously reported at AGM on 1 June 2021
- Maintained in June trading - both May & June 2021 recovered to pre-pandemic revenues of 2019
- Good forward order book (no figures provided)
- “Degree of uncertainty” due to covid
- Interim dividend of 6.7p declared
- Job Retention Scheme (furlough) monies have been repaid - bravo!
- Diary date - H1 results (6m to June 2021) due out on 1 Sept 2021
My opinion - I’m quite surprised it has recovered to 2019 level of revenues already, given that the customers are in the hospitality sector. There have been so many (permanent) restaurant closures in the UK, from CVAs, etc.
TGI Fridays (I hold, via Electra Private Equity (LON:ELTA) ) said in a recent webinar that 18% of Italian-style restaurants (the worst hit niche) in the UK had closed, mainly due to restructuring/insolvency of some large chains. With so much capacity gone, I would have expected CHH to have only partially recovered. There again, with restaurants re-opening, perhaps there is pent-up demand? So my worry here would be that the initial demand might ebb later this year, possibly?
Although anecdotally, I’ve noticed that some closed-down restaurants seem to have shopfitters in remarkably quickly, and some have already re-opened under new owners, in a new format. The attraction is that a fully-fitted out restaurant is an attractive option to new tenants, as they don’t need to spend much to refresh the site. The main items (kitchen equipment) is already there. On lower rents, and probably with a rent-free period too, the new operator of empty restaurants stand a fighting chance, and have a competitive advantage (lower costs) compared with existing competitors that survived the pandemic, but have higher fixed costs now (if they’ve been unable to negotiate a reduced rent).
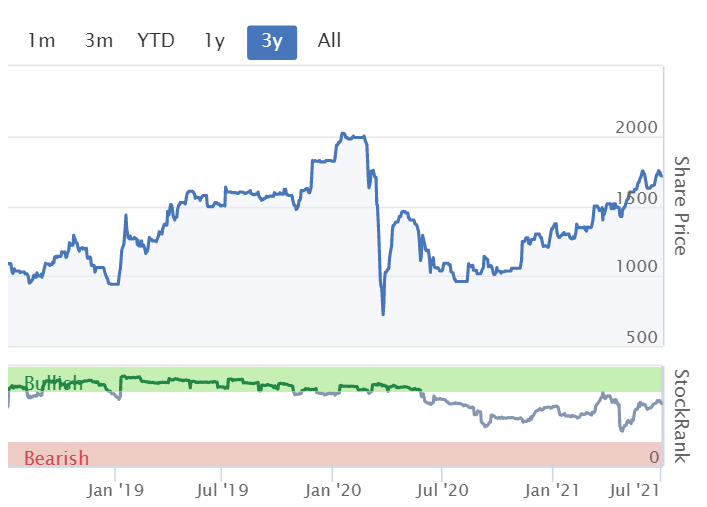
So the main question is, will CHH be able to sustainably get back to 70-80p peak pre-pandemic earnings? Maybe, maybe not, I don’t know. At 1712p share price, the PER is nearly 23 times 75p peak earnings, and the company probably won’t get to that level of earnings in 2021, but possibly could in 2022. That’s what broker consensus currently stands at: 37.7p in 2021, and 75.8p in 2022.
Personally, I can’t see the attraction, as recovery is now fully priced-in. So where’s the upside for me, if I pay full price now?
.
.
Gateley Holdings (LON:GTLY)
220p (unchanged, at 09:13) - mkt cap £259m
Gateley (AIM: GTLY), the legal and professional services group…
Today’s update seems rather confusing, and I wonder if it might contain a typo? Not what you expect from a firm of lawyers! To unpick it, you first need to read the upbeat pre-close trading update dated 26 May 2021, which relates to FY 04/2021.
That update indicated a diary date of 13 July 2021 for the FY 04/2021 final results.
Today we are told this has been pushed back a week to 20 July 2021.
Fair enough, I don’t think that’s a disaster - some companies are having problems with getting audits done in time, although no reason is given today by GTLY as to why the accounts are going to be a week late.
Note that the company previously announced a cyber-attack here on 16 June 2021 indicating that the incident was small, and had been dealt with. Maybe that distracted management and caused the week’s delay to the accounts?
The next paragraph of today’s update is confusing. It starts by saying -
As previously announced on 28 May 2021, the Group entered the second half of the year with high activity levels, strong trading momentum and a sense of optimism and confidence…
[Paul: the announcement was actually on 26 May, not 28 May, that's a typo]
Why refer to the start of H2 (which has now finished, H2 being the 6 months from Nov 2020 to Apr 2021)?
Looking back to the update on 26 May 2021, it gave chapter & verse on how the group had performed in FY 04/2021 -
Revenue for FY21 will be not less than £120m (FY20: £109.8m), an increase of more than 9.3% for the year as a whole. Prudent cost and cash management measures, initiated by the Board at the start of the pandemic and augmented by the stronger than anticipated H2 trading, have yielded a net cash position at 30 April 2021 of £20m, significantly ahead of management's previous expectations. The Group expects to report FY21 profit before tax of not less than £16.0m, compared with £14.8m for FY20, an increase of not less than 8.1%.
[ from 26 May 2021 pre-close trading update]
None of this is mentioned in today’s update. When accounts are delayed, I would expect the announcement to confirm previous guidance, which today’s announcement does not.
Instead, bizarrely, it confirms performance against market expectations for the current, new financial year, ending 30 April 2022 -
The Board confirms that the Group is on track to meet market expectations for the year ending 30 April 2022.
[Paul: possible typo no.2? Did they mean 2021? Since clarified, no this is not a typo]
My opinion - as it stands, this announcement doesn’t make sense to me.
I suspect there might be 2 typos, in that it should say 2021, not 2022 in the quote immediately above, and the reference to a previous announcement has the wrong date. Update - advisers have confirmed to me it's not a typo, and is intended to communicate that the new financial year is trading in line with expectations.
Accordingly, I’ve left a message on the voicemail of the Head of Investor Relations, Nick Smith, pointing out that the context suggests it should read 2021, not 2022. I've also flagged my query to the broker.
If they reply, I’ll update this piece (see below). For the moment though, it looks confusing, and probably a typo. If it’s not a typo, then it would be a concern, as it would seem that the company might be glossing over a potentially bigger problem, if it cannot confirm that FY 04/2021 is in line with expectations, which importantly as it stands, today’s announcement does not. They’re lawyers, so should be getting these things right.
Hence an important outstanding query exists here.
UPDATE: I've spoken to the company's advisers, who say the announcement intended to communicate that the guidance given on 26 May 2021 still stands. If so, why didn't the company just say so?! Also the final sentence was intended to communicate that current trading is in line with expectations (so the 04/2022 is not a typo).
I've suggested that the company re-issues today's update, with the RNS date corrected, and also a clearer explanation of guidance for both FY 04/2021, and FY 04/2022.
UPDATE: (7 July) - just checked my voicemail, and the company did indeed return my call, thanks for that. They also confirmed that the reference to FY 04/2022 was deliberate, and not a typo, they wanted to convey that current trading is going well, and in line with expectations.
.
Ilika (LON:IKA)
200p - mkt cap £278m
It’s fairly pointless getting a value/GARP investor like me to look at the accounts of a blue sky speculative share like Ilika.
Ilika (AIM: IKA), a pioneer in solid-state battery technology, announces its full-year results for the year ended 30 April 2021.
It’s more of the same in terms of numbers -

The loss after tax is not included in the highlights, but is £(3.5)m. I’m happy to use after-tax figures for companies which receive R&D tax credits, as that’s a genuine income.
Of the £2.3m revenues, 90% came from grants. The other income stream historically has been paid-for research for third parties, rather than selling products, which it has not yet got round to on any meaningful scale.
Therefore the £278m market cap rests entirely on hopes for future commercialisation of its research projects. There’s not really anything I have to say about that, as I’m a numbers man, not a technical specialist in battery technology.
Manufacturing facility - is in the pipeline, but they’re only talking about scaling up production by 70x. Given that existing production is very low, then that’s not exciting at all. The commentary does drop a few big names, in terms of collaborations, framework agreements, etc.
Goliath car batteries are still at prototype stage. We’re told more funding may be needed to progress that.
My opinion - with a £278m market cap, and a sexy story in a very topical area, I would encourage management at Ilika to absolutely go for it - do a huge placing of say £100m, and really get on the radar. Float on NASDAQ maybe, through a SPAC?!
There must be loads of companies doing similar work all over the world, in battery technology. In my view, the UK is very good at early stage innovation, but not very good at commercialising things.
Good luck to Ilika, but for me this share would be nothing more than a punt, hence is not of interest. I think investors need sector-specific technical knowledge to meaningfully assess the chances of success or failure. Very few blue sky shares like this succeed in the long term, but can be great speculative things in a bull market like the one we have now! Whatever floats your boat.
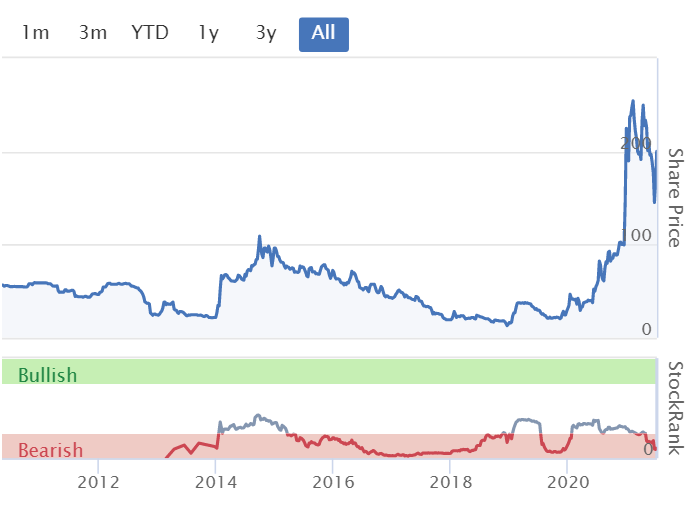
There have been 2 false dawns before, as you can see from the long-term chart below. Same management, same strategy.
.
.
Purplebricks (LON:PURP)
85.5p (roughly flat, at 11:46) - mkt cap £261m
Purplebricks Group plc (AIM: PURP), the UK's leading tech-led estate agency business, announces its results for the year ended 30 April 2021 ("FY21") and provides an update on its strategy execution.
Just a quick look at this today.
The business has been simplified now, with disposals of overseas operations, so it’s just UK now.
Financial highlights look strong, but will have benefited from the Govt stimulus to the housing market (e.g. Stamp Duty holiday)
Revenue up 13% to £90.9m
Adj EBITDA up 314% to £12.0m, although I don’t know how real that figure is, I tend to ignore EBITDA for companies like this.
Footnote 8 is important to take into account, as this is where half the operating profit came from -
Operating profit of £8.2m (FY20: loss £5.7m), including a benefit of £4.3m from non-trading items8
8 These non-trading items are a share-based payment credit of £2.3m and gains of £2.0m on deemed disposal relating to the investment in Homeday and are discussed in the financial review.
Repaid £1.0m furlough monies, which personally I like, but there are other opinions
Cash pile is strikingly high (originating from the disposal of the overseas businesses), at £74.0m, that’s 28% of the market cap, so is important. But what will they do with the cash pile, and will it add, or destroy value?
Probably the most important strategic change is to the pricing model. A new money back guarantee (on non-sale of a property) has been successfully trialled, and is being rolled out shortly. That addresses the main criticism of PURP’s business model previously - that it left behind a long tail of dissatisfied customers who paid a fee for effectively nothing. Also previously it meant that PURP had no financial incentive to actually sell anything!
Outlook - lots of detail, but the most important bits say -
Our current expectation is for FY22 EBITDA to be flat year-on-year, in line with market expectations9, with these strategies expected to accelerate revenue growth and drive progress towards the Group's medium-term targets over the next few years. Once these initiatives have been successfully rolled out, the Group will accelerate its marketing strategy to grow instructions and share. As a result of these strategic changes, the Board expects Purplebricks to be able to deliver annual revenue growth in excess of 20% in the medium-term, with confidence in the Group's ability to deliver against its growth strategy.
9 See Company compiled consensus on the investor website https://www.purplebricksplc.com/investors/analyst-and-consensus/
Link to watch replay of results presentation is here.
My opinion - this is starting to look potentially interesting again.
.
Jack’s section
Alfa Financial Software Holdings (LON:ALFA)
Share price: 139p (pre-open)
Shares in issue: 300,000,000
Market cap: £417m
Alfa Financial Software is a developer of mission-critical software for the asset finance industry. Its main software is Alfa Systems, which allows auto, equipment, and wholesale finance businesses to manage their loans and leases.
It floated back in 2017 at far higher levels than we see today but came unstuck with a profit warning, which Alfa attributed to ‘broader macro uncertainty’. In truth it looks to have been significantly overvalued (an overvalued IPO? Who’d’ve thought.) with a market cap north of £1.2bn on revenue of £73m and adjusted EBIT of £33m.
The share price tumbled by more than 75% and you can see from the chart below there was a significant amount of shareholder churn as the story came undone.
Since then it’s been a thankless ride for shareholders, although it has to be said that the trend looks more encouraging in recent months (albeit on relatively low volumes).

Our revenue expectations for H1 remain unchanged, however the increased contractual cover for the second half as a result of these recent contract wins, along with further statements of work for existing customers, means that our revenue expectations for the second half have increased.
The group now expects revenues for the full year to be c5% higher than previous expectations, with most of that benefiting operating profit performance and should surpass 2020 underlying revenues (excluding one-off licence income).
Full contract packs have been signed with three prospects since its last update:
- One contract is for a new Alfa implementation for a large European automotive OEM;
- One is for a new Alfa wholesale finance implementation for a large US automotive dealer services customer; and
- One is for an upgrade from Alfa Systems v4 to v5 for a UK merchant bank.
The group has another seven prospects in its late-stage pipeline.
Alfa is changing the way it reports revenue to better reflect changing client trends. Going forward it will report across three categories:
Software - 25% of FY20 revenue - sales from selling or developing software for new or existing customers. Will include the software perpetual licence revenue along with revenue from any development efforts required to customise the software and any maintenance or development fees for the period during which the Alfa software is being implemented.
Subscription - 23% of FY20 revenue - includes charges to clients on a subscription basis. This is recurring revenue and includes all revenue charged on a subscription basis.
Services - 52% of FY20 revenue - professional services to implement software for clients. Will include all other sources of revenue, principally based on charging clients on a day rate basis for professional services.
Conclusion
The shares are tightly held. Alfa’s major shareholder is CHP with 66%. This is actually the maker of Alfa Systems and directors include the exec chairman and CEO of Alfa (credit here goes to subscribers’ investigative work in a 2020 SCVR).
This goes some way to explaining the sparse director buying - although there has been one recent £20k transaction at close to today’s pre-open.
The Quality Rank is 99 here, which is usually a sign that there is something worth investigating. Of course, past disappointments must also be considered.

There has been no equity dilution since listing and, while net cash looks to have gone down, that’s more a reflection of the IFRS change in lease accounting than any actual increase in debt. The fall in cash appears to have come from a bumper £44m special dividend payment made in 2020 (15p per share).
That’s more than 10% of today’s pre-open share price and must go some way to restoring goodwill. All in all, this could be worth a deeper analysis. The price looks far more appropriate today than it did a couple of years ago but it’s always worth bearing in mind shareholders have been badly burned here in the past.
This is another stock with conservative looking broker forecasts that are getting nudged up. Alfa is on course to surpass FY20 revenue minus one-off license income, which was £73.3m. I’m not sure why brokers are expecting such a sharp drop in profit margin.
There could be a very good reason for that, but if we assume for a second that Alfa matches the FY20 margin of 26%, then that would make for £19m of net profit or 6.3p of earnings and a forecast PE ratio of 22x. Again, I don’t know if that will happen, but the actual forecast PE ratio is 42.8x, which to me suggests at least the possibility of further upgrades.
Kinovo (LON:KINO)
Share price: 36.5p (-3.95%)
Shares in issue: 61,214,703
Market cap: £22.3m
You might know this one by its former name of Bilby. It’s a specialist property services group that delivers compliance and sustainability solutions, with a focus on home and workplace regulation, regeneration, and renewables.
A couple of years back, Bilby came unstuck after chasing large, low-margin contracts. Since then a new management team has been installed, spearheaded by David Bullen, and we are beginning to see signs of a resurgence in the stock price with renewed buying activity.

This is a micro cap, just £22m or so, and the shares are not liquid. They’re down around 4% at time of writing, so perhaps we are seeing a setback in this recovery.
Highlights:
- Revenue -8% to £60.2m,
- Operating profit -74% to £601,000,
- Adjusted EBITDA -36% to £3m,
- Net debt down from £7.2m to £2.7m,
- Adjusted operating cash flow steady at £4.7m (FY20: £4.6m),
- Basic earnings per share (EPS) -91% to 0.27p,
- Adjusted EPS -45% to 3.91p,
- Restructured debt facilities comprised of £7.3m loan and £2.5m overdraft,
- Proposed reinstatement of dividend of 0.5p per share.
Visible revenues over the next three years are £170m (2020: £172m) including £8m in visible revenues secured since the year end with a strong pipeline.
It’s been a particularly tough year to enact a turnaround, but this is exactly what Kinovo management has been tasked with. It has instituted a new vision and purpose, pushed through structural changes, reduced debt, generated cash, invested in the business, and is now proposing dividends.
The old Bilby was ‘buy and build’ but there is now a renewed focus on organic growth alongside strategic acquisition opportunities. Investment was undertaken to grow the Business Development team during the year which will continue in the year ahead.
Management says performance in the three months to 30 June 2021 has been in line with expectations and conditions could strengthen as lockdowns ease.
Conclusion
This is a riskier stock to consider, but it’s worth remembering that this micro cap generates upwards of £60m in annual revenue. So if it can get this turnaround working, there is potential upside.
While earnings have certainly taken a big hit, cash conversion is strong (adjusted cash conversion of 156%), which suggests the underlying business is in ok shape and has the ability to self-fund its improvement initiatives going forward. Net debt also fell handily in the period.
This early in the game, I’d rather see that dividend cash being used to further strengthen the group’s balance sheet. And if the shares really are cheap, why not just buy them back? There are ongoing adjustments to results and various non-recurring charges to sort through, as is often the case with rapidly changing turnarounds.
Ultimately, the fundamental case here remains the same: a risky, illiquid micro cap - but one with what looks to be a solid new management team, a market cap of just £22.3m, annual revenue of more than £60m, and that managed to remain profitable through the global pandemic.
It won’t be for everyone and you’ll need a certain risk tolerance to consider it, but with a fair wind and able management the stock could double over the next year or two, so it’s worth monitoring.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
£PURP. I liked the proposition and recommended an Èdinburgh branch to my son, but it was a mistake. Service has been very poor. He finished up writing the Particulars. They gave no substantive advice on price and were no help on a negotiation. Now I know why they are cheap to use. Never again. I think there is a place in the market for an agent who charges a basic price if the HR value isn’t exceeded but a much higher rate on the excess - that would be a good incentive.
I don't get it myself either. We sold a house earlier in the year with a local estate agent and the couple of grand in fees was well worth not having to take time out to conduct viewings, get personally offended by low ball offers and was useful for creating a bit of distance between us and the buyer.
My only regret is that I sold to soon but I suppose thats the story of my life.
On the topic of Audit delays
Creightons (LON:CRL) have just announced they are not presenting tomorrow due to audit with no specified date...
I hold
I've had a position in Caledonia Mining (LON:CMCL) for about 7 years now. It's clear that the share price got ahead of itself in that spike last year, but I've bought more since it dropped below 1300. It seems to me that two things are not being properly valued - a) the step change in production now the Central Shaft is in use, and b) the sudden ending of the outgoings on that project after several years of investment. I think it's time I topped up again.
Gateley Holdings (LON:GTLY) and Davidsmyly, according to Stocko the frequent selling of shares owned by its Directors happened 17 months and more so its all water under the bridge. Around the time when all of us should have been selling all of our shares! I do hold.
Silver
Hi Silver Moon,
Re: Gateley Holdings (LON:GTLY), you are absolutely correct. I was idle and took the comment on the share sales from Jack's analysis of the company on 6th May at the time of their trading update, when he said that "the scale and frequency of selling is notable".
Mercia Asset Management (LON:MERC) I meant.
£merc had fabulous figures. Eps of 7p .Nav of 40p. And a very bullish comentary
Wynnstay (LON:WYN) I tried to access the webinar today on Investor Meet Company. Unfortunately I was in an area with bad reception. Disappointing that there was a notice saying the webinar will not be recorded for me to see when I get home. Other websites manage this, notably our own Mello - I wonder why they (IMC) don't?
IMC do record their investor meetings; videos are available for every one that I have attended, going back to October 2020.
If the Wynnstay (LON:WYN) meeting was not recorded, that would be a decision made by the company management, so you should address your concerns to them.
Wynnstay (LON:WYN) Thanks for the info - maybe it will appear on WYN Investors website in due course.
£WYN FYI Watched a presentation of their latest results early this afternoon on Meet The Investors . The presentation was recorded and should be on the MTI site fairly soon.
The video is now available on IMC.
Wynnstay (LON:WYN) Late update - a link has now appeared in my email to view the recording. I take it all back.
I also listened to the Wynnstay (LON:WYN) webinar on InvestorMeetCompany (IMC) and thought it was very good. Particular points were that the freehold property is still on the balance sheet at cost (bought in the late 1950s!) and he estimated was worth £10m more than book value, but also stressed that it's being used to run the business, so isn't surplus as such. It seems crazy to me that accounting standards don't require freehold property to be shown at open market value.
It's subjective, but management struck me as "steady eddies", which is what you want for that type of business.
Good answers to questions about inflation & pricing power - they take a small margin of about 2.5%, and the revenue is largely pass-through. I.e. if input prices go up, they reflect that in higher selling prices almost immediately, which the customers understand and expect.
The big issue for me is the development of agritech. I listened to a fascinating webinar on Moneyweek, where Merryn interviewed Jim Mellon. It's here, and well worth a listen. Mellon reckons that lab/factory grown meat, fish, and dairy could rapidly gain ground, and supplant about half of existing animal-based production. If he's right, then that would be devastating for farmers, and animal feed sellers (like WYN).
I couldn't ask the question during the webinar, because I was trying to cook lunch on a camping gas stove on my very windy balcony here in Bournemouth! (it makes the kitchen smell cooking indoors).
Regards, Paul.
Purplebricks (LON:PURP) (I hold)
Things I liked
Note that all contractor/agent fees are included in costs of sale, not in "People Expenditure" further down the P&L.
Hats off to management here.
I still don't understand how Strike will make any real money. Even the Rightmove listing fee can be obtained by private advertisers on some websites for £1/7days or £30/30 days.
From my notes from January 2021, Strike had accumulated losses of £38m. I haven't checked on updates since then, but clearly the owners have deep pockets.
Things I didn't like
I'm wondering whether it's the factoring arrangement the company had (which I thought they were getting rid of.)
If it is, this seems a complete waste given the cash resources that Purplebricks (LON:PURP) has at its disposal.
No position change for me, though I look forward to seeing the new pricing structure in action and hopefully an increase in that market share.
Cheers
A
Paul,
Regarding your comments on Gateley Holdings (LON:GTLY), doesn't the fact that the directors have been selling a lot of shares increase concern that there might be "a potentially bigger problem"?
RE Purplebricks (LON:PURP), I agree this pricing model is needed for the biz to be sustainable. Saw the CEO on SkyNews today where he plugged that. But, the PE ratio is 64!!! This looks a stretch to put it mildly. Does anyone know if there is anything artificially inflating the PE ratio? The cash looks good but doesn't jump out to me when I look at the Stocko screen.
Hi Paul/Jack. Can i just say that the newish format of small previews at the start of the day and personal responses in the comments section from you during the day is really working well
How kind, thanks Martin!
Here are my SCVR heat maps for today (prices as at ~9:35am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
I just got the below message from my broker AJ Bell
Marks & Spencer Group has announced details of a capital reorganisation, which means there is a proposed significant change to a company or groups structure.
Under the proposals, each of your existing ordinary shares of GBP0.25 will be subdivided into one new ordinary share of GBP0.01 and one deferred share of GBP0.24.
The deferred shares will have very limited rights and will be effectively valueless. As such they will not be credited to your account.
What, why, huh, that just confusing and of benefit to know one. What is going on?
Previously Marks And Spencer (LON:MKS) has used various share schemes to organise buy backs. Could this be a lead up to another?
Hi ambrosia,
Marks & Spencer Group has announced details of a capital reorganisation, which means there is a proposed significant change to a company or groups structure.
Under the proposals, each of your existing ordinary shares of GBP0.25 will be subdivided into one new ordinary share of GBP0.01 and one deferred share of GBP0.24.
The purpose of these capital reorganisations is usually to create distributable reserves. That then allows companies to pay divis, where they would be legally barred from doing so, if there are no distributable reserves.
It's just a legal matter, which facilitates distributions to shareholders, and has no commercial impact on shareholders as such.
Regards, Paul.
Not being rude, but make sure your communication on the Marks And Spencer (LON:MKS) purported reorganisation is genuinely from AJ Bell. I had a very odd email a couple of months ago about something similar that turned out to be a phishing scam. If in doubt, I would suggest you contact AJ Bell or even Mark’s investor relations directly.
Gus.
Not being rude, but make sure your communication on the Marks And Spencer (LON:MKS) purported reorganisation is genuinely from AJ Bell.
And, as far as I can see, there is no capital reorganisation notice from M&S, so it looks odd.
timarr
Solved - the Marks and Spencer (LON:MKS) capital reorganisation is contained within their AGM notice - the RNS simply announced the date and referred to their website for details.
There is a very detailed explanation here https://corporate.marksandspencer.com/msar2021/notice-of-meeting-2021.pdf (resolutions 15,16,22).
As Paul commented there is no impact on shareholders and normally this little trick is used to boost distributable reserves. However, in this particular case it appears to be to lower the cost of issuing shares to employees.
Hi Paul,
Any chance you could cover the results of Kinovo (KINO) this morning? I picked up a few recently, the market seems unexcited so far, recent name change, one for the future perhaps?
Keep up the great work by the way!
Cheers
I was also quite happy with the Kinovo (LON:KINO) finals this morning. The outlook and reinstatement of the dividend were both positives to me, and the move into renewables (plus the announcement of the award of some initial contracts) is an excellent growth segment to be in. I suspect this morning's drop is the market reacting to the now historical results of last year, but I'm happy to see how this pans out. I do suspect, and obviously hope, on a two year view today's price of circa 35p will look very cheap.
Hi Paul,
A couple of questions on Pci- Pal (LON:PCIP)
1) Does it concern you that management have little/no skin in the game?
2) I watched the most recent company presentation where management expected revenues to grow ~30% going forward (even with expansion into new markets) Is this not quite low? or do management have a history of guiding extremely cautiously
I know its not on this mornings SCVR but i have been researching the company recently.
Thank you for everything you do here :)
Hi joshwood,
1) Does it concern you that management have little/no skin in the game?
2) I watched the most recent company presentation where management expected revenues to grow ~30% going forward (even with expansion into new markets) Is this not quite low? or do management have a history of guiding extremely cautiously
1) I wouldn't say it concerns me, but I much prefer it generally when management have bigger personal shareholdings.
PCIP (I hold) is one of those situations where management seem very capable, but also seem quite young, and maybe haven't built up substantial wealth in their own names yet? That's often the case, where good people (even on quite big salaries) are focused on funding their families, mortgages, school fees, etc, so don't actually have much in the way of savings to invest in the companies they run. Hence why long-term incentive plans exist, to lock them in and allow them to build up meaningful stakes. That's the idea anyway, but all too often Directors see them like bonuses, and cash in their share options!
2) It's growing much faster than 30% at the moment (about double that), so hopefully they can beat the guidance. Although as numbers increase, % growth rates naturally tend to slow.
On another point, I've got mixed feelings about the decision to raise more cash, and expand into new geographies. Whilst it makes sense to grow the company, and take advantage of expansion opportunities, this has pushed back breakeven a fair bit. That nearly always seems to happen with loss-making companies - they hardly ever achieve the timescale of breakeven, and nearly always come up with reasons to raise more cash along the way.
That said, I do think PCIP is the real deal, and has a lovely market niche, and is expanding very fast in the USA in particular. So it's a nice long-term tuck away & forget share in my view, but probably going to sleep for a while.
Regards, Paul.
Actually re. STU it looks down to capex. Any idea of the investment/maintenance split of this and whether it has been well spent?
Hi dogon,
Good question, this prompted me to check whether Studio Retail (LON:STU) (I hold) is capitalising an outrageous amount into intangible assets for IT development costs, which is one of the faults I found with similar business model N Brown (LON:BWNG) (which I sold out of recently, when the legal case against Allianz doubled in size from large, to scary).
Here is the relevant section from STU's recent results, cashflow statement.
As you can see, it capitalised software & IT development costs of £8.5m in FY 03/2021, and almost nothing the year before. That's a very much better situation than N Brown (LON:BWNG), where EBITDA is meaningless because the capitalised IT spend is about 4-5 times the size of what STU is capitalising.
Sorry that doesn't directly answer your question about what is expansion vs maintenance capex, but I thought it was relevant to mention.
The more I look at STU, the more I like its valuation.
Regards, Paul.
Totally (LON:TLY) - just crept into profitability in today's preliminary results. I hold on the basis of the huge NHS waiting lists backlog and needing all the help it can get. There are not many ways to support this on the UK stock market. Good medium term growth prospects I think as NHS managers will be under pressure from politicians to solve unpleasant headlines raised by the media. Taking a hammering (opportunity!) today .
Does anyone have insight into the consistent negative cash flows at STU? I would have thought this was linked to the high credit use, but the historic pattern does not easily seem to fit what I had expected in terms of higher cash out flows as it grows with more cash in where sales fall?
Hi Dogon,
In the most recent 2 years, STU has generated strong cashflow, especially most recently for FY 03/2021, but it's mostly ended up going into a larger consumer credit receivables book. That's fine by me - revenue grew a lot, so I would expect the receivables book (a key profit generator, at high interest rates charged to customers) to also have risen.
Paul any comment on J Sainsbury (LON:SBRY) profit upgrade cheap PE biggest shortage share in fste100
Yes, I doubled my position in J Sainsbury (LON:SBRY) today, in the opening auction! Looks interesting, particularly given the bidding frenzy surrounding MRW.
cheers paul i work nights at the big big sbry 30 east of bournemouth...
My morning smallcap tweet: QBT makes attempt on bandwaggon record.
Water Intelligence (LON:WATR) Ten Lifestyle (LON:TENG) Microsaic Systems (LON:MSYS) Gresham Technologies (LON:GHT) Mattioli Woods (LON:MTW) Xeros Technology (LON:XSG) Coca Cola HBC AG (LON:CCH) Argo Blockchain (LON:ARB) Blackbird (LON:BIRD) Ridgecrest (LON:RDGC) Quantum Blockchain Technologies (LON:QBT) Ilika (LON:IKA), Gateley Holdings (LON:GTLY)
Water Intelligence (WATR) wins "Preferred Contractor" status from US insurer, its broadest yet. [SP=874.5 Cap=135m]
Ten Lifestyle (TENG) 3 year contract with a leading credit card issuer in the APAC region. Also gets multi-year extension of a Medium contract in the APAC region. "These contract wins are incorporated within the Group's existing growth plan." [SP=104 Cap=85m]
Microsaic Systems (MSYS) H1 rev up 52% on 2019. CEO ""thrilled to report this transformational performance". [SP=0.25 Cap=15m]
Gresham Technologies (GHT) guides H1 rev up 19% and LFL up 14%. Confident of achieving FY market expectations. [SP=155.55 Cap=130m]
Mattioli Woods (MTW) guides FY(May) rev up 7%, profit in line with mgmt exp. [SP=740 Cap=335m]
Xeros Technology (XSG) agreements with two domestic washing machine manufacturers to test and trial the microfibre filtration technology, XFiltra. Expect completion by the end of Q1 2022. [SP=231.3 Cap=55m]
Churchill China (CCH) May and June rev recovered to 2019 levels, good forward order book. Interim dividend of 6.7p. [SP=2635 Cap=9617m]
Argo Blockchain (ARB) June mining revenue falls to £4.36m (May: £5.51m). Exploring a potential secondary listing on NASDAQ. [SP=128 Cap=489m]
Blackbird (BIRD) Univision has entered into a multi-year deal to deploy Blackbird to drive large-scale video production efficiencies across its streaming and digital media operations. [SP=29.98 Cap=101m]
Ridgecrest (RDGC) the cash sell plans RTO of Blue Air, a Romanian low-cost airline. Coincidentally (hah!) RTO deadline hit today and shares suspended. [SP=1.1 Cap=1m]
Quantum Blockchain Technologies (QBT) Achieves a new high watermark of promtion as it deploys a whole waggon-train of bandwaggons. crypto mining, Quantum Computing Cryptography, the cloud and AI. What's not to like? Here's a taste: "QBT will access D-Wave’s quantum-classical hybrid solvers, which leverage both quantum solutions ...With real-time access to quantum computers via the cloud, QBT aims to transform classic computing cryptography algorithms, such as the one used for Bitcoin mining, in quantum computations, or quantum-classic hybrid computations." [SP=1.06 Cap=10m]
Ilika (IKA) FY. Possible equity raise to scale-up of its Goliath battery technology. [SP=197.5 Cap=275m]
In line: Gateley Holdings (LON:GTLY)
Morning all,
I recognise that mining stocks are excluded from the report, but I thought some readers might be interested in Caledonia Mining (LON:CMCL) 's (I hold) update today.
Caledonia Mining's announcement indicates the company is on track to meet its increased gold production guidance of 61,000 to 67,000 ounces. This should then increase further to +80,000 ounces in 2022. These increases are due to a significant multi-year project to build and commission a central shaft, which is now operational. The quarterly dividend is also increasing to US$0.13 per share, an improvement of 89% since October 2019.
Stockopedia suggests a PE(f) of 3.4 in 2022; yet, drilling at the mine is expected until at least 2034, indicating a reasonable margin of safety. Key risks are the gold price, lack of momentum in the share, and that the mine is located in Zimbabwe. However, the company does appear to have a good relationship with the government and future exploration projects are underway.
DYOR :)
Cheers,
Hi kieranj077.
Also a holder of Caledonia Mining (LON:CMCL) and have been for a few years. Company has produced a stream of good news, increased dividends, extension of resource assays etc., in recent times yet the share price has been in a continuous decline since it’s peak last July (an M score of 5 says it all really). Does appear that the country risk given growing domestic political instability seems to be a much stronger countervailing force than the company’s own good performance. I suspect that won’t change anytime soon.
Gus.
Does appear that the country risk given growing domestic political instability seems to be a much stronger countervailing force than the company’s own good performance.
Frustrating - the fundamentals appear so sound as highlighted in the comments above. I also think the management and especially Mark Learmonth (CFO) always come across as very credible, prudent and very investor friendly.
The obvious Zimbabwe factor aside, I am wondering if Caledonia Mining (LON:CMCL) 's recent inclusion in the MVIS Global Junior Gold Miners (GDXJ) index is also playing a part in the negative momentum? A cursory glance at the charts seems to show that the most recent slide beginning in June '21 in £GDXJ is pretty much mirrored in the Caledonia Mining (LON:CMCL) chart ... I am wondering if there is an element of "negative momentum begets negative momentum" as various ETFs are selling down?
As a Caledonia Mining (LON:CMCL) shareholder, I’m quite comfortable with the jurisdiction. Why? Simply because the company has demonstrated that it can operate profitably in the country and has done so for many years. It’s also worth pointing out that Zimbabwe is in the throes of partially privatising the state’s Gold refining operations. According to an announcement made at the end of last year, this will involve the country’s mining companies taking a 60% stake in the new enterprise. Incidentally, Zimbabwe’s Reserve bank has also recently announced that it will allow large-scale miners to export directly a portion of their production under certain conditions (Rather than sell it to the state-owned refiner). It’s hardly the actions of a hardline Marxist Government.
Certainly under the radar but there are many very profitable foreign-controlled mining operations in Zimbabwe. However, this is not a narrative that reaches the Western business media.
Hi LongValue.
Re. Caledonia Mining (LON:CMCL) , I think the issue in Zimbabwe is not so much Marxism as rampant Crony Capitalism. Corruption is endemic (according to family living in South Africa with experience of working cross border) and the “diesel tax collector” (“diesel do for my brother in law” as they pocket yet another kick back) comes knocking on every business owner’s door sooner or later. The mood music from the authorities all sounds very forward thinking but reality on the ground is possibly very different. Contrarian sums it up.
Gus.
Cronyism is a parasite that will tend to be interested in the continued life of the host, whereas the Marxist or ideological parasite is between indifferent and deliberately deadly.
For Caledonia Mining (LON:CMCL) risks are elevated by jurisdiction due the greater chances of state failure and the things that the state provides directly or indirectly. Anyone holding Caledonia must weight a scenario risk of zero due to Zim f*$# up factor. Its uncomfortable but if we forget about gold price, gold dynamics and macro stuff and just look what Caledonia can add through 'self help' then its quite phenomenal improvement profile over next 2 years. A bit more flesh for the parasites to keep them happy and huge improvement in operating metrics for shareholders (revenue growth, op leverage, earnings, cf, op margin, ROCE as long term heavy capital investments has pay off, etc).
Optionality?
1) Gold price obviously. A few hundred $$$ on it will shift sentiment. That can go both ways obviously. I balance to up side risk. But even with downside Caledonia will survive well due to margins and production growth
2) Zim has been shut down to new development and has a lot of valuable old gold prospecting land that world withdrew from. Caledonia has access to lots of cheap high quality prospective land and can act as low capital providing JV partner to outside capital
Corrupt jurisdictions appear to be part and parcel of Gold mining. And I’m under no illusions about Zimbabwe. But I think that the management of Caledonia Mining (LON:CMCL) knows how to operate in the country. It has demonstrated its ability to get things done. The recently completed Central Shaft project took five years and was self-funded at a cost of around US$60m. As an engineering feat, it was an accomplishment - it goes down to a depth of some 1,330 metres (London’s Shard: 306 metres). Not only did it alter the economics of Caledonia’s operations but it also highlighted what could be done, even in a difficult environment, by an experienced team.
Frankly speaking, I believe that if the country was a complete basket case, Chinese and Russian companies would not be pouring billions of dollars into its mining sector. I also suspect that these operators take assurances given to them by the Zimbabwean authorities very seriously.
Continued improvements at Purplebricks (LON:PURP) - as expected they've moved into profit, they have quite a lot of cash in the bank (£74 million) and are now solidly UK focused.
However, their share of overall instructions has fallen a bit and their expectations for the current FY are flat, year-on-year, in part (I think) because they expect the current very buoyant conditions to ameleoriate. No doubt that won't go down very well.
As conditions normalise the new management team have a pretty clear run at making this work - it's pretty clear there's a profitable business here now, the main question will be over future growth and, therefore, valuation. Given the progress so far I intend to continue to hold, it'll be interesting to see how they put their cash pile to work.
timarr
Agreed, I also hold. I had a good experience with them last year and found their local agent fairly knowledgeable and pleasant to deal with. I settled on using Purplebricks (LON:PURP) after a terrible experience with pushy Foxtons (LON:FOXT) agents.
The whole experience with £PURP was fairly slick and I never felt like I was being pushed into a lower valuation which is what got me to research into the stock for a long term hold.
Doesn't the commission structure - payment up front - mean that the valuation is immaterial to Purplebricks?
That isn't the same for traditional estate agents, who often offer higher valuations because that is a major driver of why customers choose them.
TBH I find it hard to see where differentiation comes in against stuff like Emoov/Yopa. One software backend may be better than the other, or one local agent may be nicer, but that isn't the same as competitive advantage.
So in a same way that BOTB announced news without referencing a competitor (Omaze), I wonder if similar has happened here? There seems to be a new player - Strike - which offers the service free now.
Strike is a very interesting proposition. How would their valuations stack up against the rest if as you stated with PB valuation is immaterial?
I considered using Strike as they were cheaper, but they didn't have the large network of local agents, so it raised a value question for me. In my area of London there was only a generic agent covering a wider area the time. Purplebricks (LON:PURP) agents generally have experience in the hyper local area to you.
Foxtons (LON:FOXT) agents in London generally hover a cheaper valuation if they think they can obtain a quick sale. They will float it to you over the phone to see if they get a bite, before sending a more sensible valuation formally by letter. Shoddy practice, but having worked for a large interdealer bond broker in London for many years it is understandable from their perspective.
Property is a lot like bonds (illiquid and each product is very different), and firms can make huge profits through brokerage, especially the ones who have the capital to buy it onto their own book. It's the reason that Opendoor on the Nasdaq is my single largest portfolio position. Please do your own research/diligence.
I recently used Strike to sell our BTL flat and I have to say I was impressed with the e2e experience. My wife was in a position to lead the sales charge, taking the role of the local agent by hosting viewings and taking all the pictures (both of which are chargeable options if you're unable to fulfil yourself).
Saying this, even on the "free" package, you still are assigned an account manager that follows up all viewings with phone calls, then a sales manager who manages the negotiation process on your behalf. You can also chime in with direct messaging to the prospective buyer too.
Majority of feedback we received from viewers of the property were that they loved the fact the owner was showing them the property as they knew the detail that the estate agents do not.
We ended up agreeing upon an offer -3% of our asking price after c2 months on the market and a steady stream of viewings. This -3% was virtually made up from not using a high street estate agent.
Selling costs? £150 for a premium rightmove etc listing, and c£1k for a conveyancer. The cost for using Strike = £0. Amazing.
I hold Purplebricks (LON:PURP) great results getting out of the debt they had and now cash at the bank. I think one of the barriers to using PB is the loss of fee if there is no buyer identified. And traditional agents use this as part of their presentation to scare people off using PB. Today they launched a Money Back Guarantee which should alleviate that concern. I also think some still don't understand the saving offered by PB. Flat fee of £999 to list. Traditional Agents are free to list but still making 1% of sale price with an average £250K that's a far cry higher than PB.
Foxtons (LON:FOXT) fees will make your eyes water
The market share drop along with the flat YoY EBITDA guidance is what is making me sit in the fence with £PURP
I think alot of short term investors in here will get bored over the next 12 months seeing flat EBITDA.
But genuine value if they can double market share to 10%. Albeit a warning about operational gearing - its not a typical online only or SaaS play as they still need agents, so operational gearing won't be as strong here compared to online only companies. Must be careful valuing this one, hybrid of online and traditional.
I don't hold but one on my watchlist.
Their progress is shown in my area. One traditional agent who had done well for many years has closed. Purplebricks boards used to only appear on the cheapest houses but are now on the mid range (c 1 million) and are successfully selling. The savings are huge.
Totally and Kinovo
This sounds like an 80's buddy movie
With Tom Selleck as Totally :)