Soaring silver miners: Fresnillo and Hochschild Mining

There are a number of entrenched dynamics that make gold an attractive proposition these days - and where gold goes, silver tends to follow (but with added rocket fuel).
In fact, some call silver the long shadow of gold. It’s a riskier and more leveraged play on the same dynamics of widespread currency debasement and non-existent bond yields.
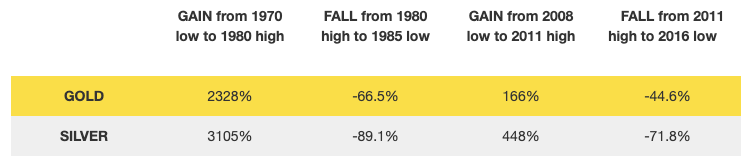
The correlation is slightly obscured by larger industrial demand for silver, but they are correlated nonetheless.
Silver is more volatile because it is a smaller market with lower liquidity. Back in the 70s and 80s the Hunt Brothers cornered the entire private market, taking a huge leveraged position and causing the dramatic price spike in the chart below.
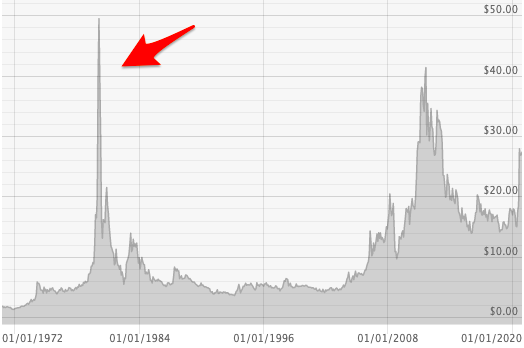
They allegedly held one-third of the entire world supply of privately held silver.
This remarkable situation prompted the jeweler Tiffany's to take out a full page ad in The New York Times, saying "We think it is unconscionable for anyone to hoard several billion, yes billion, dollars' worth of silver and thus drive the price up so high that others must pay artificially high prices for articles made of silver".
This standoff was ultimately resolved through a combination of changed trading rules on the New York Mercantile Exchange (NYMEX) and Federal Reserve intervention. By 1982, the London Silver Fix had collapsed by 90% to $4.90 per troy ounce.
In conclusion: a smaller and more volatile market. You can see below that even today total annual silver supply is a fraction of that of gold.
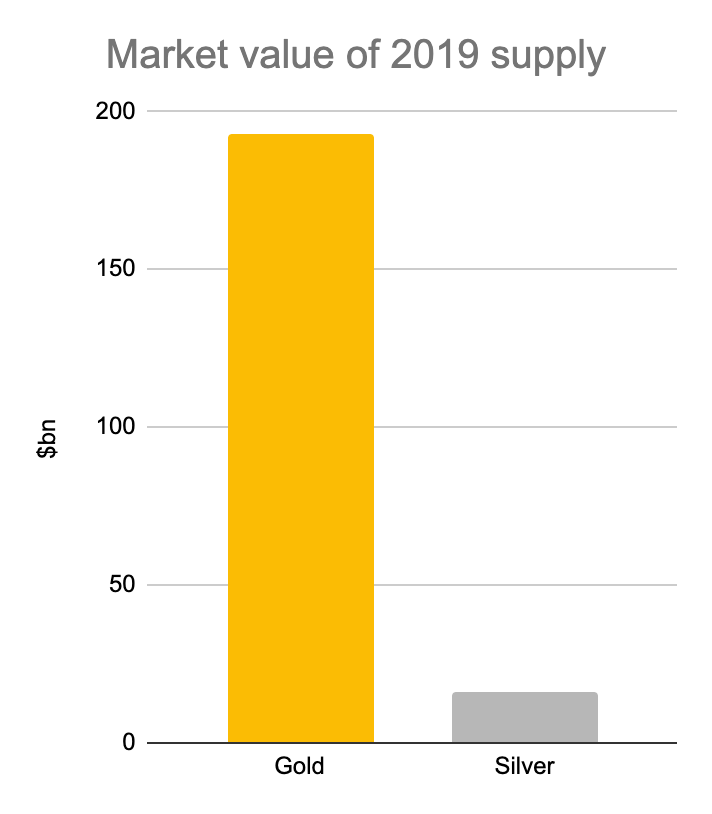
With everyone talking about the gold price hovering around the $2,000 mark, there are signs of life in silver as well.
This is purely anecdotal, but I’ve heard a couple of institutional investors in the space throw out some eye-catching silver price predictions that blow historic norms out the water. They are talking their own book of course, but what’s more concrete is that they are seeing considerable inflows right now.
Investment demand shows a 10% gain so far in 2020 as investors actively accumulate silver. As of June 30th, global ETF holdings reached a fresh all-time high of 925 million ounces (Moz).
The two spot prices are taking a breather, but the sheer tectonic scale of modern monetary theory (QE, negative interest rates) and the resulting institutional asset rotation into alternative stores of value suggest to me this could be a trend that runs and runs.
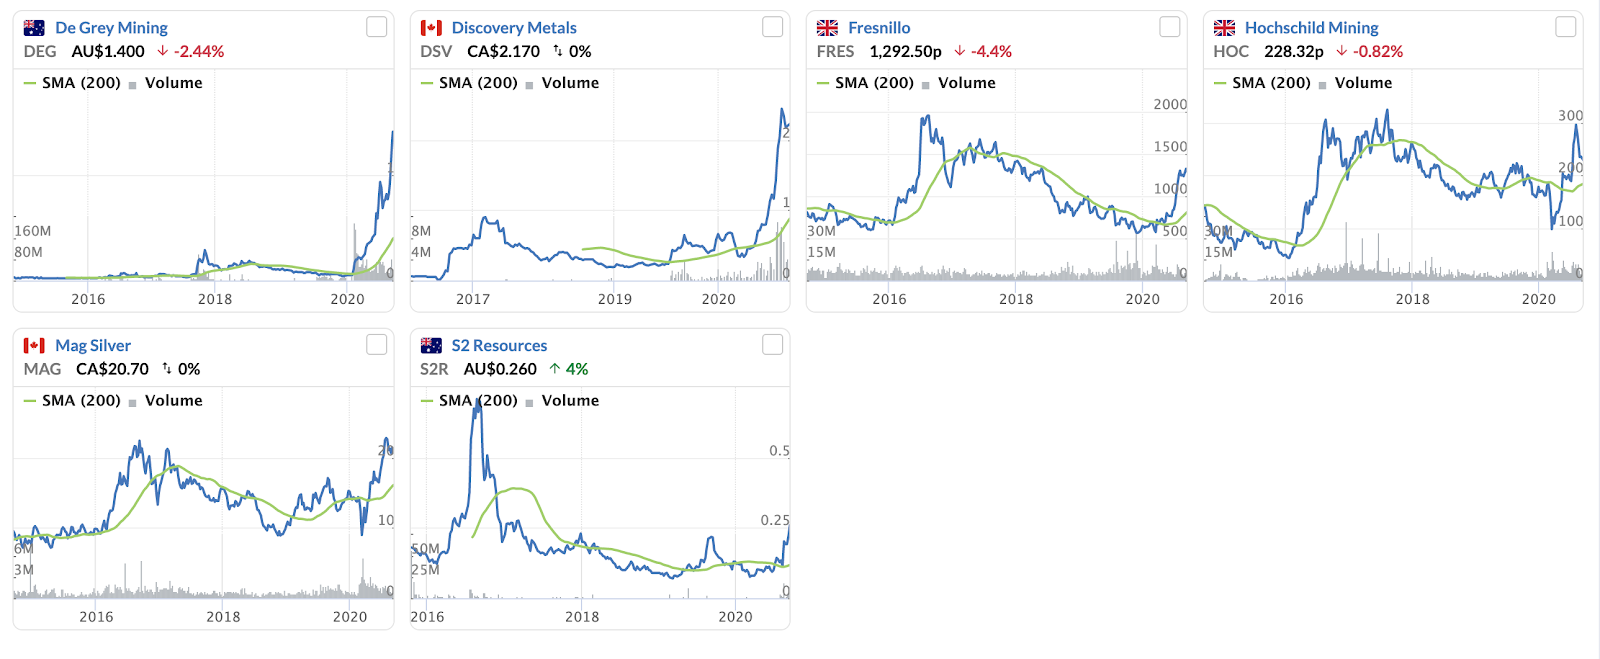
The 6y chart view of this basket of silver miner candidates tells a story, with recent strong breaks above the 200-day moving average:
I think silver is worth a look for the following reasons:
- Investment inflows will continue in the second half of 2020 (and likely beyond) thanks to its safe-haven status,
- Low interest rates have reduced the opportunity cost of both gold and silver,
- Unprecedented liquidity injections by central banks should increase their purchasing power, and
- Silver is a smaller, riskier market than gold but with possibly greater potential upside.
There aren’t many dedicated silver miners that I’m aware of. I’ve taken a first look at Fresnillo and Hothschild Mining below but if you’re aware of any promising candidates just leave a comment.
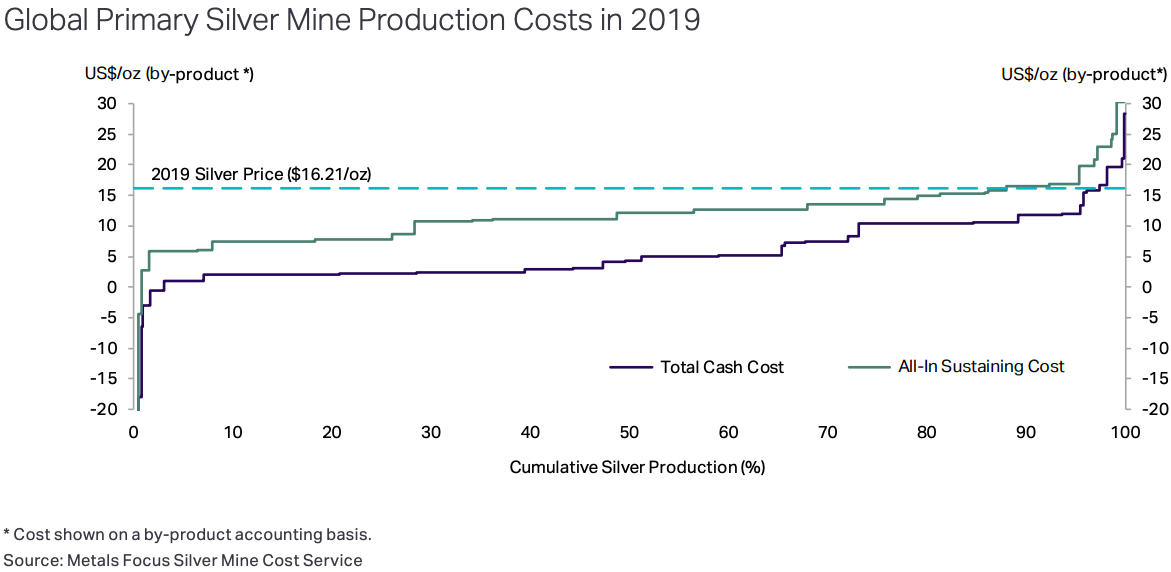
This cost curve chart from Metals Focus gives a useful sense of perspective in terms of judging how efficient these miners are:
Fresnillo (LON:FRES)
Market cap: £9.6bn
Net cash (debt): - $300m
1y relative strength: 114%
AISC: $13.5
Silver production (2019): 54.6Moz
Fresnillo (LON:FRES) is the world’s largest primary silver producer with seven operating mines in Mexico, as well as a number of other long term exploration prospects in Mexico, Peru and Chile.
Improving sentiment for silver is obvious on Fresnillo’s StockReport, with healthy relative strength and improving broker forecasts.
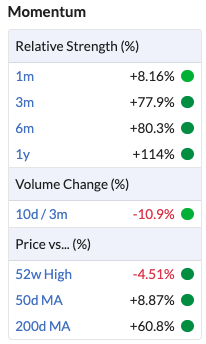
It also qualifies for two Momentum Screens: Earnings Upgrade, and Value Momentum.
With a market cap of nearly £10bn and annual revenues upwards of $2bn, FRES is no tiddler. That scale hopefully makes it one of the safer miners - but it might also limit upside.
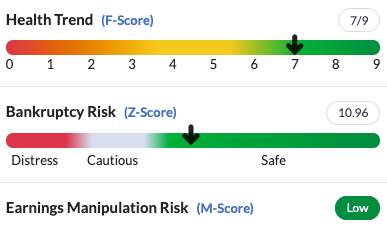
It has a very manageable net debt position of £300m, as well as strong liquidity and financial health ratios.
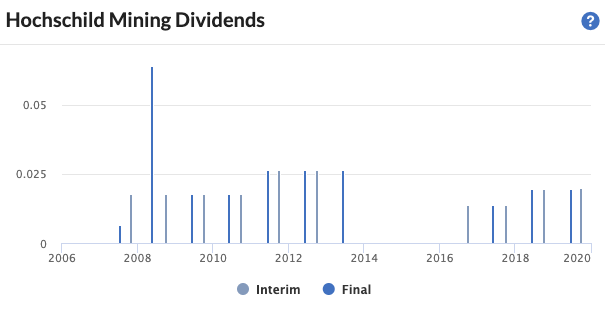
FRES has proven itself to be reasonably cash generative and has made consistent dividend payments over the years.
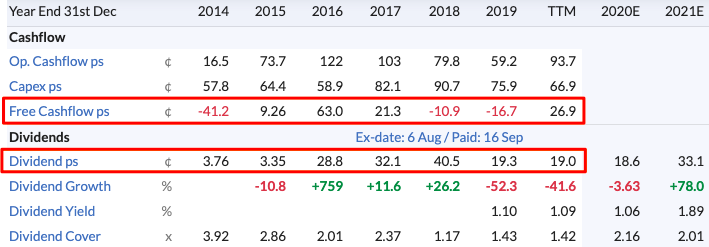
The group says it’s policy is ‘guided by the principle of providing shareholders with full exposure to gold and silver prices’ so there is a good chance of free cash flow and dividend payments increasing over the next couple of years assuming spot prices continue to appreciate.
Again, that is far from certain - but my view is that an extended run of increasing spot prices is quite possible.
DYOR of course and I welcome a debate on this point.
Investment case
ETFs aside, Fresnillo looks like a financially safe and operationally stable large cap miner in the silver space. It sails past the Financial Health checks, which partially explains the impressive Quality Rank of 82.
The group is financially stable and well invested. It has a modest net debt position of c£300m and it makes a point of investing throughout economic cycles - so if there is a prolonged uptick in silver prices, this miner is well placed to capitalise.
It also has high quality assets and long life returns. It is among the largest concession holders in mineral-rich Mexico, with c1.8m hectares of surface land.
According to FRES its portfolio of low cost gold and silver mines, high potential development projects and advanced exploration prospects “contain over 2,171.5 moz of attributable silver resources and 38.4 moz of attributable gold resources”.
The group’s ability to control costs and generate good returns on capital and operating margins in less favourable price environments bodes well for the future.
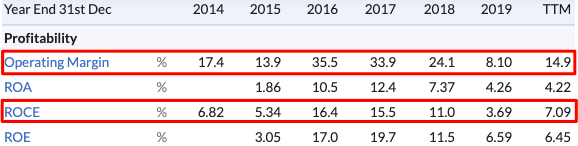
The group recently updated the market on trading and the outlook sounds encouraging. CEO Octavio Alvídrez commented:
The combination of higher commodity prices and lower costs has resulted in a significant rise in profitability during the first half. Our performance improvement initiatives we have set out in previous reports are having a positive impact. We remain committed to delivering a sustainable improvement in our operating performance and maintaining the momentum in the improvement plan into the second half.
Some financial highlights:
- Gross profit up 56.3% to $321.2m
- Operating profit up 232.1% to $216.9m
- Profit before tax up 136.6% to $127.9m
- Adjusted earnings per share up 40.5% to 11.8 cents
- Free cash flow of $242.6m (versus an $80.7m free cash outflow in H1 2019)
Conclusion
First impressions are that this is a reasonably safe, profitable miner that is well-invested and therefore well positioned to benefit from rising silver prices.
Production is down only slightly year-on-year despite the spread of COVID and FRES maintains its full-year targets of 51-56moz silver and 785-815koz gold.
The miner has plentiful resources - about 2.3bn oz of silver and 39m oz of gold - and says it operates at a consolidated silver cash cost of $7.31/oz compared to the current silver price of around $27. It’s track record for returns on capital suggests quality assets and a disciplined approach to capex.
DYOR as always, but if you’re looking for exposure to the silver price then the world’s largest primary silver producer seems like a sensible place to start.
Hochschild Mining (LON:HOC)
Market cap: £1.19b
Net cash (debt): -$57.3m
1y relative strength: 35.7%
AISC: $11.9
Silver production (2019): 16.8Moz
Hochschild Mining (LON:HOC) currently operates three underground mines - two in southern Peru and one in southern Argentina - and also owns numerous long-term projects throughout the Americas.
With a modest amount of net debt and strong financial health scores, HOC also presents itself as a potentially ‘safe’ silver miner.
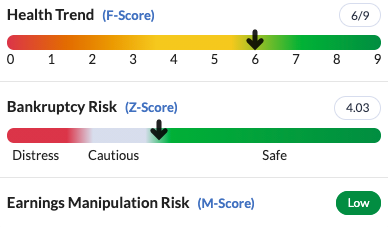
The group’s current score of c1.8x is solid, but not as encouraging as Fresnillo’s liquidity. HOC also pays dividends but the track record here is a little patchier.
It appears to trade at a pretty attractive discount to its peer group.
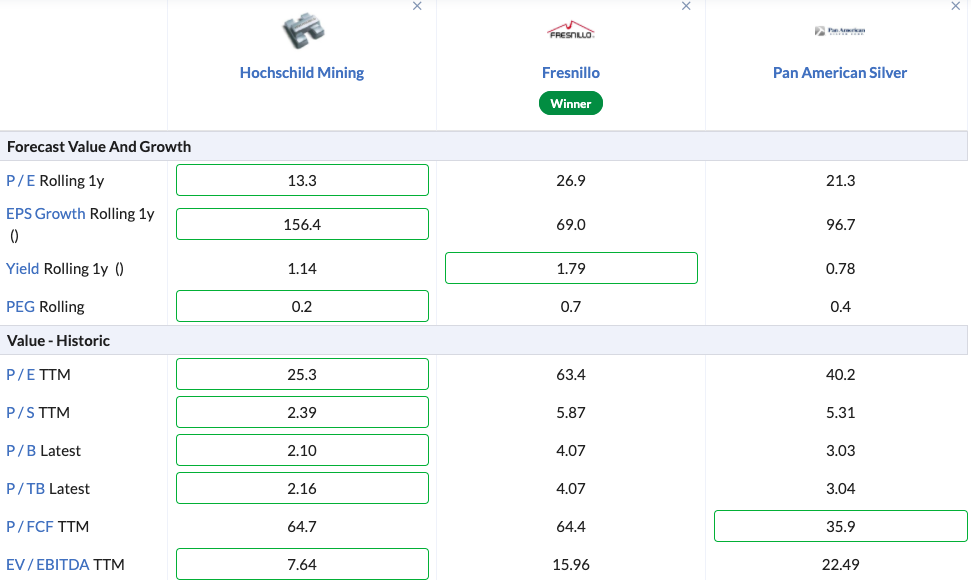
But a look at HOC’s most recent update shows COVID-related operational disruption - so is the discount warranted?
HOC has confirmed that its flagship Inmaculada site is back to full capacity and its revised FY20 production target is for 24-25m silver equivalent ounces at a silver equivalent all in sustaining cost of between $14.5-15.0.
There are ongoing restrictions in Peru and Argentina but the group expects to “deliver a solid second half of production with strong expected cashflow generation.” You can see from the table below just how much Q1 and Q2 production was hit.
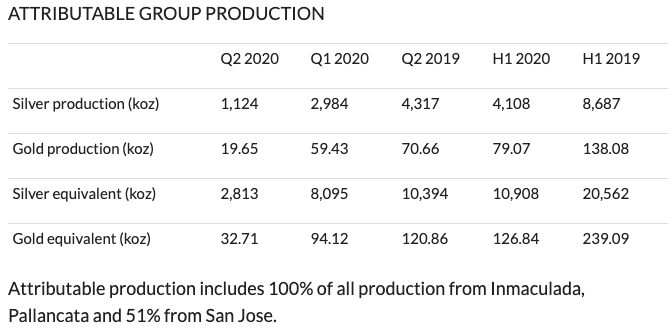
I don’t think HOC is out of the woods yet. It has clearly faced more disruption than FRES but then again that relative valuation discount prices some of this in.
What’s more exciting is the average realisable prices reported by HOC in Q2 2020:
- $1,826/ounce for gold - up 35.7% (Q2 2019: $1,346/ounce), and
- $19.8/ounce for silver - up 33.8% (Q2 2019: $14.8/ounce for silver)
If those numbers continue to trend upwards over, say, a two-year horizon then a couple of quarters of disrupted operations might be a small price to pay.
Alternatives
Both FRES and HOC have a Speculative RiskRating, meaning their share prices are quite volatile.
With much less dedicated silver miners around, and a smaller, more volatile market, ETFs could be an attractive option for some.
I’m more of a stock picker but I can clearly see the case for more broad-based exposure here.
The leveraged nature of the silver price would give plenty of scope for upside if the bull case plays out. The iShares Silver Trust (the biggest silver ETF out there) has had a stellar year in terms of share price.
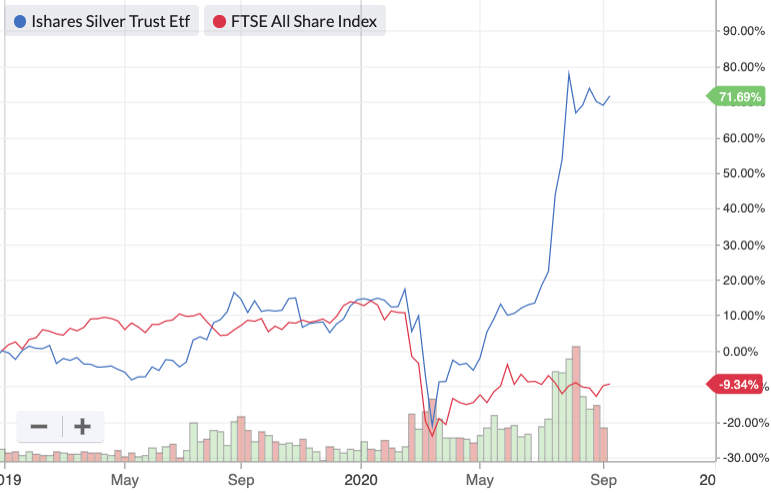
In one of Edmund Shing’s excellent Market Musings posts he points to another silver ETF: the SILJ Junior Silver Miner.
At the moment I’m considering stakes in both FRES and HOC to dilute away some of the company-specific risk. Of course spot prices can go down as well as up, but the bull case for silver looks attractive to me and I will continue to investigate ways of gaining exposure here.
If anybody out there is thinking along the same lines it would be great to spark a conversation on the topic.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Silver market much much bigger than Gamestop etc.
Having said that - although big banks have large holdings of physical silver they also have large short positions to hedge away the risk.
WisdomTree Physical Silver Individual Securities ETC (LON:PHAG) my biggest holding so fingers and toes crossed and more than a little interested to see how this plays out.
I don't have that one but I have $PSLV, which should shoot up when the market opens later.
I sold my IShares Physical Silver ETC (LON:ISLN) this morning.
Not sure which this will go.
Their argument is that there is a lot more paper silver than real physical silver out there. In other words lots of paper silver masquerading as real silver...100:1. JP Morgan were of course fined USD 920m last year for manipulating the silver market.
For leveraged silver plays look to the big Canadian royalty/streamers such as Wheaton Precious Metals, Franco Nevada and so on they are safer than the mining companies.
Silver is definitely up at the moment - in excess of $28 - who knows what the morning might bring.
Yes silver is up 10% and Fresnillo (LON:FRES) up 20%.
Fresnillo (LON:FRES)
Also be aware that it is a 75% subsidiary of Industrias Peñoles - there's only a 25% free float - just noticed Jack did not mention this.
I presume EI is referring to Reddit / WSB turning their attention to the silver market - interesting to see if it continues - ended just shy of $27 on Friday.
Never liked Fresnillo (LON:FRES) - seem to have continual production problems (therefore negating what they have in the ground) and seem very expensive.
My poisons of choice for silver exposure (although not pure plays) are Polymetal International (LON:POLY) who produce 19m oz a year and Golden Prospect Precious Metals (LON:GPM) who hold several Canadian silver miners along with their majority gold miners.
Phil
this article is probably more relevant going into Monday than ever.
Why? What is happening Monday?
Fresnillo (LON:FRES) have fallen due to landslides and Covid in Mexico hitting production, anyone have any views on them?
A Silver short squeeze is underway much like the Games top situation... They will try and drive the silver price up:-)
OK thanks I was not aware of that.
I think you might be right here:
https://www.zerohedge.com/mark...
Sorry just found the info i was looking for on POLY website :-
Polymetal International plc is a top-10 global gold producer and top-5 global silver producer with assets in Russia and Kazakhstan listed on the London Stock Exchange, Moscow Stock Exchange and Astana International Exchange. The company is a member of FTSE 100, FTSE Gold Mines and MSCI Russia. Polymetal has a portfolio of nine producing gold and silver mines and an impressive pipeline of future growth projects.
I do have a holding in Wisdom tree physical silver PHSP, Is possibly an alternative ?
Whil'st POLY have announced their new silver mine, that is some way off, but they appear to produce a substantial amount of Ag currently,although principally a gold miner. The fall these last few days ,after substantial shareholder sold a sizeable chunk. is it a buying opportunity ? I personally did add to my holding,no advice intended. Cheers stay safe Tony
Hi Tony.
A better Silver ETF in my opinion is:
Sprott Physical Silver Trust (PSLV.U)
Why do I consider this better than the Wisdom Tree ETF? I consider it to be better because it is owned by Sprott Inc. The physical silver is in their vault and you can (not that you would) take physical delivery of your metal.
The chart for silver looks very bullish. Some of the best picks are traded on Toronto and NYSE. I hold Pan American, First Majestic, Mag Silver, Silvercrest and Wheaton (Wheaton holds a number of silver streams and royalties, but diluted by their gold streams and royalties). I prefer Fresnillo over Hochschild on jurisdiction grounds but hold neither. There are some junior caps out there, particularly on TSX that look high risk and high return which I hold. Other options include SSR, which like PAAS, and the two companis you analyse here, have significant gold mining operations thus diluting the silver play. The purest silver plays are First Majstic, Silvercrest and Mag Silver.
Hi James,
Which gig risk tsx juniors do you like?
*high
Why is the price of silver down so much recently, it is now down 20% from it's peak in August, do you still think the chart looks bullish?
Fortuna Silver Mines (NYSE:FSM). Not a dedicated silver miner, but has new mine (Lindero) coming in to production so cap ex will be reducing and earnings improving. The financials are sound and just been added to the TSX 300 composite index. Bought in last September @ $4.81 CAD. Also recommend WISDOMTREE SILVER 3X DAILY LEVERAGED (3LSI). Not for faint hearted, but my view is the precious metals are about to experience the rally of a lifetime. Original purchase was in November 2011 at £1.77 and have been adding ever since. Got a little scary during COVID, bu the recovery since has been incredible.
November 2019 ETF purchase, not 2011.
Also highly recommended is Sylvania Platinum (LSE:SLP). Stockopedia Stockrank is 99. Original purchase was November 2019 at 38.09p. There's a long way to go for this company IMO.
what about jurisdiction risk?
Polymetal International (LON:POLY) made an announcement this morning on their initial ore estimate for one of their mines "The estimate confirms that Prognoz is one of the best silver development projects globally"
Why are the shares down so much?
OK I see the largest shareholder has sold 4% of shares.
Pan American Silver just updated their investor presentation. I hold.
https://www.panamericansilver....
Great company- I missed out. It’s been on a tear since April.
if they get Escobal mine operating again or if Argentina allows Navidad to be built, the shares are dirt cheap.
I think former has decent chance and latter has not moved for 10 years ( they paid stupid money to buy navidad in 2010).
Another possibility for a pre-production stock with silver is Adriatic Metals (LON:ADT1) - and Phoenix Copper (LON:PXC) is a micro-cap now attracting attention.
If you are feeling really speculative - Alien Metals (LON:UFO) is worth investigating as a junior silver (and iron ore) explorer.
Where did the 't' come from in £hocschild - annoying name, stick with £HOC Lost money on it recently down for no reason so one of those 'bandits' out there to be aware of.
Talk on Surface Transforms Surface Transforms (LON:SCE) shame they could not buy the moniker Bakery Services Ord (LON:BKE) the we would have something.
Hi Jack,
Great article - thanks for putting PMs under the spotlight. I have had a position in both for a while.
Two points that I would make to support your point:
1 I have heard that in1980 PMs (metals & miners) was 2.5% of investable assets. Given the horror of the long bear mkt and the fact that the sector was so unloved for so long, the PM assets are now ca. 0.5% of investable assets globally. It is a very small door.....when everyone tries to stampede through that door prices move very fast (in both directions as your brilliant table shows).
2. The leverage that the miners have to Ag price is scary.....HOC produces 16m oz of silver. Every $1 adds (annually) $16m pretax to the bottom line. Ag went from18 to 29 in a month between June and July and have settled around 26-27 level. Each dollar adds 3 cents (16/514) to EPS [pretax]. The leverage is immense. Both Fres and Hoc will fly with higher metal prices that are coming.
In the Great Depression, PM stocks were huge winners whilst the rest of the market crashed and burnt, in part , due to the incredible dividend payouts.
I was telling people to buy Polymetal early last year at 700p because they were paying good dividends during the bear market. I note from Stocko that Polymetal is going to pay 160c next year (based on current PM prices, so big chance of upgrade). Polymetal is an especially low cost provider. Fres and Hoc struggled due to higher silver mix in their production when Ag languished at the cost of production.
Ps note that Poly has almost replaced Shell in terms of FTSE stock with 6%+ dividend.
I am heavily invested in PM stocks and have (finally) had an amazing year thus far. These stocks will look extremely cheap in 18 months time when they are throwing out huge free cash flow/ dividends.
PRECIOUS METALS
Jack that a very interesting post
I have been taking a position in Precious Metal recently
I have positions in
iShares Physical Silver bought on 17 Aug @ 1999 currently 2052
Polymetal Int. (POLY) bought on 4 Aug @ 2033 currently 1952
Along with other Gold, Copper, and Platinum mining shares
I am now going to buy FRES Fresnillo on the next pullback.
I am also intending to add to the above on every 10% increase (pyramiding)
I now look forward to hearing from my fellow members on their views
Terry,
I need some help!
For most of us it is clear how to build a set of positions in Gold / Silver or PGM generally. It is not that that I find so troubling.
Given that most people understand that a bull run in precious metals might result in a x3 multiple in Gold miners, and perhaps a x5 multiple in Silver miners the question then becomes one of how to maximise the return from a parabolic run that has periods of very high volatility within it?
Essentially, how do you stay "in" despite the gains that you have made and the high volatility that will be experienced? And how do you know when to get out of a parabolic peak?
M.
I am working on a reply, but a bit busy at the moment. keep checking back
Regards
TT
Hi Macro
Sorry for the delay. The easy answer is Pyramiding and Stops.
If you have a portfolio of Precious Metals. You add to your position every time the price rises over 10% from the price bought. You keep adding every 10% rise. But you only buy 90% of the shares you previously bought. You should start with a 20% stop loss and reduce the stop loss on the whole sum by 1% every purchase. If you keep buying then you should have a Maximum stop of 5%. When the price hits the StopLoss then sell them all immediately.
So it should look something like this:-
1st buy 5,000 pounds at say at 500p, stop at 20%.
2ed buy 4500 pounds when the price hits 550p, stop at 19% on the whole sum
3ed buy 4000 pounds when the price hits 600p, stop at 18% on the whole sum
etc.
I hope this is useful. When you make you first million you can show me your appreciation with a small donation LOL
Good Luck and say safe.
Thanks Terry.
It is good to think this issue through as we do have plenty of time before it becomes a pressing issue. ... Rather like what to spend my (hypothetical) millions on once lockdown comes to an end!
The other day I re-read the Edison Gold report (https://www.edisongroup.com/se... ), by Charlie Gibson. On page 8 he writes about the inflationary period in the late 1970's: "Nevertheless, it is worth observing that, in theprevious case, gold did not top out until real interest rates reached over 4% for a sustainable period of time." What struck me about that comment was that (a) we are a long way from real interest rates being +ive let alone over 4% for a sustainable period of time, and (b) even if the governments achieve inflation targets (>2%) in order to achieve full employment it still takes a long time before the rising risk free rate of return works against peoples fears of future inflation and their attraction to gold; and (c) we might never get rising price / wage inflation again. To me asset price inflation seems more probable than consumer price or wage inflation - and I am not sure that nominal interest rates would be a useable signal for some time - if at all. We might never get a clear signal to inform us of the end of the trend?
Looking at a gold bull run chart here is the Gold Bugs Index (HUI) in the non-inflationary period from autumn 2008 through winter 2012.
There about 20 periods of time when the 20 day De-trended Price Oscillator (DPO-20) went negative. Some were shallow and short duration. Duration and depth of DPO-20 down-turn became more pronounced as the bull run came to an end. But there was no sudden and decisive change of character that signalled 'the end'.
Generally, I like your idea of pyramiding. But I do have a problem with pyramiding in a potentially parabolic bull-run when a inital allocation to PGM of 5% of portfolio might easily grow to a 15%-25% of porfolio over time even without pyramiding. Generally I have a dislike of selling & re-buying ~20% of a portfolio 20 times over a 4 year period! Lazyness? Old fashioned?
Generally, I like stops - but for an extended campaign the idea of paying out 0.5% stamp duty x 20 down-turns is a problem for me. ETFs not being liable for stamp duty might be an answer to that in part. And use of a cash market account for Buy-and-Hold, and a spread-bet account for shorts on the counter-trend might be part of a solution to that, too. I also wonder whether basing Buy/Sell signals on an index with a large number of PGM constituents, and that is therefore less volatile than the underlying, might be a way of reducing the number of whip-saws.
So, with your input I am gravitating towards: a small number of carefully chosen instruments in a cash account; use of pyramiding on these cash account assets; use of a spread-bet account for counter-trend shorts; use of a broad PGM index for Sell/Accumulate signals.
But as I say, there is plenty of time to work out an approach that is right for us individually!
Thank you Jack for another excellent piece.
I opened a position in FRES last April buying in at a shade under 740p and adding in July at 1034p. Currently up 56%
Like Russ Mould at AJ Bell my thinking was that Silver is increasingly very important in a number of industries and demand will increase for years to come.
Fresnillo is a big beast and can be extremely volatile but going forward all the signals seem to be very positive.
I found it useful to take the data from the quarterly production figures and multiply it by the spot figures. When I did it last, in April, both HOC & FRES came out as gold miners :-) although silver prices have recovered since and FRES are probably now a silver miner again.
What I was looking for was miners who were in a good position to benefit from a rise in prices. It was a useful exercise as it flagged up SRB, SHG & CMCL, and so far so good.
GE Ozs are particuarly irritating and I suspect are sometimes used to mask what really comes out of the ground.
Yes, I know, it’s simply a survey and it was published by a Gold magazine. But it tallies with what I believe to be true and that’s the popularity of Silver as an investment vehicle for American private investors. It also aligns with a suggestion that I heard many years ago. And that is currencies crumble from within. It’s not hedge funds or international money managers but ordinary people seeking an alternative to the domestic currency. Essentially, I think that both Gold and Silver may rise to prominence as the US Dollar falters.
https://www.prnewswire.com/new...
First Majestic Silver.
That collapse in the silver price in 1980 lasted until 1997 when it became known that an investor had bought 3,500 tonnes. Yep, Warren Buffet.
I like both of these however Anglo Asian Mining (LON:AAZ) (Gold, Silver, Copper miner) pay a circa 4.6% dividend right now and look like better value:
Anglo Asian Mining (LON:AAZ)
Yes, but is the lower valuation / higher dividend fair given they operate in the Republic of Azerbaijan. From the CEO letter 23 June
"We were required to acknowledge publicly in August 2019 that the Government of Azerbaijan had announced it had appointed advisors with regard to a possible transaction with Anglo Asian Mining. There have been no significant subsequent events requiring further announcements by us. Nevertheless, I can assure shareholders that it is the Company's understanding that the Government of Azerbaijan has no intention to nationalise, purchase or otherwise take control of Anglo Asian Mining or its assets in Azerbaijan."
Jack, There's no t in Hochschild.
Now I've got that off my mind I'll read the article ;)
Thanks for this Jack. I'd been sat on £PHAG for about 5 years knowing that one day with enough patience silver, in the wake of gold, would start to climb again and faster. As it went north of $20 I bought some Hochschild Mining (LON:HOC) as well and despite recent disruptions think it will come good. Due to the difference in volatility I do view Gold and Silver a little differently. Gold is a hedge against certain risks and forms a core part of my portfolio. Meanwhile Silver is a much more speculative play. As it rises I've bought more and if it gets very high I'll put trailing stops in to sell some as I don't want to watch it go to $50 (fingers crossed!) and back down again without having profited.
Jack - Excellent article; A little additional Silver background from the Daily Mail....
On silver specifically, Russ Mould (AJ Bell) believes that its price will be supported not just by its reputation as a 'safe haven' – alongside that of gold – but its increasing use in key industrial processes. He explains: 'Silver is the best conductor of all metals and also has anti-microbial attributes that make it a perfect biocide. These chemical properties mean it is ideal for industries specialising in medical equipment, electronics, water purification and solar power. As the world focuses ever more intently on renewable sources of energy, solar panels could be a big driver of silver demand.'