Somero: Good portents from Ashteads Q3s, and only on a PE of 10x growing topline 40%
Somero Enterprises SOM.L 113p Mkt Cap £65m
Having seen the strong numbers published by plant / equipment rental business Ashtead yesterday, I thought I would update with a few thoughts on Somero Enterprises. Somero is an AIM listed (£65m mkt cap), US Headquartered, designer / manufacturer of laser guided screed (concrete) machines. These are used to make really flat floors for warehouses and out of town retail space.
https://www.youtube.com/watch?v=rn587OSkTgU
(a quick youtube video of their machines in action)
Operations
Operations are predominantly in the US, which accounted for 53% of sales, with 17% from EMEA and 30% from ROW (China, S America, Korea). The structural drivers here are the demand for more automated picking from warehouses. Automated warehouses need v flat floors. Some customers like Prologis & CostCo have on occasion specified that the building contractor use Somero's laser guided machines. Its clear the company is top of the pack in its field. Also China sales have been growing v fast and a Shanghai office has recently been opened.
On top of that there is a cyclical element, which is huge (ie was great 2005 to 2007 but absolutely terrible for Somero in 2008-2010). No point in sugar coating this, if the non residential construction cycle is for you, great, if not, watch out. The company is currently in an upcycle with sales growth of 40% in 2013 and another 40% H1 14 vs H1 13. Growth is mainly from its large line machines and spares. Geographically strongest growth is in the US and China but the Group is also seeing improved sales in EMEA.
Longer term management is targeting a doubling of 2013 sales by 2018. Realistically this is only a guess as it's a highly cyclical company.
Barriers to entry ?
There's a bit of IP in designing the machines. I read the company has a 99% mkt share in laser guided screed machines. Not sure if I believe this. The company does aim to introduce one new model each year and recent In all Somero spends c2-3% sales on Engineering but in 2013 this only amounted to $900k, so it wouldn't be insurmountable for a competitor to spend say $5m over a couple of years getting up to speed.
The company does have a direct sales force with experienced sales people, in both N America and in a small number of offices around the globe eg Shanghai, UK,
Operational Leverage
In short: Bags of it…A picture is worth a thousand words.
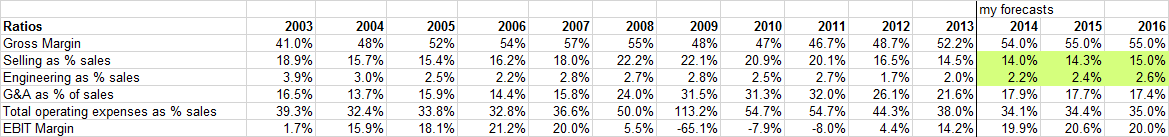
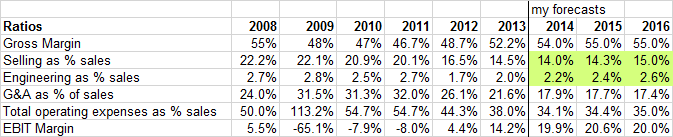
Source: Annual reports, VegPatch forecasts (hopefully you can see the table better in 2 sections)
Gross margins are impacted by sales of larger, higher margin machines which tend to dry up in a down cycle. Following the economic downturn revenues GMs fell. GMs declined from 55% to 47% fell between 2008-10. The company's response was to cut costs. G&A fell by $6m 2008-12 but G&A as % of sales went from 14% to over 30%. Overall EBIT margins fell from nearly 20% to -50% in 2009. However the reverse is true in an upcycle. As non residential construction has picked up margins have massively improved and I think they are likely to go back to 2007 highs.
Balance Sheet
The Balance sheet is net cash, but given what I have showed you about margins I think this is the only sensible position to be in.
Still in an upcycle ?
Yes. The most recent Trading Update on 20th Jan stated:
“Due to particularly strong trading in December, the Board is pleased to announce that it now expects to report EBITDA for the year to 31 December 2014 slightly ahead of market expectations. Demand has continued to be strong across our core existing product range whilst new products have contributed significantly. We have also seen a broad geographic base to our growth, with H2 2014 top line growth driven by sales in North America, China, South East Asia, Latin and South America and Europe.
Based on the continued momentum we have seen across the business in the second half of 2014, the Board expects to deliver further growth in 2015."
Outlook for 2015 and beyond
Banks still easing lending criteria (top chart), while demand for loans is increasing (bottom chart)
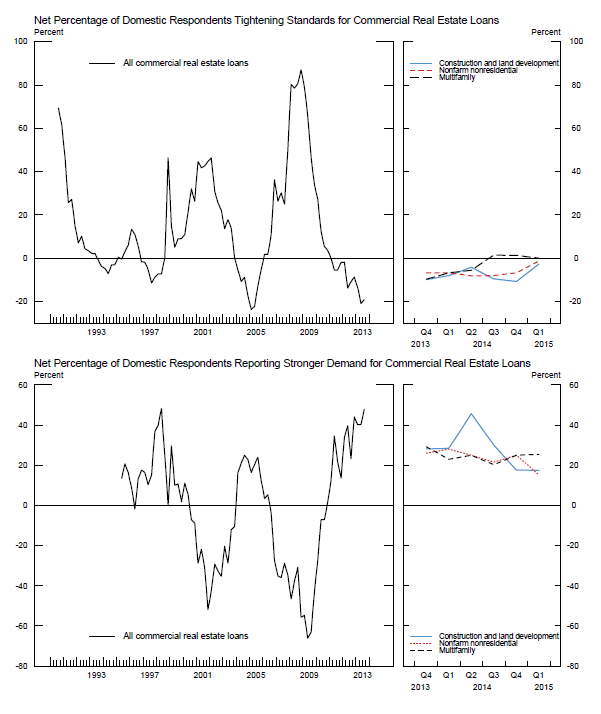
source: US Federal Reserve, Feb 2015
So why did you mention Ashtead at the beginning ?
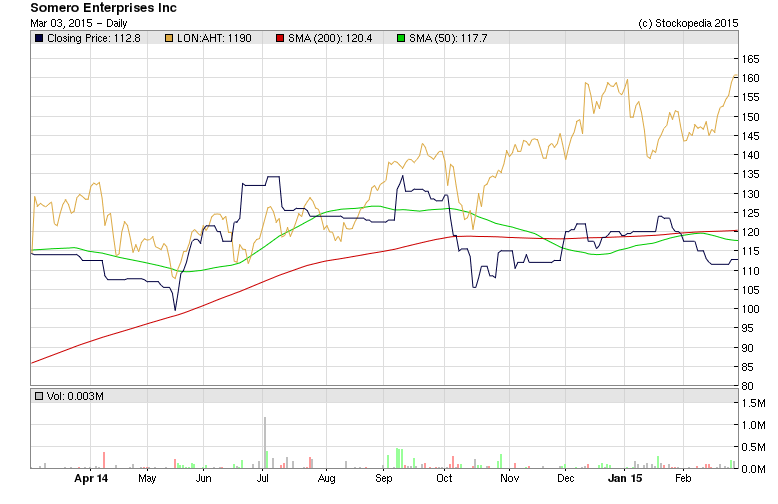
Like Somero, Ashtead (LON:AHT) is highly influenced by the US non residential construction cycle. Its growth has been v strong post the crisis (cyclical) and combined with a competitor in United Rentals who is financially burdened after an acquisition, and a trend more towards rental than ownership (Structural) it has been able to grow very fast. Whats interesting is that Somero has lagged Ashtead (LON:AHT) share price by around 45% since October 2014 (Ashtead share price is the brown line on chart below, Somero's is grey/blue) despite both showing very similar growth dynamics.
Valuation
On my numbers Somero is on 10x PE 2015, which is slightly higher than 9.5x the consensus EPS (I tend to be conservative). I fully understand paying a low multiple for peak EPS but I don't think the US non residential construction cycle is petering out yet. I think we have a another few years to reasonable growth given that private non residential construction activity is still 1/3 below the 2007 and 2008 peak years (I'll admit they were too high though) and fell back to levels in the financial crisis last seen in 2001. So I think there is still pent up demand which will come through as bank lending standards continue to ease. However when I see Ashtead is on 16x April 2016 EPS then I think there both relative and absolute value in Somero. I have bought more today.
VegPatch
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
12 comments
SOM. Check this site. It gives a good indicator at the state of the US construction industry
http://www.abc.org/NewsMedia/ConstructionEconomics/ConstructionBacklogIndicator/tabid/272/entryid/9674/abcs-construction-backlog-indicator-returns-to-earth-in-second-quarter.aspx
I think automated warehouses are the exception not the rule in general. But at the margin they will be a driver of Someros sales.
I would ask your contact
1) does his firm use Somero machines (if not, do they use machines at all? Especially as Somero claim over 90% mkt share). If so are the machines any good? What is the return on investment for a contractor e.g. Spend $100k on a machine and it pays back in terms of 3 less contractors needed
2. Can he give you an overview of the drivers of his business and can he make any comments on national or regional demand for concrete. How does his backlog of business compare now to this time last year? Outlook for next year? What economic signals does he pay most attention to?
3. Any changes in US regulation etc that we may have missed in the UK being thousands of miles away.
4. Any thoughts in general about the industry?
I would be interested to hear the answers.
Thanks
Do you have any estimate for the percentage of Somero's business that is automated warehouse construction?
If this percentage is significant, then it is not the overall statistic for nonresidential construction we care about. We would want to dig for the growth numbers for automated warehouse construction, which might be a substantial multiple of the generic nonresidential construction growth rate.
The family of one of my best friends in high school owns a huge US concrete contractor. He is now one of the key officers of the firm. Are there any due diligence questions you would like answered about Somero, from a customer perspective? I can ask him.
Vegpatch
I agree with you about not having rigid investing rules and my investing style has changed with the books that impress me and the results they produce. Also there is very little that’s new. So for example Mark Minervini and his side kick David Ryan have been heavily influenced by the growth investor William J. O'Neil and all of them promote a style of high PE type investing. Likewise I believe O'Neil was heavily influenced by the legendary momentum investor Jesse Livermore.
At the other end of the investing scale I have tried and struggled with mechanical Rank investing, where the company selections are made for me. But Rank scoring does identify companies that my “Monkey Brain” bias would otherwise miss. I do believe it’s a case of finding investing style(s) that that suit your personality.
There is a lot to be said for a mix of high value, quality and momentum shares within the same portfolio, because there are times in the investing cycle when each of these predominate and a spread of styles covers these bases. At the moment I am trending toward 30% cash and a few more value type shares because of the Geo-political uncertainty initiated by Trump.
I too hold Bioventrix and Somero Enterprises Inc (LON:SOM) - In my top 4 holdings. Ian
I feel Somero Enterprises Inc (LON:SOM) is a likely takeover target, many large construction companies could easily buy this company, my only concern is the US economy, there are doubts about Trumps policies happening. But I agree it still look reasonable value and I'm happy to hold.
Carey,
I agree about not being too late. The Somero Enterprises Inc (LON:SOM) average broker EPS estimate for 2018 is up just +5% which looks too conservative and will be partially depressing the Stocko 12M forward PER calculation of 15x . If SOM beat the 2017/18 forecasts the price is cheap for the return metrics, which is why the price has continued to rise.
Paul mentioned in the Minervini blog that he is no longer focusing on stocks with a low PE. I came to the same conclusion a couple of years back, having looked into the William J.O'Neil investing process. Ian
iwright7
Hi, I was interested in your Minervini / Paul Scott comment.
personally i try not to have rigid rules, but i do try to refine my investing process over time. For the the majority of my personal portfolio i have high quality franchise shares like Bioventix (LON:BVXP), British American Tobacco (LON:BATS), Sage (LON:SGE), Next (LON:NXT) with a smattering of growth companies like St. James's Place (LON:STJ), DP Poland (LON:DPP), opportunistic purchases of asset backed shares like CLS Holdings (LON:CLI) and Mountview Estates (LON:MTVW) which fall into the value bucket and the odd special situation like Somero Enterprises Inc (LON:SOM) or Jersey Oil and Gas (LON:JOG) (now sold).
Somero is a good example. i first analysed and modelled it at 16p, it looked a high risk, cyclical recovery share which was squarely in my Special Sit crosshairs. I liked the odds but before buying i did some further checking then spoke to a colleague who had been a holder. since before the financial crisis. He put me off, saying management wasnt great (in hindsight i think he was confusing the management with the shareprice). Anyway i waited till 50p before pressing the buy button. I have bought and sold along the way but have held a position for the last 4 1/2 yrs.
Whats the point of this ?
1. Be your own investor. If you like the look of a share and have done the work then make the call yourself. Similarly if it doesnt go right, you have only got yourself to blame.
2. Do keep you eyes open and listen to other experienced people. Thats not to say this contradicts the previous point, but you will never be the person to "invent" and idea, so if you hear of an interesting idea eg Bioventix was an idea i heard about in a Stockopedia interview with Keith Ashwell-Lord, but in turn I am told it was suggested to him by Leon Boros, then do some research. Dont follow in blindly but DYOR ! If you want some fun, have a look on ADVFN at a share called BNN Technology (LON:BNN), the amount of private investors that assume that professional investors have better info and therefore follow them blindly is worrying!
3. Everyone has their own system. Find out what works for you.
4. Learn from your mistakes. Of all the rules i have in investing this is the most important one. Analyse your portfolio returns over time and most importantly analyse where you went wrong. If you can cut out the mistakes, you are well on the way to being a "superinvestor". It sort of reminds me of the Charlie Munger quote about death
"All I Want To Know Is Where I'm Going To Die So I'll Never Go There"
If you learnt where your previous mistakes were and never went there again your percentage annual returns would probably go up by at least 5% in my estimation.
Best of British
VegPatch
Interesting to see this old article bumped. A few more pence and it will have tripled in price since the original article. It still has a stock rank of 96, there is a good chance of a special Divi and I still think it has room to run. A P/E of 15 isn't that demanding after all.
Still not too late to buy.
i am glad you appreciated it
Thanks
thanks for the thanks. Hopefully the clue was in the title
Another company I like at the moment, which like Somero hasnt done much recently, is Young & Co's Brewery (LON:YNGN)
I wrote it up a few weeks ago
http://www.stockopedia.com/content/young-amp-co-quality-operator-14x-pe-09x-tnav-5-yr-eps-cagr-15-94180/
Its a long term situation. Very much a quality operator
Have a look (but please do your own research)
Good post VegPatch. Wish i had picked it up when you first wrote it.