Stock Brief - Gulf Keystone Petroleum (LON:GKP)
One of the highest ranked oil & gas producers on Stockopedia, Gulf Keystone Petroleum, is continuing to expand production from its Shaikan Field in the Kurdistan Region of Iraq, just as crude oil prices have $100 a barrel in sight.
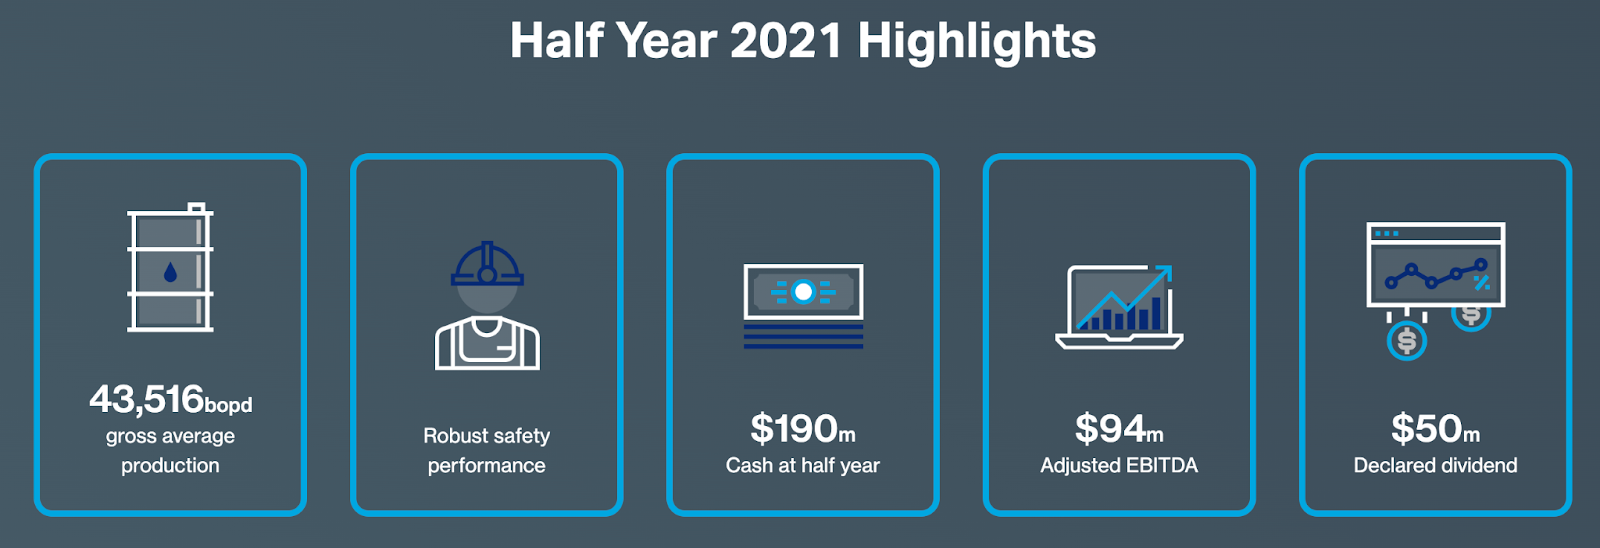
Having produced over 43,000 barrels of oil per day (bopd) in 2021, GKP is targeting production growth to 55,000 bopd over the next year. This production growth, combined with the strong oil price environment and low operating costs have seen the company’s revenues and profits reach record levels. As a result, the company has materially increased its dividend payments and is carrying out substantial share buybacks.
However, given the historically volatile nature of the region and GKP’s single-asset reliance, the shares continue to trade on incredibly low earnings multiples. This could present an opportunity for investors, particularly if oil price fundamentals continue to strengthen, but GKP remains a higher risk investment.

Profile
What are the company's principal business activities, how does it generate its revenues?
Gulf Keystone Petroleum (GKP) generates the entirety of its revenues from the sale of crude oil from its flagship asset, the 280km² Shaikan Field, which has been in production since 2013. One of the largest oil discoveries in the Kurdistan Region of Iraq, the Shakain Field has produced around 92 million stock tank barrels to date (MMstb) and is estimated to contain gross 2P reserves and 2C resources (recoverable oil) of 798 MMstb. This gives a field life of over 30 years at current rates of production.

GKP produced 43,440 barrels of oil per day (bopd) in 2021, and aims to produce between 44,000 and 50,000 bopd in 2022. Under a production sharing agreement, signed with the Kurdistan Regional Government (KRG) in January 2018, all crude oil exports are purchased by the KRG at Brent minus $22/bbl, reflecting quality adjustments and full transportation costs.
Size, Sector & Exchange
At the current share price of 217.5p, the market capitalisation of the company sits at £464 million. As an oil & gas producer, GKP falls under the wider Energy sector and trades on the LSE Main Market.
Business strategy
GKP’s current business strategy will focus on its Field Development Plan (FDP) for Shaikan. The near-term goal is to raise production to 55,000 bopd, with the potential to expand field production to 110,000 bopd over the longer-term.
GKP submitted its FDP to the Ministry of Natural Resources (MNR) in Q4 2021. The plan includes details of the continued ramp-up of its production, appraisal of new reservoirs, and a gas management plan to halve CO2 emissions.
The company will now wait for approvals before commencing further developments with its partner MOL, which owns a 20% interest in the Shaikan Field.
History & Growth
Gulf Keystone Petroleum was founded in 2001, and listed on the London Main Market 3 years later. It wasn’t until 2009 that the Shaikan discovery was made, which was subsequently declared commercially viable in 2012.
Having entered production shortly after in 2013, production growth to 40,000 bopd was achieved by December 2014. Given the decline in the oil price in the following years, plans to expand production to 55,000 bopd were only initiated in June 2018 and should be realised over the next 12-18 months.
Given the strong oil price environment, GKP has rapidly expanded its dividend payments since its maiden dividend in March 2019 and has also initiated share buybacks given its growing cash balance.
Recent News
Dividend payment - Following on from the company’s Operational & Corporate Update on 24th January 2022, the board declared that an additional interim dividend of $50 million would be paid, following $100 million worth of dividends distributed in 2021.
The dividend will be paid on 25th February 2022 to shareholders who were on the register as at 11 February 2022.
Operational & Corporate Update - The most recent company update highlighted GKP’s substantial free cash flow generation in the current oil price environment. Before paying an additional $50 million dividend, the company held $228 million of cash on its balance sheet as at 21st January 2022. This also excludes the remaining arrears balance from the Kurdistan Regional Government (KRG) of $28.6 million related to the unpaid January and February 2020 invoices.
The update did allude to some on-going production issues with a few wells though, as SH-13 and SH-14 productivity has come in below expectations. As a result, the increase in gross production towards 55,000 bopd has been delayed.
CEO, Jon Harris, commented the following: "We are pleased today to declare an additional interim dividend of $50 million, bringing distributions over the past eight months to $150million in line with our commitment to balance investment in growth with returns to shareholders.
Since the beginning of 2022, gross production peaked at just over 50,000 bopd and has averaged c.46,800 bopd, versus the 2021 average of 43,440 bopd. However, the lower productivity of recently completed wells, SH-13 and SH-14, and temporarily curtailed production from SH-12, have resulted in a delay in gross production increasing to 55,000 bopd. 2022 gross average production is expected to be 44,000 to 50,000 bopd.
GKP's substantial production base at current oil prices continues to generate significant cash flow and value for Gulf Keystone's stakeholders. On approval of our recently submitted Field Development Plan, we are well positioned to achieve sustainable growth from the Shaikan Field, which has delivered close to 100 MMstb, and has 489 MMstb of estimated 2P gross reserves remaining."
Catalysts
Trends & Events
Oil price fundamentals are currently extremely favourable for producers. Despite oil prices climbing towards their highest point in 7 years, at $95 a barrel, there is the potential for them to rise well beyond $100.
As Covid-19 restrictions begin to relax in most countries around the world, demand for oil continues to rise. The International Energy Agency estimates that ‘world oil demand is set to rise by 3.2 mb/d in 2022 as restrictions to limit the spread of Covid ease, releasing pent-up demand.’

Source: spglobal.com
Crude oil suppliers haven't been able to respond to the rising demand, and inventories have been drawn down globally as a result, despite the release of strategic reserves by national governments. OECD industry oil inventories reached their lowest level in 7 years in December 2021.
OPEC members continue to struggle with production targets, and the growth in US production has so far been unable to cover these shortfalls. Furthermore, the threat of war in Ukraine could further disrupt supplies and send oil prices shooting past $100 a barrel.
For GKP, upcoming catalysts could include the approval of its Field Development Plan by the Ministry of Natural Resources, asset acquisitions and international diversification, or further dividends or share buybacks.
Risks
What risks does the business face?
Operational - As mentioned in the company’s latest operational & corporate update, production issues can arise at any time. The recently drilled SH-13 and SH-14, which both came onstream in December 2021 have produced below expectations despite an acid stimulation programme and well clean up. SH-12 has also seen production halted due to the appearance of trace quantities of water, which will need to be investigated. This highlights the operational difficulties involved in oil extraction, and the on-going risk shareholders should expect when investing in the sector.
Single-Asset - GKP’s sole asset remains the Shaikan Field. A lack of asset diversification could potentially be holding the company’s share price back, with investors often more reluctant to invest in single-asset oil producers.
Geopolitical - Whilst the Kurdistan Region of Iraq is fully autonomous and has been recognised since 2005, the region remains a geopolitical hotspot. Furthermore, issues with the Kurdistan Regional Government with regard to unpaid invoices for oil supplies during the onset of Covid-19 could also dissuade investors from investing in this jurisdiction.
Macroeconomic - The current macroeconomic environment for oil producers may arguably be the strongest it has been for years, but as the US, Canada and Brazil ramp up production, current supply issues may start to fade away next year. The US Energy Information Administration (EIA) expects inventories to start to rise again from Q2 2022, which could put downward pressure on oil prices.
Summary
Bull points
Expanding oil production as prices near $100 a barrel, cash balance in excess of $200 million and rapidly growing, generous dividend distributions and share buybacks, Shaikan Field has low operating costs, large reserves and is a potential 30+ year asset
Bear points
Recent operational difficulties with new wells coming online resulting in delays to the 55,000 bopd production target, notable lack of asset diversification and significant reliance on the Shaikan Field, perhaps more favourable jurisdictions to invest in
Gulf Keystone Petroleum’s current valuation has seemingly priced in most of the risk factors, but whilst the company continues to rely solely on its Shaikan Field, it may struggle to command a higher valuation.

Nevertheless, at current oil prices, very few mid caps on the London market will be able to generate anywhere near the same level of free cash flows as GKP. Production is growing at a very opportune time and there are a number of catalysts that could continue to drive the share price higher in the coming months.
As the cash pile continues to build on the company’s balance sheet, it will become harder for the market to ignore the increasingly attractive fundamentals.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
For those not up to speed, I think Gulf Keystone Petroleum (LON:GKP) counts as a "meme" stock now.
Open confession: I don't know if Private Investors (myself included) are being suckered or not.
This was 200p a share. The Turkey pipeline closed in March due to a complex legal dispute. The share collapsed to 80p.
There is a contingent of Private Investors holding the bag, currently around 116 to 124p hoping this pipeline reopens and Baghdad does a deal.
There is a Short Seller war, although the Short Hedge funds appear to now be retreating.
This is probably the Game Stop and Blood Bath & Beyond of British oil companies. Lots of speculation that if Baghdad agrees to license GKP to operate, the share rebounds, possible a take over target.
I am now deeply committed into this.
Victory to the little people!
Interesting, but prefer Serica Energy (LON:SQZ)
I liked the review of Gulf Keystone Petroleum.
You were right to highlight the political risks here and indeed there was a significant development this week. Iraq's federal court has ruled that all KRG contracts with oil companies, foreign parties and states are invalid. This includes exploration, extraction, export and sale agreements. Watch this space!
I see very few articles on this sector - which I actively trade.Stocko has a big blind spot here
Hi SaarfLondon,
Thank you for your feedback.
We will endeavour to provide more coverage of energy stocks in the future. We'd like our Stock Brief selection to be guided by the community, so this feedback is greatly appreciated.
As the fundamental picture continues to improve for oil & gas related equities, more companies will inevitably fall across our radar.
Kind regards,
Keelan
Very good to see Stocko publishing on oil E&P companies. As an ex petroleum engineer and City oil analyst, I commend you on the approach taken. As you state, there is significant operational risk here, Gulf Keystone Petroleum (LON:GKP) have consistently missed production targets due to the complexity of the fractured carbonate reservoir that holds the oil. As such production targets and reserve numbers should be given a haircut - but definitely value here if the government pays up at higher oil prices.
Do you have other preferred E&P stocks for further research Pentago?
Frankly I prefer to do my E&P hunting in the US, because the majority of UK E&Ps either have challenging reservoirs or balance sheets. I do like the management teams at Jadestone Energy and Savannah Energy (LON:SAVE) as they are doing something different. Although I have been worried about pricing power in OFS, I think the indications are that shale and OPEC spending needs to continue increasing - and I see Hunting (LON:HTG) as a beneficiary of the former and Petrofac (LON:PFC) and even Lamprell (LON:LAM) of the latter, as being interesting at current price levels
Hi Pentago - do you have a view on United Oil & Gas (LON:UOG) and the management team there?