Stock Brief - Serica Energy (LON:SQZ)
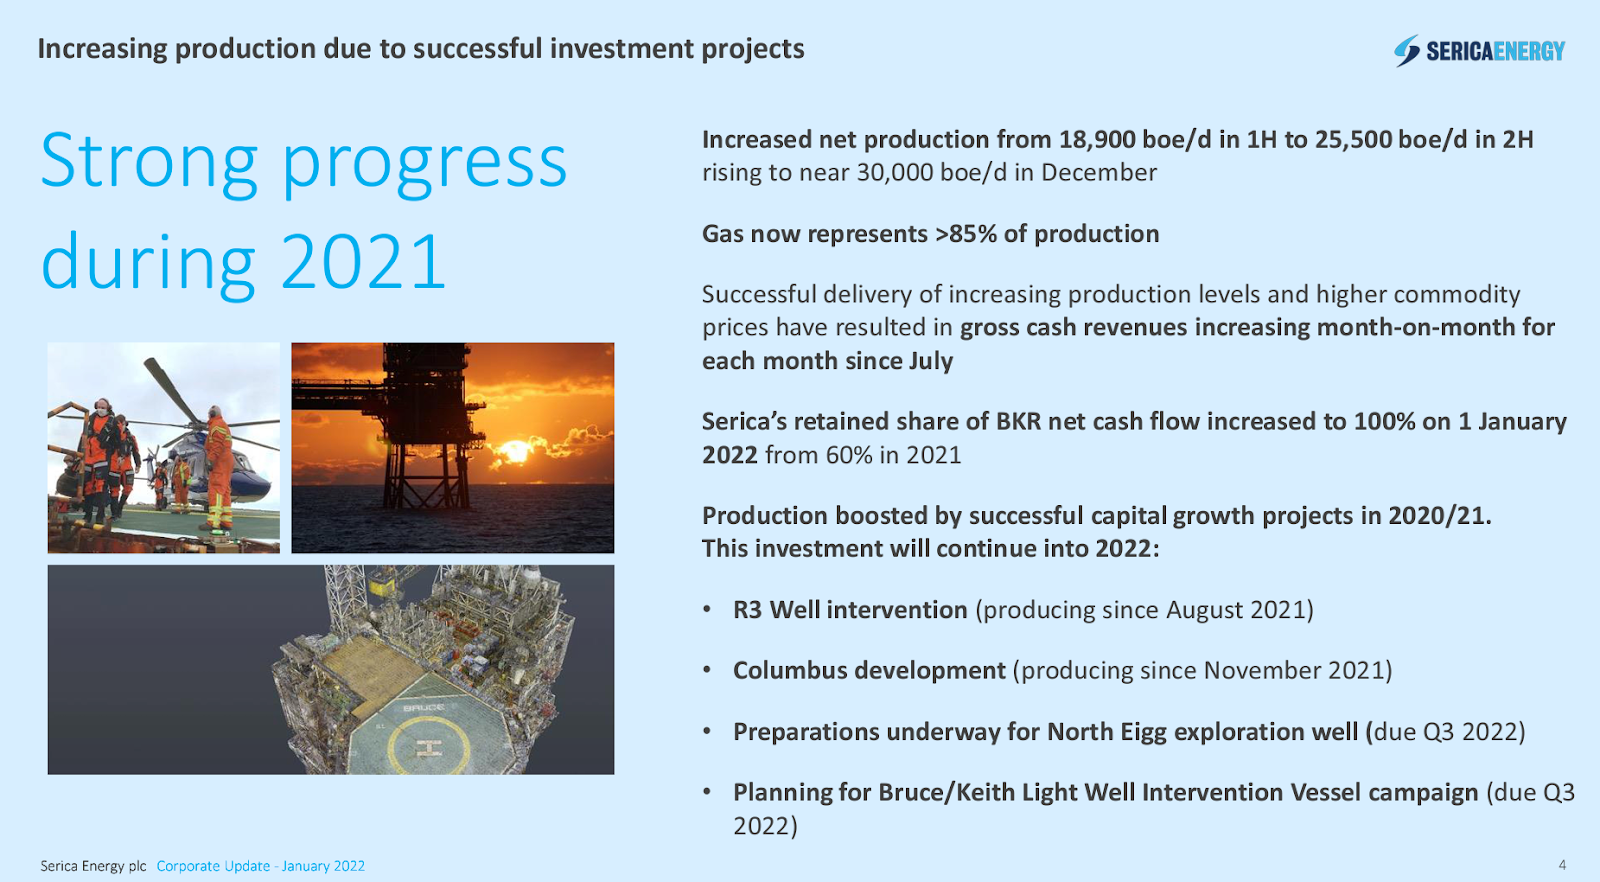
Serica Energy shares are currently trading at all-time highs, with the share price set alight by soaring natural gas prices over the past year. The company is currently responsible for over 5% of the UK’s natural gas supply, and continues to expand its productive capacity, recently reaching nearly 30,000 barrels of oil equivalent per day (boe/d) in December 2021.
Serica’s success story has been reflected in both the share price and the company’s financial performance. Its most recent corporate update highlighted a cash build to over £218 million as at 31st December 2021. This figure is only set to grow as the company now retains 100% of the net cash flows from its Bruce, Keith and Rhum (BKR) fields in the North Sea, though 50% of Rhum is still owned by the Iranian Oil Company (IOC).
The unfortunate recent developments in Ukraine, and the looming threat of another world war, continue to push gas prices higher as energy supplies become increasingly uncertain. Despite prices falling back since the pre-Christmas 2021 peak of 450p per therm, they remain 6 times higher than this time last year.
With the fundamental backdrop for energy prices being so favourable, is there still value left to extract in Serica’s shares?
Profile
What are the company's principal business activities, how does it generate its revenues?
Serica is a UK based upstream oil and gas producer, with a range of production and exploration assets located in the North Sea. Over 85% of the company’s current production now comes from natural gas, which accounts for over 5% of the UK’s entire natural gas supply.

Serica’s production assets include the Bruce, Keith and Rhum fields in the UK Northern North Sea. The company also operates the Columbus field and maintains an interest in the Erskine field, in the central North Sea. Combined, these fields currently produce nearly 30,000 boe/d net to Serica, guidance for this year is in the range of 27,100 and 33,600 boe/d. Proven and probable oil reserves (2P) from these fields stand in excess of 61 mmboe (million barrels of oil equivalent) as of the 1st Jan 2021.
The company’s management team have notable experience in the North Sea and are experts in optimising the use of new technologies to maximise production and extend field life.

Size, Sector & Exchange
Given the 269 million shares in issue, at the current all time-high share price of 292p, the market capitalisation is in excess of £785 million.
Serica operates in the Energy sector, under the Oil & Gas industry and its shares are listed on the LSE AIM Market.
Business strategy
As previously mentioned, Serica's unique advantage lies in its technical skill set and management expertise in extracting the maximum value from its asset base in the North Sea. Its future strategy will continue to revolve around this theme, with management actively targeting opportunities where it can add value.
The company has a proven track record of improving the performance of wells through workovers and extending their field life. For example, the R3 well reintervention on its Rhum subsea gas field in 2020/21, boosted production from 12,900 boe/d net to Serica to 19,000 boe/d net.

Equally, Serica’s net 2P reserves at acquisition for its Erskine interest in 2014 was 3.6mmboe. Since this time, net production from Jan 2014 to Jan 2022 has reached 4.97mmboe (138% of original) and net reserves now still total 2.46mmboe (68% of original).
The company has already confirmed that planning is underway for a Bruce/Keith Light Well intervention campaign in 2022, which could add further production. There will be greater anticipation for the North Eigg exploration well though, which is scheduled to spud in Q3 2022. The well is part of the greater North and South Eigg structure, potentially targeting prospective resources in excess of 100mmboe. North and South Eigg are directly adjacent to the company’s existing Rhum block.

Serica’s strengthening balance sheet not only provides it with the capex it requires for its current field developments and exploration projects, but also with the capacity to take on lucrative opportunities as and when they arise.
History & Growth
Serica's historical strategy has focused on identifying assets in the UK North Sea where the management team can apply its expertise to unlock value. Formed in 2004, the company only acquired a working interest in a producing field in 2014, when it acquired an 18% interest in Erskine.
The acquisition of the Bruce, Keith and Rhum (BKR) fields from BP in November 2018, was a transformational moment in the company’s history. Serica became an operator for the first time, and was able to effectively apply its expertise to simplify workflow processes, increase production uptime, reduce operational costs and extend field life.
Today, Serica is a company with over 150 employees, 5 producing fields, and 2 exciting exploration assets in the North Sea.
Recent News
Rhum Production Update - A fault was discovered in the Rhum Subsea Control Module, which resulted in the temporary shutdown of Rhum production. No safety or environmental issues so far, however, production will likely not resume for at least two weeks.
Production at Bruce and other fields have not been affected. A further update will be provided when Rhum production is restarted.
Mitch Flegg, Chief Executive of Serica Energy, commented:
"This is a frustrating event, but I am confident our skilled teams onshore and offshore will safely and efficiently implement the required repairs using equipment and plans already in place to deal with such a situation. Production from Bruce, Erskine and Columbus has consistently averaged over 10,000boe/d net to Serica so far this year. We expect these rates to continue during the Rhum shut down and we will look for ways to optimise the Bruce production rates during this period."
Corporate Update - A strong update pointing out the contribution of R3 well and Columbus field, with Serica’s production reaching 85% gas. Key operational and financial highlights included :
- Rhum R3 well put into production in late August 2021. Rhum production significantly boosted, adding up to 6,000 boe/d net to Serica.
- First production from the Columbus field achieved in late November 2021. Early production initially constrained due to temporary unavailability of full capacity in the export system. Average rates of 3,270 boe/d net to Serica now achieved in the period up to year-end.
- BKR net cash flow sharing arrangements ended on 31st December 2021. As of 1st January 2022, the company retains 100% of the net cash flow from BKR.
- Average realised gas prices of over 113p/therm and oil over $70/bbl.
- Cash pile grew to £218.4 million at 31st December 2021, consisting of £103 million held in cash and deposits and £115.4 million as temporary security with gas price hedge counterparties.
- 20% of 2022 gas production hedged, leaving considerable upside exposure.
Mitch Flegg, Chief Executive of Serica Energy, commented:
"2021 was a very busy year for Serica, which reinforced the value of our through-cycle investment strategy as our expenditure during the low gas price environment of 2020 on the R3 and Columbus projects bore fruit this year. The importance of our contribution to the provision of vital lower carbon gas to the UK's energy market was also demonstrated. We will continue to pursue our investment-led strategy this year with a planned well intervention programme on Bruce and Keith in addition to our exploration well at North Eigg. As always, we continue to look for acquisition opportunities that fit our criteria and will add value for our stakeholders."
Catalysts
Trends & Events
UK natural gas prices hit all time highs as recently as December 2021 and are still significantly above their historical averages. The demand dynamics remain strong as natural gas adoption continues to increase. This is primarily driven by the fact that natural gas emits a lot less carbon dioxide than other fuels and is therefore necessary for our global transition towards carbon neutrality.
The supply side looks a lot more concerning, though potentially rewarding for Serica. Russia may decide to turn off its gas supplies to Europe, and other nations that continue to support Ukraine. In this case, prices may once again soar to new record heights. However, should the opposite occur and a peaceful resolution is found, a lot of the uncertainty will be removed and gas prices may fall quite abruptly. The current trends are favourable for Serica, but geopolitics must be taken into account here.

Serica will report its full year results in April. Further catalysts might include an acquisition, plans shareholder returns, or the drilling of the North Eigg well in Q3 2022.
Risks
What risks does the business face?
Operational - Offshore wells are much more costly and complex to operate than their onshore counterparts. As shown by the fault discovered in the Rhum Subsea Control Module on 28th February 2022, issues can flare up in spite of the most rigorous operational preparedness. In this case, there have been no safety or environmental issues, but production will be hit for at least 2 weeks. This will have a notable impact on company revenues as it accounts for approximately 60% of group production.
Exploration - Serica plans to spud its North Eigg exploration well in Q3 2022 at an estimated cost of approximately £45 million. Should the well disappoint, this will also throw the prospectivity of South Eigg into doubt.
Growth - The company’s large cash pile continues to grow daily and could reach in excess of £300 mil by the end of Q1 on current forecasts. With no debts, pressure from shareholders may start to mount if shareholder distributions or acquisitions are not made. This may lead to management acquiring assets in an unfavourable pricing environment in the pursuit of growth.
Geopolitical - The events over the past week have demonstrated just how volatile the world stage is today. It is impossible to predict what might happen over the coming weeks, but investors would do well to closely monitor developments and assess their risk exposure accordingly. Serica is currently a beneficiary of the natural gas pricing environment, but that could change in an instant.
Summary
Bull points
Serica’s net cash flows are set to grow rapidly as the company’s share of BKR rises, cash on balance sheet already over £218 million, attractive valuation with 12m forecast P/E of 2.9, extremely favourable natural gas price environment, field workovers at Bruce/Keith could provide additional production growth, North Eigg exploration well may add significant resources if successful
Bear points
Difficulties in operating offshore wells as highlighted by the recent issues with the Rhum Subsea Control Module, gas prices highly dependent on geopolitical factors at this time, company looking for acquisitions but may be forced to pay over the odds for M&A in this environment, lack of growth prospects if North Eigg well disappoints, small dividend yield
Brokers are having to revisit their price targets for Serica higher on the back of its 100% ownership of BKR, increased production rates and elevated natural gas prices. Jeffries recently raised its price target from 290p to 360p, and rated it a ‘buy’.
Serica represents a unique opportunity as a leading mid-sized North Sea focused natural gas play. The company is in a relatively secure position, due to its importance to the UK’s natural gas supply and rapidly growing cash reserve.

However, the market has taken notice of this and the shares are now starting to command a premium as a result. If natural gas prices start to retreat, the share price may fall just as quickly. Although, ceteris paribus, a sustained period of natural gas prices beyond the current 250p per therm could turn the company into one of the greatest cash cows on the London market. Definitely one to keep an eye on!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
I was very surprised to see how much these shares have fallen back. They are now only 11% above pre-war levels having been as high as 45% up! Although the fighting is now more limited to eastern Ukraine, a peaceful solution isn't in sight and it could all flare up again if Putin starts losing and lashes out with WMD.
I suppose this is because of the steep drop in UK wholesale gas prices. tradingeconomics.com attribute this to "warm weather prospects, ample LNG supplies, and fading concerns over Europe’s access to Russian gas"
I notice there has been quite a pullback on some smaller energy stocks whilst Shell (LON:SHEL) and £BP are still going up, any ideas for the reason?
lots of theories, nothing concrete!
The broker did The sale of BP stakes in a way to dump the shares, probably causing some second thoughts and profit taking.
They have had a good run, but even after the beating they took today, they still trade on a PE of 1 to 2.. I’m still holding the rest of the year, picked a few more up today!
I did top up Serica Energy (LON:SQZ) today, don't really understand the fall when oil and gas prices are still high. I did sell some £BP on friday.
thanks , very interesting
I used Serica Energy, as an example recently, to show the benefits of doing your own research (with a calculator). Details Here! Mick (DIYinvestor).
Hi DIYinvestor,
Thank you for your comment. I really enjoyed your thorough analysis in the video! It perfectly demonstrates how investors can stay ahead of the market using their own up-to-date forecasts. Estimates often lag by a few months at the best of times and valuation mismatches are where the opportunities lie!
Kind regards,
Keelan
Hi Keelan,
Many thanks for you kind comments. For those of us interested in small to medium sized companies, where they're not covered by analysts, it can be the only way to get a feel for what's going on.
I also 100% agree with you that valuation mismatches can provide great opportunities!
Kind Regards, Mick (a.k.a. DIYinvestor)
Hi Keelan, I was 1.6% out (below) the actual figures and despite the run up in price, since I created the Youtube video (14th Feb 2022), the prospects for 2022 IMO remain excellent. For those of us that have held Serica Energy (LON:SQZ) for a while, the proposed dividend of 9p (an increase of 157% on 2021) represents a very nice return on our purchase cost!
With Serica benefitting from 100% of the BKR assets in 2022 and onwards, that's a 66% increase on output (at a much higher price per boepd)!
Any thoughts?
Mick (aka DIY-Investor)
hi Mick,
Yes you were very close. Pretty excellent results yet still they got a hammering yesterday!
The results was written like a funeral speech. Maybe to down play its results a bit to pacify the windfall tax loons?
The upside will be this year as you pointed out. Though i MAY trim back my position as its become a huge % of my portfolio.
Saying that its hard to find a company with a better cash flow?
Hi Roodini,
Yes, the recent news is also very interesting… I’m preparing another video presentation, based on my updated research and pointing out a few things that indicate where the results have been downplayed IMO.
Mick.
fantastic work. Been holding £Sqz for a year now and had done some digging but your video was amazing work. Thanks
Cerica, interesting and informative write up. Hard to draw any firm conclusions. Tangible equity falls at an average of avout 4% relative to MCap pa over the past 4 years. Some modest share issuing over the past 4 years, but then this last year Serica seems to have bought back nearly all the extra shares issued over recent years.
Big build up in intangibles though, clearly a lot of expansion going on here, how and when reserves are shown on the balance sheet requires specialsed knowlege to fully understand I think, cash position looks decent as well.
I have invested in oil/gas and oil services in the past. Ithaca to 2017 gave me 6 fig gains, Kentz was a key holding before its buy out c2014 and Perofac was great for me in 2009 to 2010, although I lost money on PFC in 2017, which highlights the unpredictability of the sector.
Assuming that the inevitable small oiler operational risks run favourably, it will all come down to the oil price, the long term outlook is unfavourable in my view, but for the next few years, perhaps the next 3 to 5 years, the oil and gas price outlook looks pretty good.
Personally, I don't feel inclined to invest in this sector now, partly becuse investing in oil/gas can affect my capacity to sleep soundly and partly because the post 2016 UK specific and other global headwinds have now thrown up compelling bargains in lower risk UK facing sectors. And no, risk and reward do not need to go together, if you analyse stocks correctly, you can have your cake and eat it, low risk, high reward.
One thing that I will say about Serica. When analysing, I started by looking at the balance sheet and saw the huge build up in intangibles, linked to the very strong cash position. Those two observations don't normally go together without massive share issuing having happened. So I looked at the share issue record to see for myself. The small number of additonal shares issued over the past 4 years have almost all been bought back, this does suggest that Serica takes the wealfare of its shareholders seriously and clearly the business is highly cash generative at the moment.
Is Cerica good value at this price? I think that is very hard for me to judge, certainly an interesting business though.
.
Correction I think is needed on Rhum. It is my understanding that 50% of Rhum is owned by the Iranian national oil company and hence Serica needs an annual licence from the US to operate the field because of the US sanctions on Iran. This has always been granted in the past few years. Whilst it is correct to say that Serica will now benefit from 100% of the production of their 50% share of the field, income from the other 50% accrues to Iran.
Hi Ned,
Thank you for pointing this out! This will be updated to make sure the 50% holding of Rhum by the IOC (Iranian Oil Company) is clearer.
Kind regards,
Keelan
you have to question if Serica is a UK company operating in UK waters, why on earth do they need the permission of the Americans to operate. The Americans have been spreading democracy around the world to oil producing countries at the end of a missile for years, so for them to have a say in the operation of a UK company really get on my nerves!
Blimey - never seen a £300M cash pile being called a risk!
As far as Warren Buffett is concerned, capital allocation is the KEY RISK to consider when assessing a management team.
"Over time, the skill with which a company’s managers allocate capital has an enormous impact on the enterprise’s value
After ten years in the job, a CEO whose company retains earnings equal to 10% of net worth, will have been responsible for the deployment of more than 60% of all capital at work in the business."
Hi Mikex1,
As Epsilon has very well put, capital allocation is indeed a key risk factor to consider. In fairness to Serica's management team, they have an excellent track record here.
However, a £300 million cash pile might embolden the management team to take on riskier, more ambitious acquisitions, which may not be in the best long-term interests of the company and its shareholders. We've seen many examples of management teams destroying shareholder value through acquisitions in the past. That hopefully won't be the case here, but it is always worth considering!
Kind regards,
Keelan
Biggest holding at moment and after recent run. Is unusual for a smaller North Sea oil and gas producer to be debt free and have negligible decomissioning costs.
Slight worry is North Eigg not being successful and management overpaying in present climate to secure production long term, although been cautious and generally adept so far.
Great report Keelan . Yesterday i dipped my toe in but i'll wait to see how things develop with the war. The Russians could win the war but unlikely win the peace which means the whole thing could drag on for some time.
Another broader play on the energy market is the Etf £SPOG up 4% today with 66% US , 17% Canada and only 5% Russia.