Stock in Focus: Drax could be a cash cow

My SIF stock screen is delivering a fairly minimal set of choices this week. Just eight companies satisfy all of my screening requirements. Of these, four are in the portfolio, two are ruled out on diversification grounds, and the final two are overseas stocks.
This situation arises periodically and doesn’t concern me. Indeed, I see it as a sign that the screen is working as intended, filtering for affordable growth. What I often do at times like this is to experiment with disabling individual rules in the screen.
I usually find that there’s one rule in particular which is limiting my choice of stocks. This week is no exception. By disabling the rule requiring a trailing earnings yield of more than 8%, the number of stocks in the results jumps from eight to 44.
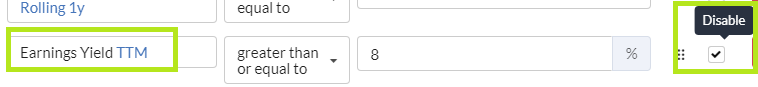
By making this change, I was hoping to find companies whose operating profits were hit by one-off costs last year. These might have been related to the pandemic or some other factor. Such companies might normally pass all of my rules and could potentially be cheap.
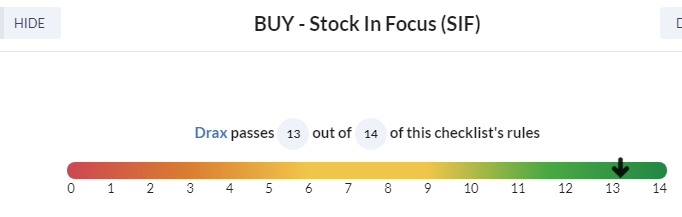
One example appears to be utility group Drax (LON:DRX), which is also a member of this year’s NAPS portfolio.
Drax booked £226m of “coal and other asset obsolescence charges” in 2020. Without these, the company’s underlying operating profit would have left it with an earnings yield of 7.4% -- close to my 8% minimum.
Last year’s losses reflect the company’s final farewell to coal generation, which substantially ended in March 2021. Most of the company’s generating capacity has now been converted to biomass (wood pellets) and Drax now provides c.15% of the UK’s renewable electricity.
Opinions vary on how sustainable biomass generation really is, but that’s a debate for another place. The reality is that biomass is supported by UK government policy and by a subsidy scheme that runs until 2027.
In 2020, Drax received a staggering £837m of subsidy payments from the government, against power sales of £2,164m.
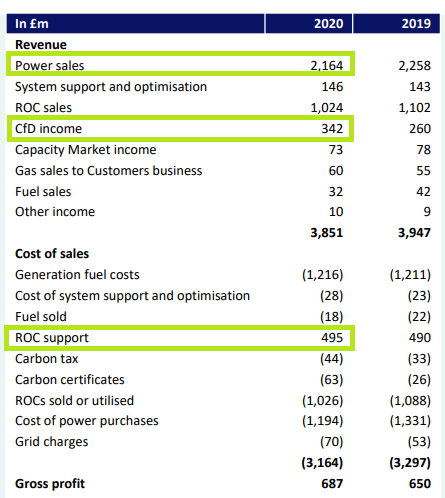
Source: Drax FY20 presentation
With this kind of tailwind, I reckon Drax could be a potential cash cow.
Stockopedia rates Drax shares quite highly too, with a StockRank of 83. However, individual factor scores are mixed, with a high MomentumRank, but a lowish QualityRank.

Let’s take a closer look.
Value: reasonably priced
As this is a utility stock, I’m looking for a modest valuation and an attractive yield. Drax’s ValueRank of 70 looks promising. Drilling down into the value factors which make up this score reveals a mixed picture:

We must also consider a few other valuation metrics:
Earnings yield: My understanding is that last year’s asset impairment charges were mostly one-off and non-cash, so I’d be prepared to adjust them out.
Using the company’s adjusted operating profit of £189m, Drax has an earnings yield (EBIT/EV) of 7.4%. That’s just below my threshold of 8%.
Price to earnings ratio: Using the normalised eps data from Stocko’s data provider gives Drax a trailing P/E of 22.
However, if we’re prepared to accept the company’s own adjusted measure, this falls to a more reasonable P/E of 15.
Dividend yield: Drax has made several dividend cuts over the last decade, but the payout was increased last year. The shares have a trailing yield of 3.9% - above the FTSE 100 average of 3%.

Debt: The company’s latest update indicates that its net debt/EBITDA ratio should fall to 2x by the end of 2022. Borrowing has risen since the year end due to the acquisition of Pinnacle, the company’s Canadian biomass supplier.
This level of leverage is towards the upper end of what I’m comfortable with, but the company’s subsidised and regulated cash flows suggest to me that the situation is unlikely to become problematic.
Verdict: I think Drax looks reasonably valued, but not obviously cheap. Free cash flow was stronger than earnings last year, which seems to support my view that I can safely ignore last year’s non-cash exceptional charges.
If Drax’s quality and momentum characteristics are positive, then I can imagine this stock could have some upside potential.
Quality: better than it looks?
The ValueRank is a backward-looking metric, in keeping with the tradition of value investing. The QualityRank includes a mix of measures designed to highlight both historic profitability and forward-looking trends. It’s intended to identify companies with improving quality metrics.
Profitability: For a variety of reasons, Drax has performed poorly in terms of reported profit in recent years. This is reflected in very weak profitability scores:

Cash generation: However, free cash flow generation has been more consistent and generally improving. In the graphic below, we can see that dividends have been well-covered by free cash flow since 2016:

F-Score: The Piotroski F-Score includes nine tests to see if the company’s financial performance is improving. The F-Score is heavily-weighted in the QualityRank due to its predictive qualities.

I think it’s worth noting that all three of the failures in the F-score breakdown relate to last year’s reported loss. The other measures - relating to cash generation and pricing power -- all show improving trends.
This seems to support my view that if we filter out last year’s transitional events, Drax could have positive momentum.
My verdict: I think that Drax’s ability to generate attractive free cash flow and fund dividends could form the basis of an investment case for the stock, at the right price.
Momentum: a strong setup
Drax’s MomentumRank of 93 suggests that the market has a positive view of the outlook for the business. For our purposes, this factor rank can be divided into two elements.
Price momentum: These technical factors give us a snapshot of a stock’s trading volumes, price action and performance against the wider market.
All of this information is captured in a useful snapshot at the top of the StockReport:

The only area of weakness seems to be the 10d/3m volume change. This suggests buying has fallen off recently. However, I think this needs to be seen in context.
Drax shares surged in March, after the company published its annual results and announced the acquisition of its main biomass supplier. We’re just coming out of the tail end of that three-month comparison period. I suspect the volume change metric will improve as this market-moving event falls out of the numbers.
Earnings estimates: I’m looking for a rising trend of earnings forecasts, as history tells us that companies which beat expectations often outperform for longer than expected.
Broker forecasts for Drax have been upgraded more than once over the last three months:
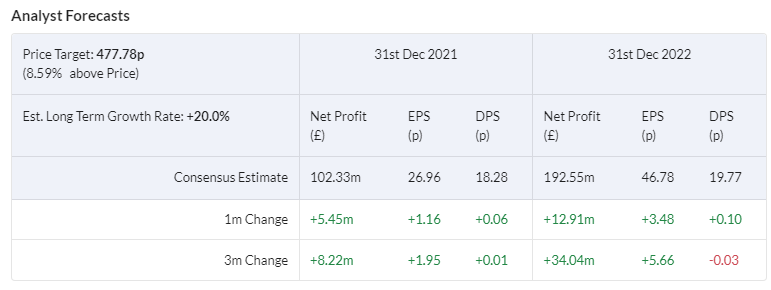
The outlook for 2022 is particularly bullish, as we can see from the brilliant broker consensus trend chart:

My verdict: Drax appears to have strong momentum. This seems to support my view that the company’s profitability and cash generation could improve as the business moves on from the transitional events of recent years.
The stock’s rolling forecast metrics for the next 12 months look attractive to me and satisfy all of my screening tests:

Note the strong forecast earnings (eps) growth. This implies a 2022 forecast P/E of just 9.4, with a 4.5% yield. If Drax can deliver on this, then I think the current valuation could start to look usefully cheap.
My decision
Drax comfortably satisfies all of my screening rules except the earnings yield requirement. This reflects (what should be) last year’s one-off losses, marking the end of the firm’s coal operations.
I’m tempted by Drax but I’m not going to buy the shares this week. The reason for this is that even using the underlying earnings yield of 7.4%, this stock still doesn’t quite pass all of my screening rules. I don’t want to overpay for a heavily-geared business whose outlook beyond 2027 is still - arguably - uncertain.
To hit my target earnings yield of 8%, I estimate that Drax’s share price would need to fall by about 10%, to around 400p. This may seem unlikely right now, but after such a strong run I wouldn’t be surprised to see the stock pull back a little.
I’ll keep an eye on this situation over the coming weeks and if pricing improves, I may choose to add Drax to the portfolio. Of course, if I do, I’ll mention it here before taking any action.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
I hope everyone gets chance to watch the Panorama documentary televised last night on Drax.
for years now I have been banging on to people that Drax is THE single biggest poster child for eco vandalism, possibly on the planet.
Chopping trees down with deisel power machines, shipping to the Uk and burning. It’s utter madness to satisfy the politicians who are handing out backhanders to the eco lobby in the form of “subsidies”.
part of the grift that electric vehicles are powered by renewable energy.
EEV = emission elsewhere vehicle
Well finally Panorama laid it all out in display.
https://www.bbc.co.uk/programm...
Drax is the UKs biggest CO2 emitter.
The saying” it’s an I’ll wind that’s blows no one any good “is one that certainly applies to Drax (LON:DRX) with gas prices going through the roof it’s wood pellet and hydro assets have never been more important for electricity generation
Also this https://www.bbc.co.uk/news/bus...
Also this https://www.bbc.co.uk/news/bus...
Big move up for Drax (LON:DRX) today only info I could find was the following which I copied from another site so only taken at face value
Though Barclays have increased target price to 960
Stock Rating: Overweight
Industry View: Positive
Price Target: GBp 960 (from GBp 550)
Price (14-Sep-2021): GBp 436
Potential Upside/Downside: +120.2%
Tickers: DRX LN / DRX.L
We believe Drax contains significant share price upside potential. We increase our PT by 75% to 960p, implying 120% upside potential: Since our last update (May 2020) we see notable improvements to the Drax investment story but little change to the share price. We believe the current price is an attractive entry point.
The next Orsted? We now value the NPV of BECCS, pellet and pumped hydro expansion at £575mn (145p/share), which was previously £50mn. BECCS to us has the feel of offshore wind in 2005 – marginal current economics and a large niche area but with significant potential. We see Drax becoming a global leader in developing and operating these complex BECCS projects both in the UK and globally, and we estimate a long-term upside scenario valuation of 3800p, or 8.8x the current share price.
Option 1: Power price 'bubble' will increasingly lead to material earnings and cash upgrades. Drax is c.30TWh hedged over the next three years, but there is 3TWh of unhedged output in 2022 (20% of total output) and 6TWh in 2023 (40%). The correlation between power prices, bark spread and the Drax share price has broken since Drax joined the S&P global clean index (May 2021), and we believe it should reconnect. Every £5/MWh power price change is c.£500mn NPV to Drax, in our view.
Option 2: Pellets. Drax's ambition is to self-supply 5mn tonnes, and we estimate further export is possible. 3mn tonnes expansion would equal an NPV of £800mn, all else equal.
Option 3: BECCS. A global emissions technology game changer. We estimate that BECCS could have a value of up to £10bn NPV. The first unit may be operational by 2027, but we see significant potential for further UK and global expansion.
Option 4: Pumped hydro. Drax is planning to invest £500mn to increase capacity by 600MW. We estimate this would provide a further c.£70mn EBITDA and £320mn NPV.
https://gridwatch.co.uk/
Here is a very informative site to track power generation
It is very informative. Renewables are wood, food residues and straw. Burning wood is not carbon neutral.
In my opinion, Drax is about as unethical an investment it is possible to make as it is investing in worsening droughts and flooding caused by environmental destruction, due to it policy of burning wood, which releases more carbon than coal.
As unethical an investment as it is possible to make !!!!
Burning wood pellets is worse than coal do you have any evidence to back up both statements ?
Drax (LON:DRX) There is some evidence, I have heard from various sources, here is one: https://www.pri.org/stories/2018-06-20/uk-s-move-away-coal-means-they-re-burning-wood-us
I'm also not keen on cutting down ancient forests to replant with young trees which is what is happening with Drax in the US.
is that it that’s all you’ve got And from reading that you deduce they are committing slash and burn of ancient forests ??? I hope you put more research into stocks you do like
Have a good weekend my friend
No there are other articles. I researched it a few years ago and it was not from that article. As I said that is only one of several.
have you read the info on the wood pellet operation that Drax recently bought and the rational behind buying it ?
personally I think you are just virtue signalling and basing your views on hearsay what I find interesting is why you feel the need to tell people what they should invest in basked on your view of the world and what you think is right and wrong rather than the financial benefits of holding a share do you have the same views on Unilever for instance and their use of palm oil
Maybe we should start a different thread where you and others can tell everyone why people shouldn’t invest in certain shares because of what you think of the company and your obviously superior morals
You sound like a control freak who rather than concentrating on what they invest in themselves wants to control what everyone else does with their money
I suggest you need to read what people write more carefully. Where did I tell people what to invest in?
hahahaha you are so funny
So you think people should invest in Drax yes or no ?
It is up to them to decide.
Thanks at least that’s one thing we can agree on like I say worry about what you do yourself and your own actions before you do anything else
https://www.theguardian.com/bu...
Drax has now purchased Pinnacle Renewable Energy Inc.
The Guardian article quotes a letter, that states: Pinnacle uses wood from a climate-critical forest that has been home to Indigenous peoples for millennia, and is a breeding site for more than 3 billion North American birds and the home of many endangered animals."
Also, for what it's worth, wood burning stoves are recognised to be polluting and are bad for asthmatics, so it is accepted that burning wood is bad for the environment.
https://www.theguardian.com/en...
Finally,, even the pro-business Daily Mail has let rip about the dangers of Drax (see previous link).
so yes or no
so you think they will cut down all the trees in one go not on a rotational basis ?Are you against cutting down trees ever for other uses building etc what would you use instead ?what fuels would you rather use to generate electricity ?because you can’t do it just with wind and solar ?
biomass and pumped hydro along with gas and probably nuclear 2 of which Drax use are the options available at this time and for the foreseeable future
Give me you options ?
https://thenarwhal.ca/bc-wood-...
"Independent supply base audits by the Sustainable Biomass Program found that 28 per cent of Pinnacle’s woody biomass comes from primary feedstock – meaning directly from the forest – in B.C. Their most recent supply included yellow and western red cedar, trees that should be left standing even if they’re diseased, according to registered B.C. forester Eric Matzner."
"Bioenergy smokestack emissions are higher than coal because burning wood isn’t as efficient."
Therefore, going back to burning coal would be better, overall, as it's more efficient and does not have such a catastrophic environmental effect.
you are forgetting that the carbon produced is taken out of the atmosphere and stored by trees before being burnt where as the carbon in coal has been locked up for millions of years
That carbon stored in trees will be released after the tree dies and rots or if there is a forest fire any way
Is that not true ?
You need to think through what you are saying
Also with carbon capture burning wood pellets would be carbon negative actually take carbon out of the atmosphere
https://en.wikipedia.org/wiki/National_Observer_(Canada)
And if you are looking for a neutral view I suggest you look somewhere else
Maybe you should start a campaign to return Drax to being coal powered ?
Thanks for the suggestion. Here's a paragraph from the relevant National Observer article:
"As to why people should care, Parfitt says there are a few reasons. Not only are the environmental implications severe, but the industry produces few jobs. Just over 300 people work in the pellet industry in the province, scattered across 14 mills — a half a per cent of the total number of forestry workers."
https://www.nationalobserver.c...
So, you've got mature forests being razed to provide power for Drax. Now, some might say the forests will grow back naturally, but the trend is for more droughts and flooding worldwide. With flooding, soil gets washed away and the land becomes barren. Also, with no forest cover, heat from the sun is radiated back into the air instead of being absorbed, resulting in increased worldwide average temperatures.
Now, take a look at the financial summary for Hiscox Hiscox (LON:HSX) and Lancashire Holdings (LON:LRE) and Beazley (LON:BEZ).
Revenues are increasing but profits are tumbling. The costs of insuring against environmental catastrophic events are increasing all the time. Thanks to Drax, the profits of such insurance companies are likely to fall further. Ultimately, the entire insurance industry will be at risk. And if firms can't get insurance then we can look forward to a scenario depicted in films such as Planet of the Apes or Mad Max 2!
Hahahah thanks for that really made me laugh out loud Hahahahaha
Always best to start the day with a bit of comedy
You're welcome.
It remains to be seen if one day Big Ben will be seen poking out of the sands like the Statue of Liberty did in Planet of the Apes!
You have an imaginative mind my friend
Thanks for that image that first planet of the apes film was a classic
Pleasure. Courtesy of the film Evil Dead: Army of Darkness, here's a shot featuring a Big Ben maybe of the future:
http://theonyxpath.com/disquie...
100% agree. Drax is the poster child of state sponsored Eco-vandalism.
The mental gymnastics required to believe shipping 20000 tons of trees across the Atlantic to burn as a “renewable energy” is truly spectacular.
At the same time, making it illegal for home owners to buy logs for wood burning stoves from local suppliers, and forcing the industry to import wood from abroad.
Millions of years ago coal was essentially trees. They died and became coal.
Yet rather than use that as a fuel source, the Greenwash industry, along with massive cash bungs from the mentalists in parliament (all parties) seems to think cutting down new trees is “renewable”
https://www.dailymail.co.uk/ne...
The odd thing is that when forest fires rage it is regarded as bad for the environment in terms of carbon emissions, yet when hardwood trees are burned to create energy, it is somehow great for the environment.
I would not rule out a screeching u-turn with regards to government subsidies in the future.
Great research and write up. I like everything you say about this stock, but I've also read recently somewhere (can't remember exactly where) about its longer-term future and its green-washing of its credentials (you state some of this).
With so much risk hanging over its 2027 and beyond future and the fact that it seems to import wood all the way from Canada then I fear it is only one very small step away from some hugely negative ESG and long-termism press.
To this end I am finding the risk/reward balance uncomfortable. I wish all holders well and hope that there is no sudden blip in the road, but "I am out on this one."
BTW - maybe I am just a bit sore from yesterdays Best Of The Best (LON:BOTB) "blip" and am being overly cautious as a result :-)
You're right to be cautious - in a heavily regulated, and subsidised industry such as this, the fortunes of Drax (LON:DRX) can instantly change with just one change in government policy.
Exactly, and especially so when the policy being subsidised at Drax (LON:DRX) makes no actual environmental sense. It’s a matter of time until it gets changed.
It makes sense that in that the carbon absorbed by a tree in its lifetime growing will be released when it dies whether it is burnt or just dies and rots away would you not agree ?
The big break through will be when they start the carbon capture when you will be taking trees that have absorbed carbon from the atmosphere while growing then burning the pellets you produce from them to generate electricity which will be carbon negative by pumping the carbon underground
Anyone who thinks we won’t need nuclear gas and biomass in the medium term is not thinking clearly unless you want to spend those cold foggy days in the winter sitting in the dark and cold ?
Drax does have its hydro power stations to produce power at these times and has announced it is looking to expand there site on loch awe also but with an expanding population and increasing electricity use in my opinion biomass will be with us for some time to come look at one of the sites that tracks power by its generation to get an idea of what types of power generation generate our power and when
For me its great to see the Stocko metrics used and abused and learn how to use them.
There is no 'tick box' answer to investing or protecting your capital and contributors should not be at risk of lawyers trying to make a fast buck, defending tips, recommendations, etc.
The big mags maybe have big lawyer budgets but I don't want my subscription charge to rise through leech action.
Thanks for the excellent write up Roland.
I have been a holder for over 12 months, have added to and this is now one of my biggest positions. Both the share price and income have done better than I initially thought, by which I mean have got to where they now are quicker than I thought they would.
More good news;
1. A recent trade report has estimated that actions by the National Grid to balance the energy market under 'volatile and difficult circumstances' earlier this year, means Drax achieved a price in January '21 of £387/MWh, roughly doubling revenues on the same period in the previous year.
2. Drax has recently signed a long-term deal for carbon capture technology with Japan's
Mitsubishi Heavy Industries, paving the way for negative emissions from its UK (Selby, Yorkshire) plant by 2030.
I must admit I read the whole article with the belief that you were going to buy - bit of a twist at the end there!
Hi Norfolk'n'Good,
Thanks for your comment and the extra info.
I admit I was tempted to buy Drax (LON:DRX) this week, but in the end I decided that I should stick to the rules. I am hoping the market will let me add the stock in the coming weeks - we'll see.
Roland
Actually what I should have drawn your attention to Roland is the recent (21/4/21) Longspur note on Research Tree. EPS forecasts for next 4 years, if achieved, should ensure some pretty hefty share price rises.
Now you're tempted....?