Stock in Focus: Family firm Henry Boot ticks (almost) all the boxes

As I write this on Monday, the FTSE 100 is up by more than 5% on following news that the Pfizer/BioNTech vaccine for COVID-19 could be 90% effective. Although the trial results haven’t yet been published and peer reviewed, they appear to be better than expected. Widespread deployment of the vaccine could bring the end of the coronavirus pandemic into sight. Apparently the UK government already has 40m doses on order.
Battered stocks such as Rolls-Royce, Cineworld and Carnival are enjoying double-digit gains. Airlines are flying too. However, I’d argue that even in a best-case scenario, the outlook for equity in these firms is likely to remain uncertain for some time. Many have taken on significant amounts of new debt in order to survive the pandemic. In my view, even a return to 2019 trading could leave many of Monday’s high-profile risers in need of several years of intensive deleveraging.
That’s not to say that there aren’t some good buying opportunities out there. But I think it’s worth considering how easy it will be for highly-geared firms to repair their balance sheets without further equity dilution.
This theme of balance sheet strength leads me to the sector I’d like to talk about this week: property.
Hidden value in this unloved sector?
Commercial property stocks have suffered badly in the pandemic and many now trade at a big discount to book value. However, a fair number of firms have managed to maintain healthy balance sheets. I can see value in this sector on a medium-term view.
At the big cap end of the market, British Land (I hold) and Landsec look safe enough to me. Both have promised to restart dividend payments this year. Moving down to mid caps, I believe that central London landlords with high-quality estates - such as Shaftesbury (I hold) and Derwent London - will also recover well in time.
The company I want to look at this week is a little different. According to its website, Henry Boot (LON:BOOT) operates “across the whole property value chain. We acquire land without planning permission, obtain planning permission, develop sites and maintain an investment portfolio”.
The group’s operations are structured in this way for a reason. Construction and property investment provide reliable cash flows, but at relatively low rates of return. However, this cash flow can be funnelled into land and development opportunities. These generate higher returns, but are also lumpier and more cyclical.
Boot’s business model is easier to understand with the help of this graphic, which I snipped from a video on the firm’s website.
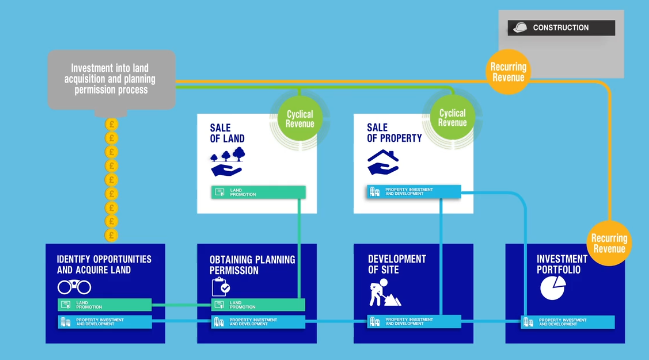
The company says that this structure enables it to minimise gearing while still generating attractive returns. This certainly seems to be true. Henry Boot reported a net cash position at the end of June and has generated an average return on capital employed of 14% since 2014.
I won’t be adding this share to the SIF Folio, as Boot’s business overlaps too heavily with that of FTSE 250 firm Morgan Sindall, which I bought for the portfolio in March and reviewed in August.
However, I’ve long had a favourable impression of Henry Boot and might be interested in other circumstances. In this piece I want to take a closer look and ask whether now might be the right time to buy.
BOOT passes my tests
This £325m firm has been dipping in and out of my SIF screen over the last few weeks. The reason for Henry Boot’s intermittent presence in my screening results is that the shares’ liquidity is poor.
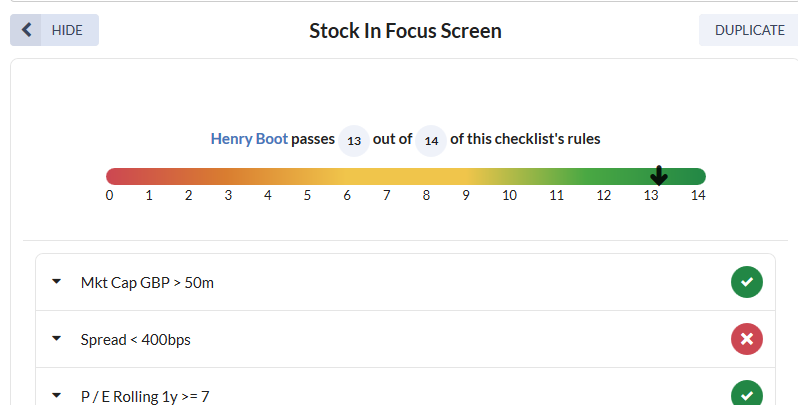
According to Stockopedia stats, the exchange market size is just 1,000 shares - less than £2,500 of stock. My screening results suggest the spread regularly exceeds 4%. However, I suspect patient investors can probably buy on better terms than these.
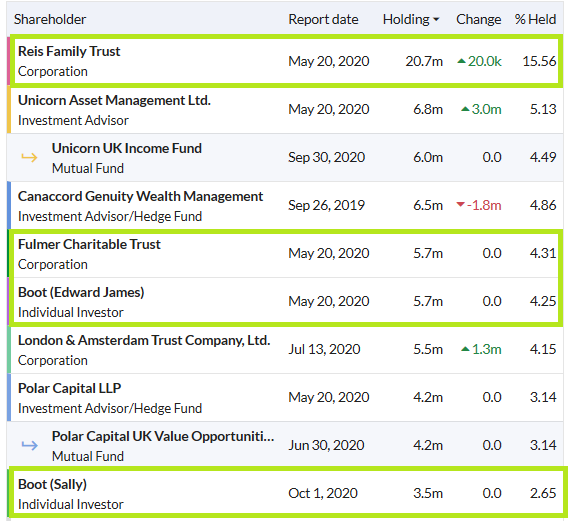
One potential attraction is the continuing involvement of the founding family. Chairman Jamie Boot has been with the company since 1979 and has run all four of the group’s main operating subsidiaries during his career.
Another positive is continuing family ownership. As far as I can see, family interests control around 27% of BOOT shares:
Let’s move on to take a look at Henry Boot’s QVM factor scores. Is there an opportunity here to buy quality at a reasonable price?
Value: solid
At first sight the situation seems promising. Henry Boot is trading in line with book value and at just seven times trailing free cash flow, according to the Stocko stats:
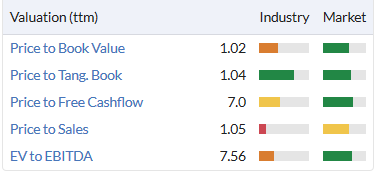
Book value: The company reported a NAV of 232p per share at the end of June, so this price/book ratio looks about right to me. It’s also worth noting that the NAV was unchanged from a year earlier. As yet, the firm doesn’t seem to have needed to impair the value of any of its assets. This stability may be linked to the fact that 74% of the group’s £1.4bn construction pipeline is in industrial and logistics assets, where demand has stayed strong.
Free cash flow: I think that the price/free cash flow ratio shown above has been boosted by favourable working capital movements as a result of COVID-19. Essentially, reduced levels of activity levels during H1 led to a reduction in both receivables and payables. However, on a full-year view I’m comfortable that this is a cash-generative business - albeit with the lumpiness you’d expect in this sector.
Earnings: Profits have obviously suffered this year, but BOOT stock still looks attractive using my favoured valuation measure:
Earnings yield (EBIT/EV): 10.7>#/p###
One possible caveat is that the company has already said that it doesn’t expect profitability to return to 2019 levels “for some time”. This suggests that this historic ratio may not provide an accurate indicator of near-term future performance.
Summary: I don’t see anything much to dislike in Henry Boot’s valuation. In my view, the stock is probably quite reasonably valued at this level.
Quality: above average?
Boot’s QualityRank of 92 suggests a strong showing in this regard. I wouldn’t disagree. For a construction and property company the firm’s profitability metrics look impressive to me:
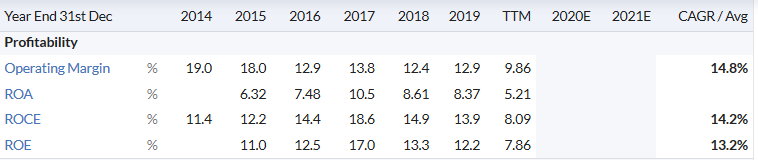
The other key element of the QualityRank calculation is a stock’s Piotroski F-Score. This measure of financial health looks at profitability, cash generation and balance sheet health. Boot’s falling profit mean that the stock fails some tests, but it still manages a respectable score of 6/9:
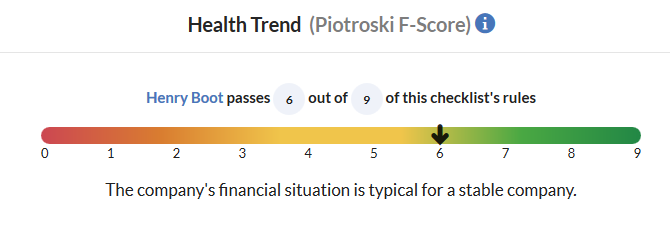
I don’t see anything much to dislike in Boot’s quality score.
As I’ll now explain, my concerns revolve around whether this is the right time to be investing in this business.
Momentum: uncertain
Boot’s MomentumRank of 52 is the weakest of its three factor scores. In the circumstances, I don’t think this is surprising.
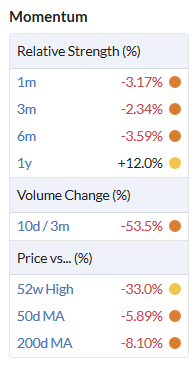
Price momentum: The outlook is uncertain from a technical perspective. I can’t see any bright spots in this graphic:
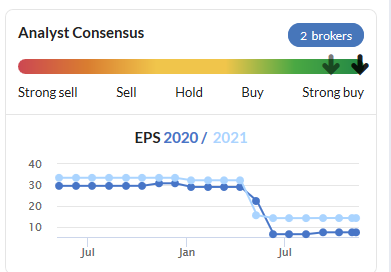
Earnings estimates: The outlook for profits is also uncertain. Earnings are expected to fall this year and only to make a partial recovery in 2021:
The company has already started making construction workers redundant. I wonder if it could take some time for profits to return to the levels seen in recent years.
This could be significant, as the shares currently look quite fully priced to me, relative to earnings. According to Stockopedia, broker forecasts price the shares on a 12-month rolling forecast P/E of almost 18. This year’s dividend cut means the yield is relatively modest for a property stock, at 2.4%.
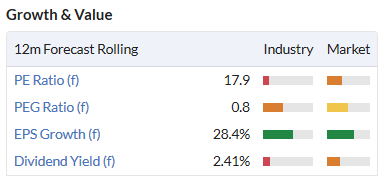
Measured against the book value of 232p per share, the stock looks more reasonably valued. But to make a final decision, I think a broader perspective is required.
My verdict
Here’s how Henry Boot has performed against the FTSE All-Share Index since 2000:
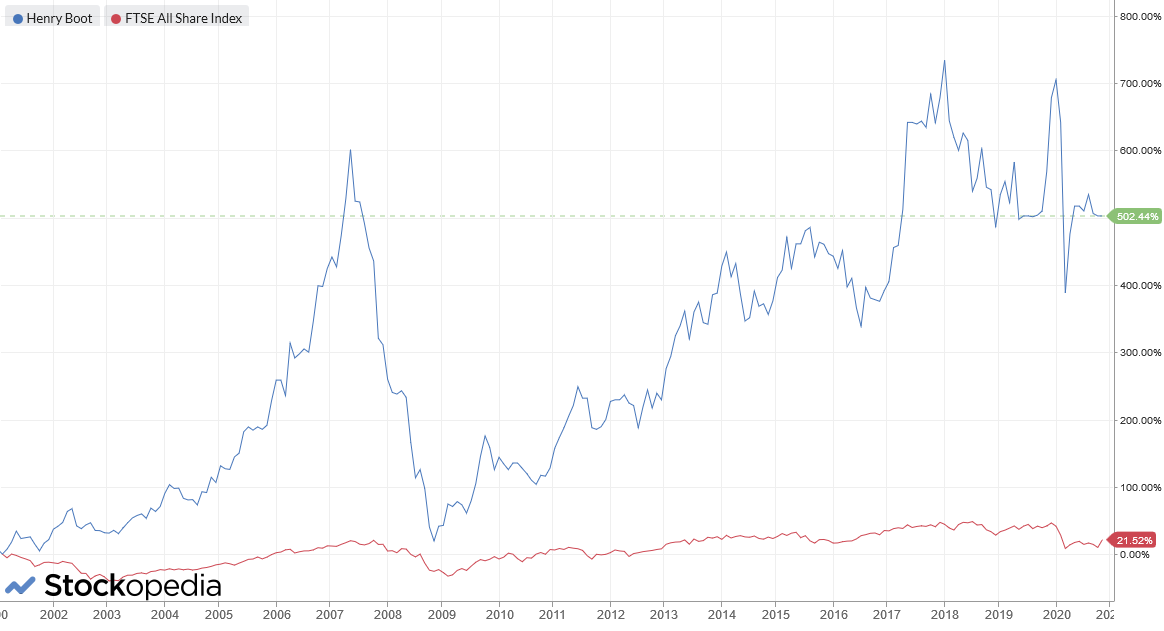
It’s an impressive track record and I can certainly see some appeal in these shares as a possible long-term investment.
However, for me this chart begs one big question: where are we in the current property market cycle? I can see two possible scenarios:
The bull case is that the construction and property sector could bounce back quickly next year, assuming the pandemic recedes. In this scenario, I think Boot shares could offer good value at current levels.
A more bearish view is that we’re only at the start of a longer recession. In this scenario, I can imagine that Henry Boot’s pipeline of construction work and land development opportunities could gradually decay, taking years to recover. The shares might not be cheap after all.
I’d love to know what you think about this. To paraphrase Churchill, is this the beginning of the end, or merely the end of the beginning?
Disclosure: At the time of publication, Roland owned shares of Morgan Sindall, British Land and Shaftesbury.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Heres a good pointer..... family owned companies which BOOT is outperform other companies in recessions/bear markets. A nice reminder and pointer from IC magazine last week.