Stock in Focus: Imperial Tobacco

"I'll tell you why I like the cigarette business. It cost a penny to make. Sell it for a dollar. It's addictive. And there's a fantastic brand loyalty." - Warren Buffett (1987)
Although Mr Buffett is thought to have some reservations about the issues facing the tobacco industry, there’s no doubt that this quote captures the innate quality of Big Tobacco, from an investment perspective.
FTSE 100 member Imperial Tobacco has delivered a 136% total return for shareholders since 2009. A capital gain of 97% has been topped up with a generous dividend payout that’s risen by an average of almost 10% per year.
Tobacco firms like Imperial have proved that advertising restrictions, constant tax hikes and a thoroughly dangerous product are no barrier to financial success.
The addictive nature of tobacco helps, of course. A cynic might even suggest that the tax hikes help too, as they enable tobacco firms to slip through their own price increases under the cover of a rise in tax...
What’s really happening?
The reality is that the tobacco industry is seeing a structural decline in sales.
My calculations suggest that Imperial’s tobacco volumes have fallen by an average of 2.8% per year since 2009. Total volumes have fallen by 18%, from 347bn stick equivalents in 2009*, to just 294bn in 2014.
The tobacco industry is responding to this change by consolidating and focusing on fewer brands. Imperial’s marketing is focused heavily on its portfolio of ten growth brands, from which revenues are rising.
In June, the group completed the acquisition of a number of US cigarette brands owned by Reynolds American and Lorillard. These assets were being divested as a result of the merger of these two firms, one of which (Reynolds) is part-owned by British American Tobacco.
Concentrating ownership in this way and reducing the number of brands to a relatively small number of widely-recognised premium brands has paid dividends. The adjusted operating margin of Imperial’s tobacco business was 43.3% in 2014, up from 42.9% the previous year.
Full-year profits for 2015 are expected to be 40% higher than last year.
Still good value?
After such an impressive performance, you wouldn’t expect Imperial stock to be cheap. Yet the shares don’t look expensive and have qualified for the James O’Shaugnessy Cornerstone Value Screen since January 2013.
Imperial’s ValueRank of 69 would be higher were it not for the firm’s price-to-book ratio of 5.98.
All the other key value metrics are pretty reasonable. A trailing P/E of 13.6 is complemented by a price-to-free cash flow ratio of 11.5.
This highlights Imperial’s tremendous ability to generate cash. Few stocks have a P/FCF that’s lower than their P/E ratio.
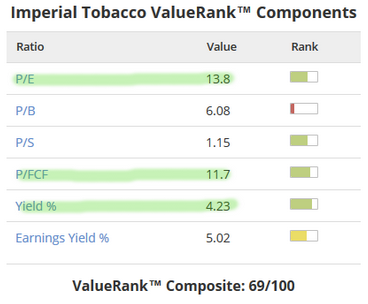
The dividend yield remains attractive, at 4.2% on a trailing basis. It’s worth noting that Imperial’s dividend has been covered at least 1.5 times by free cash flow since 2009. This should be a safe payout for the foreseeable future.
The only slight question mark is an earnings yield of just 5.1%. The reason for this is that Stockopedia calculates earnings yield using enterprise value, or market cap plus net debt. Imperial’s low earnings yield reflects its high level of debt. I’ll look at this more closely in a moment.
A quality smoke
Imperial’s QualityRank of 94 suggests that the British firm has all of the attributes identified in the Warren Buffett quote at the start of this article.
Stockopedia’s Guru Screens certainly suggest this stock is likely to outperform on quality. Imperial qualifies for the Quality Income Screen and the Screen of Screens, suggesting it might be a good bet for long-term income investors.
We’ve already seen that once you strip out duty and tax, making and selling cigarettes is incredibly profitable. The moat-like qualities of premium tobacco brands are also well understood.
However, Imperial’s long-term return on capital employed of 11.1% is only a little better than average. This correlates with the firm’s gross profit to assets ratio of 20, which is also pretty average.
In my view, these numbers reinforce the logic behind the tobacco industry’s gradual consolidation. A lot of capital is tied up in these firms, but by scaling up, efficiencies of scale help boost returns to worthwhile levels.
Imperial’s Piotroski F-score of 8 confirms my view that the group is profitable and has a decent balance sheet. However, it’s worth commenting on Imperial’s net debt of £9.6bn, which is almost five times the firm’s operating profits.
This is higher than I’d normally like to see. However, Imperial’s strong free cash flow and interest cover of 55 suggest to me that it’s unlikely to become a big issue, unless interest rates rise sharply.
Serious momentum
Where Imperial scores most highly is momentum. The firm qualified for the Earnings Upgrade Momentum Screen in June and has a MomentumRank of 97. This not necessarily what you’d expect from a dividend stock in a mature industry.
However, Imperial’s acquisition of a US brand portfolio as part of the Reynolds-Lorillard deal has transformed expectations. Earnings per share are now expected to rise by 21% in 2015, and by a further 15% in 2016.
The group is continuing to benefit from earnings upgrades, too. Interim earnings beat expectations by nearly 6%. Next year’s earnings estimates have risen by 10.8% during the last month.
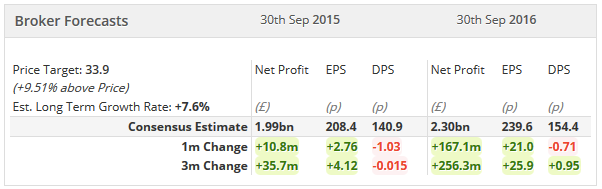
All this has given Imperial strong price and earnings momentum:
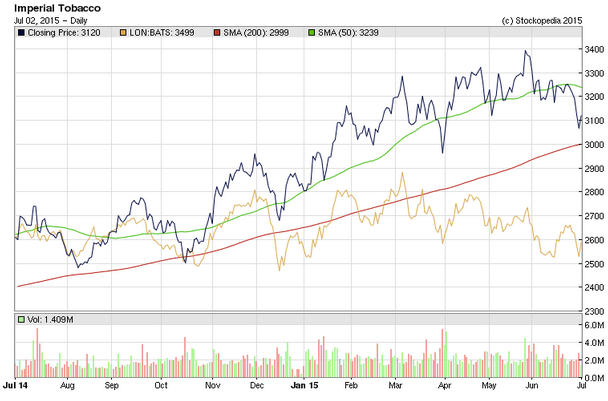
Imperial has outperformed both the FTSE 100 and its larger peer British American Tobacco by around 20% over the last twelve months.
Outlook
Is Imperial Tobacco still a buy? Top fund manager Neil Woodford continues to be a big believer, and Imperial is the third-largest holding in his income fund, at 6.96%.
The Stockopedia data suggest to me that Imperial is likely to continue to generate above-average returns for shareholders.
Offsetting this for some investors are ethical considerations, plus the fact that Imperial no longer lags behind BATS in terms of share price performance.
I’d say that Imperial shares are fairly valued, but please DYOR, as always.
*Based on reported cigarette volumes and tonnage of fine cut tobacco sales, using the industry-standard 1g/cigarette stick equivalent conversion, as explained here: http://www.esta.be/esta-on-smoking/eu-taxation-of-...
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?