Stock in Focus: I’m troubled by ESG and surprised by Impax Asset Management

I’m a firm believer in a quantitative approach to investment - relying on the power of data and proven factors to select stocks. One of the things I like about investment is the intellectual challenge of the process and the way in which it can be abstracted from day-to-day life.
However, by detaching myself in this way, I wonder whether I’m doing my full duty as the part-owner of a business. Focusing only on a company’s numbers can make it uncomfortably easy to condone things for which I wouldn’t want to take personal responsibility.
I don’t claim any kind of moral high ground here. I’ve profited from owning shares in a number of businesses that I wouldn’t want to work for. But I’m starting to wonder whether I’m comfortable with this situation, or if I need a more structured approach to ethical and environmental issues.
I’ve been having a think about how I might do this, and have come up with three options.
DIY: As a general rule, I only invest in stocks that I’ve selected myself. I don’t generally buy funds, either.
Logically, if I wanted to take ethical investing seriously, I’d have to understand the issues, do my own research, and form my own ranking system.
That sounds like a lot of work, unless I could use tools such as Stockopedia to develop a screening system that recognises ESG (Environmental, Social and Governance) factors. This would be an interesting project, but I’m not yet convinced that I could make meaningful ESG judgements from financial data alone.
The index tracker option: ESG investing is increasingly on institutions’ radar. Index providers such as MSCI and FTSE Russel have developed ESG scoring frameworks and related indices to facilitate investment in well-ranked companies.
However, the top holdings from each provider’s UK ESG indices suggest heavy concentration, and very few obvious themes:
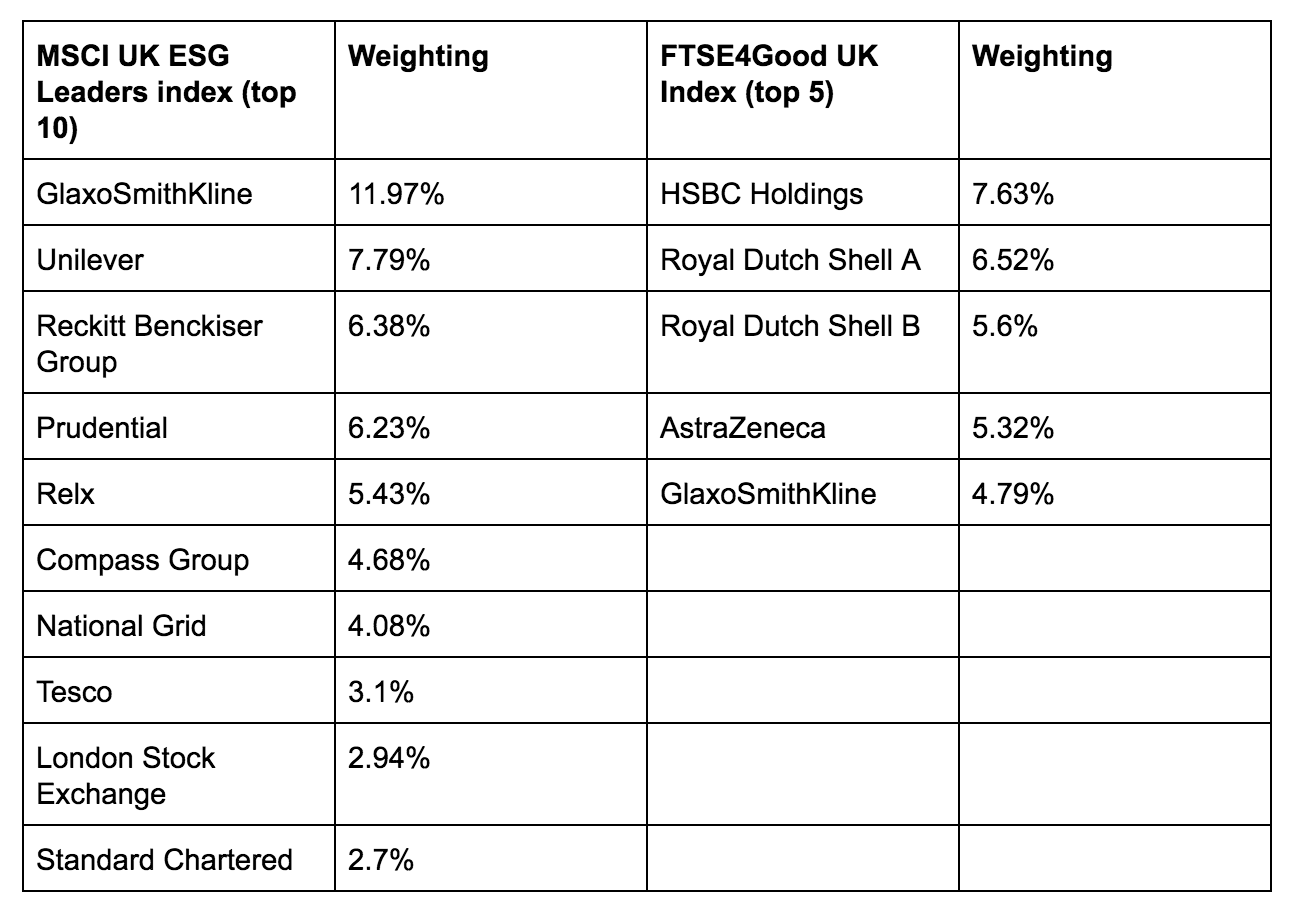
Source: MSCI UK ESG Leaders Index factsheet, 31 July 2019, FTSE4Good Index Series factsheet, 31 July 2019.
Judging from these stock selections, FTSE and MSCI use very different sets of criteria to score firms for ESG. This highlights one problem with ESG investing -- existing rating systems appear to be highly subjective and inconsistent.
I own several of these stocks and would be happy enough to own most of the others. But I’m not sure I’d describe all of them as a force for good.
These ESG indices haven’t been great performers, either. Returns have been similar to those provided by a FTSE All-Share index tracker over the last 10 years. Overall, I can’t see any compelling reason to buy into ESG tracker funds.
Invest in a specialist: AIM-listed impact investing firm Impax Asset Management has grown assets under management from £2.7bn to £14.5bn over the last five years. The IPX share price has risen by 420% over the same period.
Although this stunning growth has been aided by the 2018 acquisition of Pax World Management, I still can’t think of any other reputable UK-listed asset managers with comparable performance.
Browsing through the firm’s ESG policy, I note that part of their system involves two proprietary ‘smart beta’ frameworks, which score companies on gender leadership and sustainability.
Alongside this, the firm does a lot of fundamental and issues-based analysis, all of which contributes to an ESG score for each company.
The right time to buy? I’ve followed this stock with casual interest for a while, but my impression was that it had become too expensive to be an attractive pick for a value-focused investor like me.
However, I note that the shares have now fallen by 17% from June’s all-time high of 295p. So I ran Impax through the Stock in Focus checklist to see whether Impax might qualify for the SIF screen, which looks for affordable growth plus momentum. The result was much closer to a clean sweep than I expected:
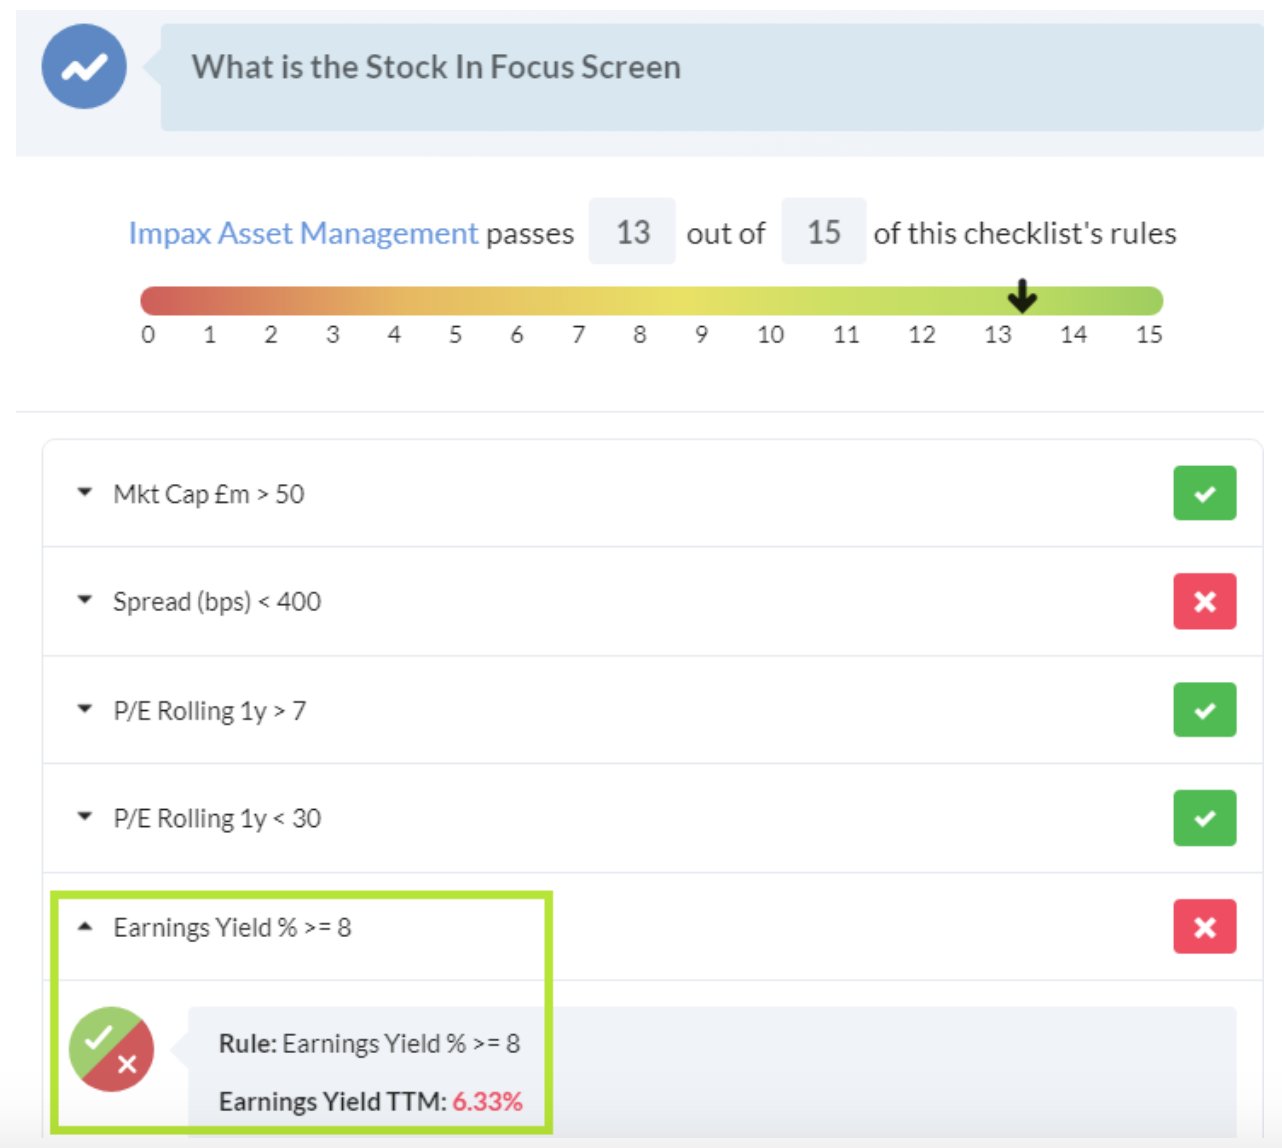
Spread: I avoid buying stocks with bid-offer spreads of more than 4% for the SIF fund. I don’t think such stocks are suitable for this fairly short-term trading strategy. But dealing spreads can be quite volatile. I suspect that with a little care and persistence, it would be possible to buy IPX within my 4% spread limit.
Earnings yield (EBIT/EV): My normal minimum for this excellent valuation metric is 8%. But in the relaxed version of my SIF screen, which I use during dry spells, I reduce this to 6%. So once again, I don’t think this failure is necessarily an obstacle to including Impax in the SIF folio at some point.
Given this, let’s take a quick look at some of the qualitative factors which I think could make Impax an attractive investment.
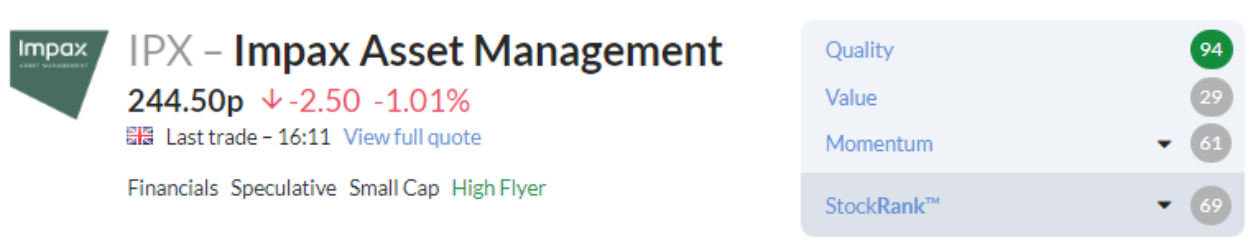
StockRanks: Stockopedia’s algorithms have a mixed view of this stock, with a high quality score but more cautious ratings on value and momentum:
Value: As I suspected, Impact shares look quite fully priced:
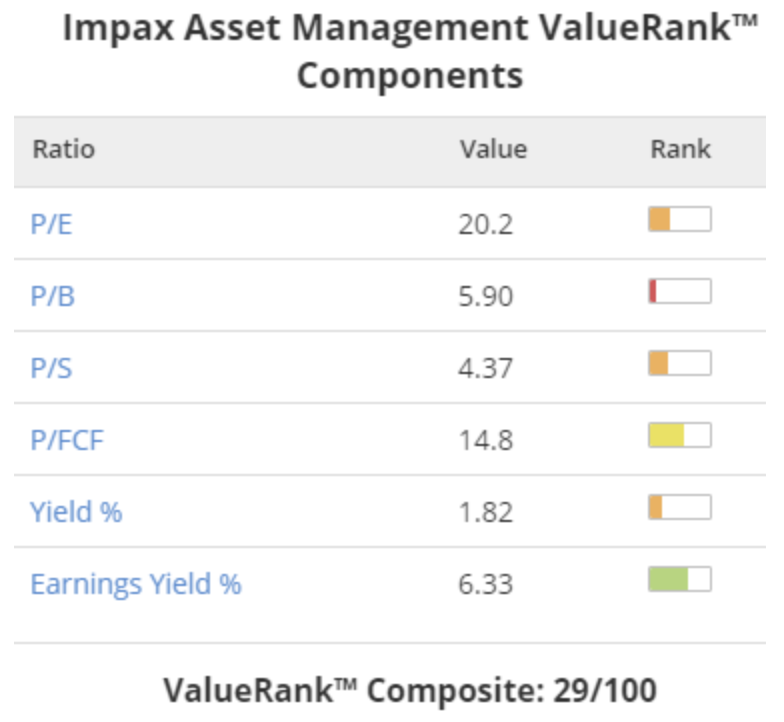
However, it’s not all bad. A price/free cash flow multiple of 14.8 suggests the firm is generating good levels of cash flow. The earnings yield of 6.3% is also reasonably attractive.
I’d want to look at these numbers more closely, but at first glance Impax appears to enjoy an attractive level of profitability and good cash generation.
Quality: A QualityRank score of 94 suggests this is a quality business, rather than a cheap one. Sure enough, the numbers are impressive:
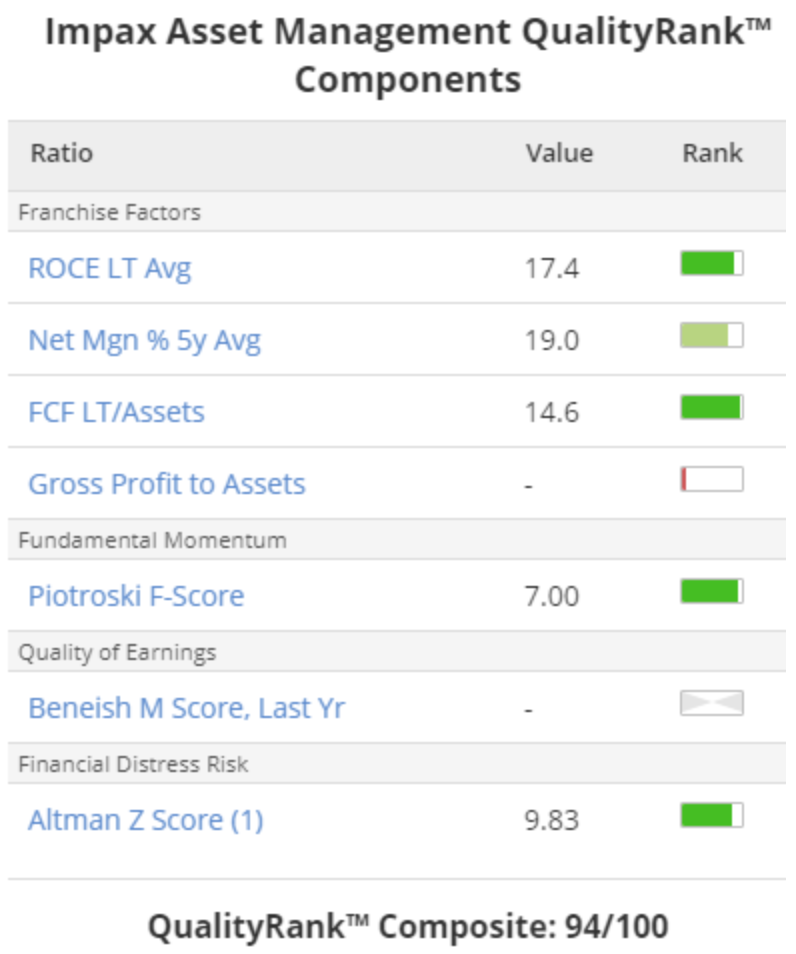
These figures look very promising. A quick check of the year-by-year figures suggests that these 5-year average figures represent a stable, improving trend:
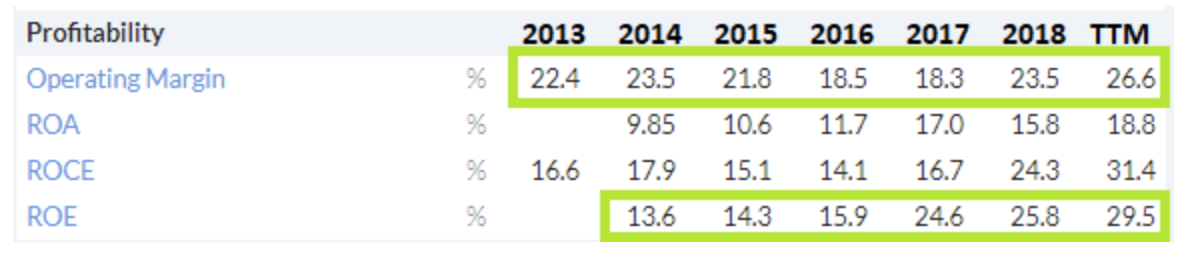
I suspect the strong free cash flow we saw above relates to Impax’s strong pricing power. In its latest results, the company reported a revenue margin of 0.55% of AUM.
To put this in context, struggling FTSE 100 asset manager Standard Life Aberdeen recently reported a revenue margin of 0.28% of AUM.
If it’s sustainable, I think that Impax’s superior profitability could make it an attractive investment and help justify a premium valuation.
Momentum: Stocko’s ever-useful consensus trend chart also shows that analysts’ forecasts have been slipping recently:
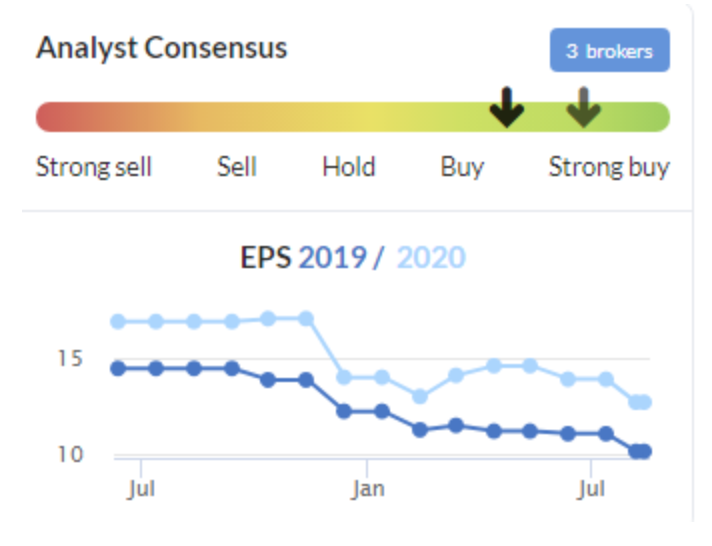
I’ve already noted that the share price has been falling. However, a look at the stock chart suggests that this could just have been a case of the stock becoming overbought and needing a period of consolidation:
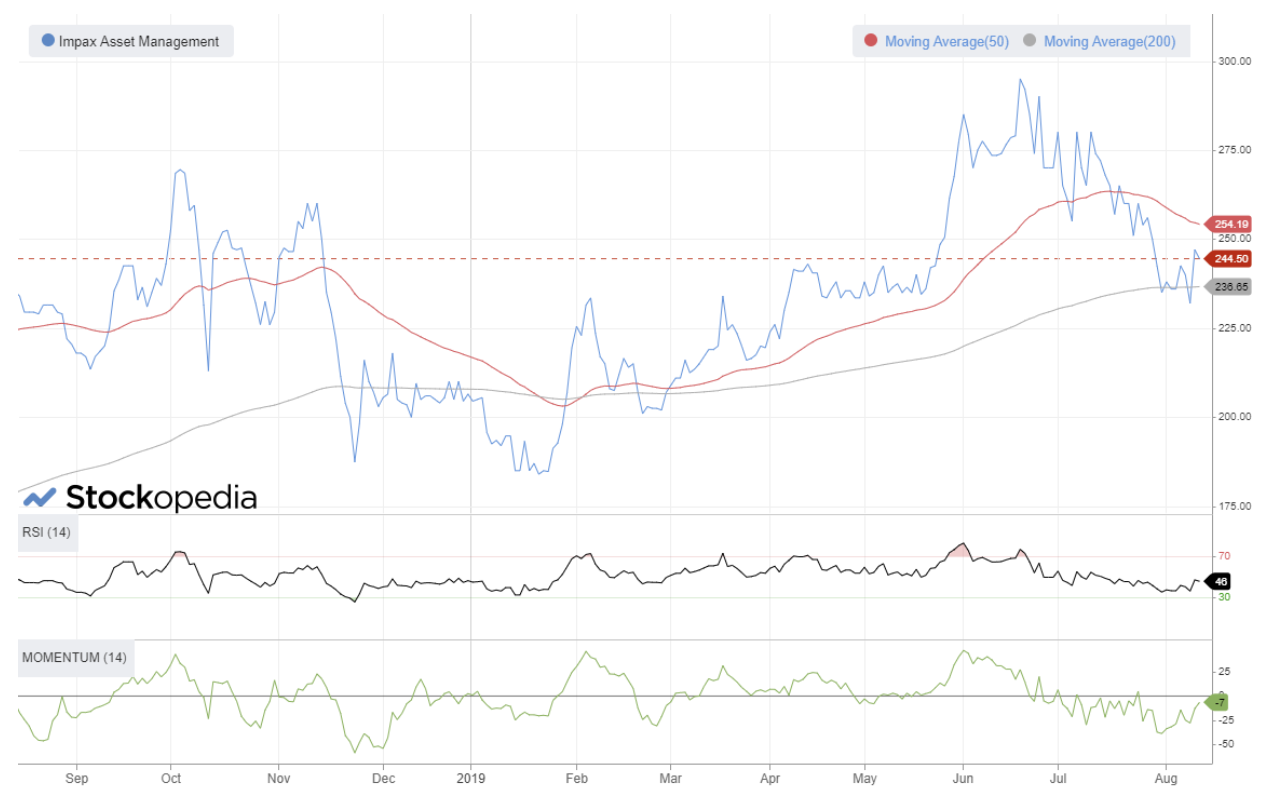
This view is (arguably) reflected in the stock’s MomentumRank, which has fallen but remains fairly positive:
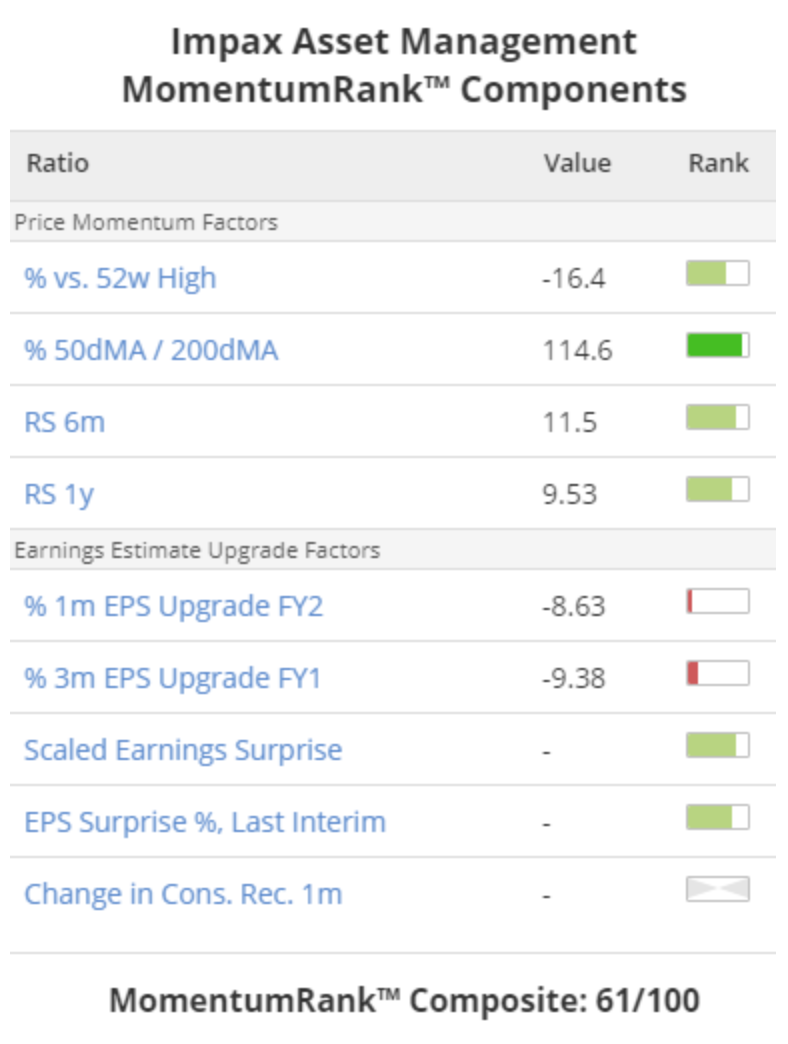
Price momentum appears to remain fairly strong. Further earnings downgrades could threaten this, but as things stand, the picture doesn’t seem too bad to me.
My verdict: In valuation terms, Impax continues to be priced for growth. The stock has a rolling forecast P/E of 20 and offers a 1.9% dividend yield. That’s not exactly value territory.
To deliver further gains from this level, I believe the company will need to maintain its pricing power and deliver further growth. This is by no means impossible, but with macroeconomic indicators looking increasingly mixed, the firm’s recent growth rate may be harder to sustain.
I’m not going to add Impax Asset Management to the SIF folio this week, but I’m cautiously impressed. I believe there could be an opportunity here.
Are ESG issues part of your investing process and do you have an interest in Impax? I’d be very interested to know what you think.
Disclosure: Roland owns shares of GlaxoSmithKline, Royal Dutch Shell, Standard Chartered and Tesco.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Hi - why would you invest in an asset management firm and not an ETF from blackrock or similar that keep the costs much lower(to be honest, i haven't done the math yet), more transparent in showing their holdings to you(from an ESG perspective you can reconcile easier)? I'm just getting started on this part of our strategy, so this article has been quite helpful! thanks!
SMinvest - thanks for your comment. I was considering Impax Asset Management (LON:IPX) as a possible ESG investment because I mostly buy stocks, not funds. I was attracted by Impax's specialist focus on impact investing, which I hope would provide exposure to a differentiated set of assets to a general stock market fund.
I've not so far been tempted by ESG ETFs because my brief research into ESG indices such as those run by MCSI and FTSE suggests that they aren't particularly differentiated investments (see the examples in my article).
One point I should make is that investing in Impax stock is not equivalent to buying an ESG ETF.
In general terms, investing in an asset manager can be seen as similar to a *leveraged* investment in stocks. This is because fee income is normally linked to the value of assets under management (AUM).
When markets are rising, clients invest more cash and asset values rise. So AUM rises very quickly.
When markets are falling, the opposite tends to happen. Asset values fall and clients withdraw cash. AUM can fall fast, cutting fee income sharply.
In truth, I haven't yet decided how I will approach ESG in my own investing. I think that Impax could be an attractive stock, although I'm not sure that the shares are particularly cheap at the moment.
As always, please DYOR.
Cheers,
Roland
An interesting summary which I agree with. I purchased all of mine in 2016 at the 40s and 50s and top-sliced a couple of times to make it a nil cost share. It's no longer cheap, but once we get through any possible bear market it should be able to grow AUM much further. I see no reason why it can't notch-up £30bn AUM in the next 5-10 years. I will continue to hold as Ian Simms is an intelligent iconoclast - he probably has 5-10 years before retirement so will want to keep his baby moving to some sort of crystallisation event no doubt.
They are a good follow on Twitter Roland - company specific and ESG sector generally
Although Impax Asset Management (LON:IPX) may be a good long term, I am very cautious about investing in fund managers at the moment with the current volatility and Brexit likely to be an even bigger factor in the coming months.
As ever, some excellent analysis Roland. I have owned Impax Asset Management (LON:IPX) for a couple of years now (maybe three years even) and have taken some profits along the way. I have passed them over for recent portfolio top ups, partly because of value and partly because of the stage of cycle we are at. AuM is in part affected by market performance.
This said, since passing £10bn AuM the company have been winning some fairly significant mandates (due to scalability I presume) which I think will be an ongoing trend. In short, I would see a significant market sell off as an opportunity to load up on Impax Asset Management (LON:IPX) but for now, I am retaining a modest holding with a watchful eye on a valuation opportunity.
Cheers
Simon
Hi Simon,
Thanks for your comment. I agree that the link between market performance and AUM is a risk with Impax Asset Management (LON:IPX). Given the rapid recent expansion, any impact from a market fall may be hard to predict -- and could be severe, given high asset values in many sectors.
For an asset manager with a good track record, I would tend to view a market dip as a buying opportunity, rather than a reason to sell. But it could be very uncomfortable for a while...
Another point that interests me about the rapid increase in AUM is whether Impax will be able to maintain a genuine differentiated focus on impact investing. One area I'd like to research in more detail is the nature of the firm's investments.
Good luck with your holding.
Cheers,
Roland
With all the "moral" investors selling out of the non-ESG stocks, the big sovereign funds and institutional investors, this must surely act to depress the share price of the non-virtuous stocks.
Does this mean there is a future opportunity for income plays from depressed sin stocks once the moral investors have all sold out?
Hi Andy,
I can see that some unloved non-ESG stocks do present possible buying opportunities. For example, the current valuations of big tobacco and big oil.
Conversely, some bears would argue that depressed valuations are deserved not so much for ethical reasons, but because these companies are potentially in a multi-decade run-off scenario.
These arguments have been knocking around for a while, as a shareholder in some such companies, my view is that the reality lies somewhere in the middle.
I do believe that there are some attractive income opportunities in big cap stocks at the moment and have been buying accordingly.
DYOR, of course!
Regards,
Roland