Stock in Focus: Is it time for last orders at JD Wetherspoon?

Opinions vary on the appeal of JD Wetherspoon’s affordable pubs, but the firm’s stock has been a profitable investment. The shares are worth 77% more than they were ten years ago. The dividend has risen by 155% over the same period.
Wetherspoon generates lots of cash flow, and this has been funnelled into rapid growth. The group now has 956 locations around the UK. Sales are 56% higher than they were in 2010.
Yet there are some clouds on the horizon.
Wetherspoon’s operating margin has fallen from a high of 9% in 2011 to just 6.2% in 2015. Interest payments on the group’s net debt of £ 626.1m now account for almost 30% of operating profit. The net debt itself is equivalent to 13 times trailing net profits. As founder and chairman Tim Martin never fails to mention, tax rates are quite high, too.
I’ve been concerned for some times that rising debt and falling margins will combine to bring Wetherspoon’s golden era to an end. The firm’s recent interim results did nothing to persuade me I was wrong. Despite a 6.2% rise in revenue compared to the same period last year, operating profit fell by 10.8%. Underlying earnings per share fell by 16.6% to 19.1p.
On that basis, a significant improvement in second-half trading will be required to meet full-year consensus forecasts for earnings of 45p per share.
A storm in a pint pot?
Am I exaggerating? After all, Wetherspoon’s cash generation remains strong. Free cash flow per share, by the firm’s measure and that of Stockopedia, consistently exceeds earnings per share.
The group’s £626m net debt is only around half its net fixed assets of £1.2bn, many of which are freehold and long leasehold properties. That seems reasonable. If margins remain under pressure or debt costs become problematic, couldn’t Wetherspoon just cut back on new pub openings and use the cash to reduce debt?
Perhaps. But I suspect such a plan would trigger a big drop in Wetherspoon’s share price. After all, it would be a clear signal that the business was going ex-growth. Wetherspoon’s sub-2% dividend yield would no longer be sufficient inducement to hold the stock. Greene King, for example, offers a forecast yield of nearly 4%.
Value? Not really
What do Stockopedia’s algorithms make of Wetherspoon’s current valuation? The shares currently have an uninspiring StockRank of 44 and do not qualify for any of the Guru Screens.
Wetherspoon’s ValueRank of 56 is slightly more impressive. The stock has a price/free cash flow ratio of 6.4, which is firmly into value territory. The group’s price/sales ratio and earnings yield (EBIT/EV) are also acceptable:
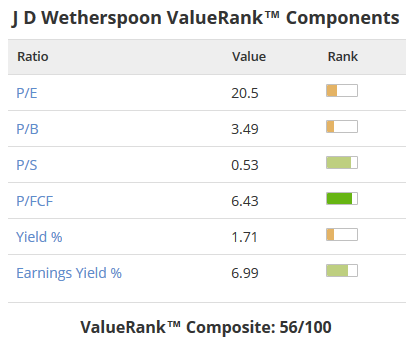
It’s worth asking why there is such a big difference between the P/FCF and P/E ratios. One of the main reasons appears to be that Wetherspoon’s annual depreciation costs are quite high. Depreciation is subtracted from profit but is added back in when calculating cash flow, as it’s a non-cash expense.
For the first half of the current year, Wetherspoon reported depreciation of £32.1m. That’s slightly more than the group’s net profit of £30.8m.
What this seems to imply is that while Wetherspoon generates a lot of free cash flow, it has to spend a lot on maintaining and updating its pubs. Thus this free cash flow is not really as free as it might seem.
I believe that Wetherspoon’s trailing P/E of 20 and P/B of 3.5 provide a more realistic view of the firm’s valuation. If earnings growth cannot be maintained, these ratios could soon seem dangerously high, in my view.
Improving quality
Wetherspoon’s recent results did have some positive effects on the stock’s ranking. The firm’s QualityRank has risen by eight points to 47 over the last month.
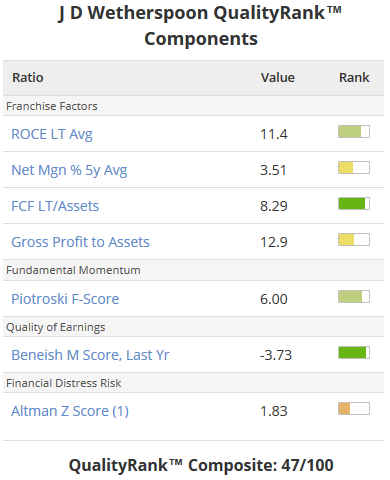
Once again, free cash flow is one of the main highlights. In addition to the high depreciation charge I mentioned above, I think that a second factor which boosts cash flow is Wetherspoon’s negative working capital.
Almost all sales are in cash and stock is turned over quite quickly. I suspect that the vast majority of food and drink is sold before Wetherspoon has to pay its suppliers.
This is evident from the latest balance sheet. Receivables are just £31m, while trade and other payables are £ 279.8m. Working capital (current assets minus current liabilities) was -£215m at the end of the first half. In other words, Wetherspoon was operating with the benefit of £215m of interest-free credit from its suppliers!
A second point worth highlighting is the 5-year average net margin. At 3.5%, this is uninspiring but acceptable. However, calculated on a year-by-year basis, net margin has fallen steadily from 4.1% in 2010, to 3.0% in 2015. This is not so appealing.
The final quality-related issue to consider is whether the group’s scale gives it a competitive advantage. I suspect it does. Wetherspoon has become (in my opinion) rather like McDonald’s, in the sense that you always know what you’ll get.
Many customers value this combination of low prices and predictability and seek out Wetherspoons when visiting new places. It remains to be seen how tolerant the group’s loyal customers will be if it’s forced to raise prices.
Momentum is poor
I’m not a chartist, but I have learned the hard way that it is rarely a good idea to invest against a well-established price trend.
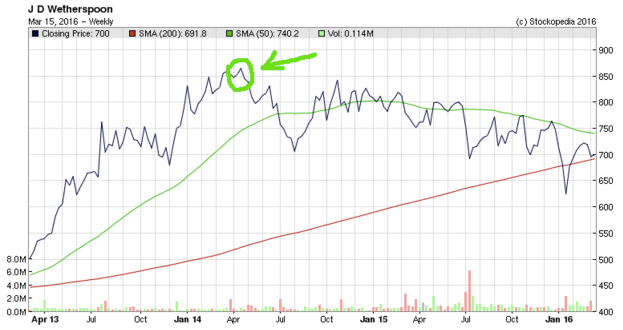
In my view, Wetherspoon’s chart shows a clear downward trend that’s been in place since April 2014:
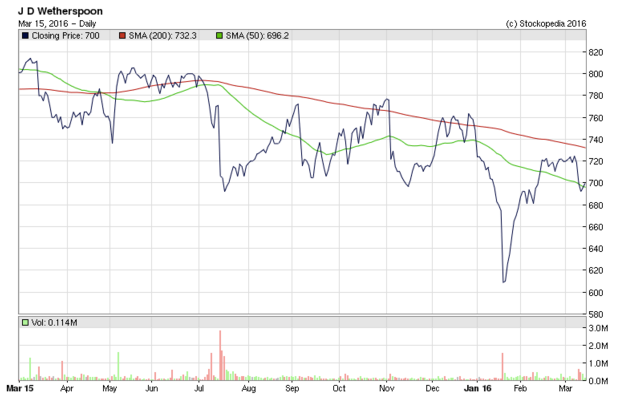
On a one-year view, the moving averages also suggest to me that a downward trend has become established. The 50-day moving average (green) is firmly below the 200-day moving average (red), which appears to be acting as resistance:
Earnings forecasts tend to support this negative view. Broker forecasts for 2015/16 have fallen from 54p per share to 45p per share over the last year. That’s a 17% decline. My view is that the eventual outcome could be lower still.
What’s next for Wetherspoon?
In its recent interim results, Wetherspoon warned that another round of wage increases would be necessary in April to implement the national living wage. Founder and chairman Tim Martin said the group was “aiming for a reasonable outcome” for the current year but warned that the market remained highly competitive.
In my view, the risks are heavily weighted towards the downside for Wetherspoon. I also believe there is better value elsewhere in the sector. I may occasionally call into a Wetherspoon for a cheap coffee or a pint, but I won’t be buying the shares for the foreseeable future.
Of course, your view may vary. Tim Martin has built a formidable business and may already have a plan for the next stage of its evolution.
As always, these are only my opinions and certainly not advice. Please DYOR and let me know what you think in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Thanks for a good article. I think Wetherspoons is a good example of a business where attempting continued growth is the wrong strategy but one the business is forced to follow for fear that its share price might fall. The business should develop an ex-growth strategy and concentrate of becoming a cash machine to provide income to its shareholders. If only investors would realise that going ex-growth can be an appropriate strategy if the situation demands it. Concentrating on cash generation and forgetting about new pub openings seems a sensible strategy for Wetherspoons. If the share price does collapse and I were a venture capitalist I might be tempted to run my rule over this company with a view to taking it private and implementing the cash generation strategy.