Stock in Focus: Is Shoe Zone a good fit?

Disclosure: Roland owns shares in Shoe Zone.
When investing in retailers, it’s important not to confuse product quality with investment quality. Take Shoe Zone, which floated on AIM in 2014. Although the firm’s business model is of the ‘pile them high, sell them cheap’ variety, Shoe Zone’s stock scores far more highly on the quality front.
As it happens, Shoe Zone is one of the most recent additions to my personal portfolio. I purchased the stock after the June interims revealed no new problems and quite decent results.
Nothing much has happened to the share price since then, despite the recent market volatility. This makes sense to me. Although Shoe Zone’s products are made in China, its customers are all in the UK, where the economy appears relatively stable.
Like Poundland, Aldi and other cheap retailers, Shoe Zone appears to have found a successful formula for high street growth. In this article I’ll ask whether this seems likely to translate into shareholder returns.
What about investment appeal?
Shoe Zone’s frugal appeal certainly stretches beyond its footwear.
Stockopedia gives the firm a StockRank of 87, with value and quality ranks in the mid-80s. This gives the firm a QV Rank of 95. As a value and income investor, I often use the QV Rank as an initial filter to highlight companies in which I might be interested, as they tend to fit my investing criteria.
Interestingly, Shoe Zone’s profit warning earlier this year has left the shares trading at almost exactly their IPO price. Thus investors can buy Shoe Zone shares at the initial offering price, but with the benefit of more information.
Good value
Shoe Zone’s ValueRank of 84 reflects an undemanding valuation, an attractive dividend yield and a respectable level of profitability:
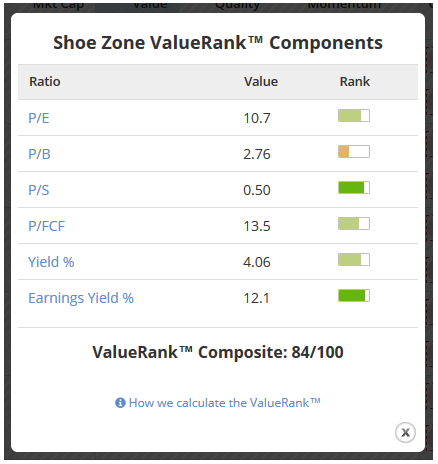
In my view, the dividend yield, earnings yield and P/FCF are the key figures here. Shoe Zone’s modest P/E ratio and attractive dividend yield is backed up by solid free cash flow generation.
The earnings yield is one of my favourite ratios. It’s calculated as EBIT/EV, or operating profit divided by enterprise value. In my view, this is an excellent way of assessing a company’s underlying profitability, as it excludes interest and tax costs but includes the impact of debt on a firm’s valuation.
I tend to look for an earnings yield of more than 10%, so Shoe Zone fits the bill, especially as it has no debt and thus should have negligible finance costs.
One caveat is that in my opinion, Shoe Zone’s intrinsic asset value is minimal. The firm has a head office and warehouse, some trucks and around £28m of inventory. The stores are normally rented and production is outsourced.
Investing here is about profiting from the execution of an apparently profitable business model.
Low-cost quality
According to its website, Shoe Zone sells more than 20m shoes per year. In 2013, the average retail price was just £9.77.
Yet being cheap isn’t enough for either shoes or shares. Some quality is necessary. Shoe Zone’s QualityRank of 85 suggests that in financial terms at least, this isn’t an issue.
However, investors might wonder why the firm’s successful model hasn’t been copied by others, as it has with Poundland, for example. In my view, the answer to this is that the firm’s management is above average.
Shoe Zone is essentially a family firm. Chief executive Anthony Smith and his brother Charles, who is COO, control 55% of the stock. These large shareholdings should mean that the firm is run with a relentless focus on cost, cash generation and sustainable dividend growth.
After all, based on this year’s forecast payout of 9.45p, Anthony Smith’s 30.56% shareholding will generate a dividend income of £1.4m, dwarfing his £225,000 salary.
Shoe Zone’s performance in 2014 certainly suggests that costs are kept under tight control. The firm’s gross margin rose from 59.4% to 61.3% last year, thanks to “improvements in sourcing”. This is an impressive gross margin for a retailer, although last year’s improvements may have been helped by the strong pound and falling commodity prices.
In any case, the firm’s 61% gross margin dropped through to an operating margin of 6.1% in 2013/14, giving a healthy net margin of 4.6%.
This profitability is backed by a strong balance sheet and net cash, earning the firm a Piotroski F-Score of 7. I have no real concerns here, other than whether last year’s exceptionally good performance can be sustained.
Uncertain momentum
Shoe Zone’s trading appears to be heavily weighted towards the second half, which includes the spring/summer period (Shoe Zone’s financial year ends in October).
As a result, the firm’s first-half accounts, while broadly positive, didn’t really provide much of a clue about full-year prospects. Forecasts from the firm’s two brokers indicate that earnings per share are expected to rise by 12% to 18.1p this year, giving a forecast P/E of just 9.3. A dividend payout of 9.45p per share is forecast, giving a chunky 5.5% prospective yield.
Shoe Zone’s MomentumRank of 45 doesn’t really reflect this optimism. Although earnings momentum is reasonable, price momentum is poor.
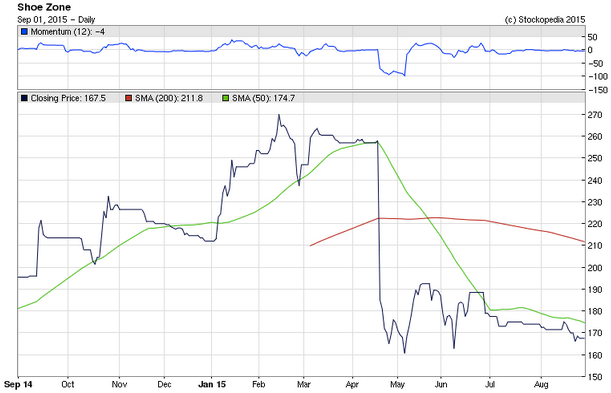
With a chart like this, price momentum is very weak.
The impact of the firm’s April profit warning is still very much reflected in the price momentum factors. As we saw with Boohoo.Com recently, this creates a dilemma for investors. While the valuation may be attractive, the price momentum situation is not.
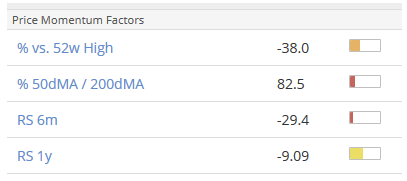
For me, this isn’t a big concern. I prefer to buy cheap and wait for something good to happen and see technical momentum factors such like the price relative to the 52-week high and the ratio of 50-day moving average (dMA) to 200dMA as secondary to fundamentals.
However, this is a case of DYOR. What’s comfortable and consistent for one investor may not work for another.
Outlook
In my opinion, Shoe Zone’s performance during the second half of this year is key. The way I see it, management credibility and investment appeal are both in need of a dose of boring consistency at the moment.
If Shoe Zone delivers, I’ll be happy to hold and enjoy the yield while sales inch higher. If not, I may sell. But that’s only my view. I’d welcome yours in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
10 comments
SHOE prices from China are fixed in US$. However, there is scope to renegotiate at certain times, so the RMB depreciation should bring cost deflation, just not immediately.
The company are cutting back on total outlets, and will continue doing so. They feel that with their quality criteria on returns from new shops that (organically) they're currently near saturation levels in the UK. They've a programme of closing Grade 3 stores (300 lines) and opening Grade 1 stores (400 lines).
Renegotiation of lease terms is yielding dramatic benefits in terms of cost reductions, but they're aware this in not a long term solution. They're open to growth, and will probably resume that path soon, I feel inorganically. After the burns they suffered from the Stead & Simpson acquisition, they're understandably cautious about the right sort of growth.
Hi Roland, VegPatch et al,
Thanks to all for their interesting comments.
Perhaps another point to consider is that since March the remimbi/£ exchange rate has changed by approx 6.5%. This should help SHOE presumably and it should drop straight through to the bottom line.
Regards,
Richard.
My first port of call in thinking about Shoe Zone was Peter Lynch's advice to invest in companies that you see around you every day. From the outset it appears that Shore Zone (SHOE) has what people desire: a product at a low price point. Average prices are under £10 for a pair of shoes! But when I interrogated the numbers In the P&L felt less comfortable with this assumption. Sales have been going backwards for a number of years. management has just had to close 9 loss making stores and is moving a number of others, whilst opening larger stores.
SHOE operates from 541 stores nationally. It has realised that a number of its 140ish smaller, Grade 3 stores, which stock c300 shoe styles, are not cutting the mustard and it is having to close some. It however is focusing on opening more, larger Grade 1 stores that stock 450 shoe styles. The problem is that Group sales are going backwards, -6% in H1, and although gross margins rose , it doesn't offset the decline in sales. It has also pushed some sales online with Amazon and eBay, but this doesn't offset the decline. Sales have fallen from £239m in 2010 to £173m in FY14, and it is very likely 2015 will be below 2014.
In the H1 results SHOE said that average rents have been renegotiated DOWN 28%. That helps the profitability of struggling stores but I think it tells me more about where SHOEs stores are located. I seriously doubt that Shoe Zone stores are destination stores that attract shppoer from miles around. The fact that rent reviews were down so much probably means the portfolio is located on desolate, sub optimal high street locations which have been negatively impacted by online sales and the financial crisis. Have consumer habits in these areas changed for good? Unfortunately quite possibly. I would want to ask management if it built Shoe Zone from fresh today, how would it look? How many of its stores are non profitable, how many are only just profitable? How has the profitability of its current marginal stores changed in the last 3 years? I am concerned that while it is closing 9 loss making stores (just 2% of the total store base) it will be doing the same next year and the year after.
Multichannel sales grew 30% in h1, but no figure is given as to the importance of multichannel sales. No LFL sales for the store were given either. This doesn't strike me as a management team willing to 'fess up to its issues.
So I feel this company will struggle in future as it continues to battle against sales moving online and its diseconomies of scale from its 143 smaller stores which are likely to be losing sales. Also I am concerned that its store portfolio is poorly located.
I may be completely wrong in my admittedly cursory analysis, but This one is not for me despite the relatively low valuation.
Happy investing
VegPatch
Hi VegPatch,
Thanks for such an extensive comment, you make some good points. In my article I say that the firm's H2 performance is critical to the investment case and this sort of marries up with what you say -- the company really does need to prove it can deliver with boring reliability. I won't hesitate to sell if I get the feeling that this isn't going to happen.
I don't have such a downbeat view on the rent reductions and store portfolio as you, though. I don't think Shoe Zone is aiming to be a destination store -- it simply wants to mop up all the (considerable) demand for cheap shoes in areas where the stores are located. Rather like Poundland, pricing power is limited to so cost cutting is essential. If Shoe Zone can use its relative clout to force rents down, then that's all to the good, in my view.
Similarly, closing underperforming stores quickly makes sense to me. The big supermarkets should probably have been doing a bit more of this...
As regards earlier years' performance, at first glance SHOE's sales, profits and margins appear to have been all over the shop in previous years. You only mention the apparent decline in sales but there are other questions: could sales really have fallen 35% in 2011, but then shot up by 41% in 2012? I'm not convinced.
Without further research I can't be sure that I'm right, but my interpretation of these figures is that because they are pro forma figures produced for the IPO, they present a rather distorted picture. I suspect much of this may be explained by a combination of corporate restructuring, refinancing and calendar changes. (I should add that this is guesswork -- I don't know the detail of Shoe Zone's history before it was listed.)
Thanks again for your comments, opposing views are alway invaluable when trying to justify an investment!
Cheers,
Roland
Roland,
Perhaps another point to take into account is that Shoe Zone ( with shops in reportedly run-down locations) may now be being undercut by High Street stores, notably Primark. The Primark (pronounced "Preemark") store in a shopping mall near to where I have a flat in Spain sells women's shoes good enough for daily use (and I am picky!) at very cheap prices. In their sale, a few weeks ago, I picked up three pairs for a grand total of 16 euros! I have no idea whether Primark in UK sell shoes. If they do, that could present quite a challenge to Shoe Zone.
Best wishes,
Jane.
That is probably true but Primark in UK is only in the large towns/cities, ShoeZone have more outlets and are in smaller towns. In my area there are no Primarks within 30 miles. In fact there is only 1 in Suffolk and 1 in Norfolk. Whilst ShoeZone have 2 stores in Ipswich and are in most medium size towns, in Suffolk they have about 12 shops in Suffolk. So a slightly different set up.
Herbie, good point, although I've just looked up their websites and Primark do seem to have the appreciable number of 198 shops across UK and Eire against the 553 units Shoe Zone has in those two countries. The point of Primark perhaps starting to eat Shoe Zone's lunch may still be valid if they start mopping up the business for cheap shoes with bright, modern stores in those larger population centres and in shopping centres where there is likely to be captive footfall, effectively pushing Shoe Zone out to the edges of the market. Primark are very market-savvy and Shoe Zone may well have quite a fight on their hands.
Thanks for that info. I did not realise Primark had so many stores now. I think ShoeZone are already in those sort of locations. In my local town there is the only shoe shop I think, there is a Sports Direct if you want trainers/walking/sandals type footwear. I can't see Primark opening a store there but there is a small M&S so you never know.
Hi
I like the proposition, seems like a John Lee sort of share.
SCS is similar.
Hi Timmytrump,
Thanks for your comment. I see your point about SCS (LON:SCS), although in my view Shoe Zone (LON:SHOE) has the edge, thanks to its superior profitability (operating margin of 6% vs 2.5% for SCS) and a more affordable dividend.
As Paul Scott pointed out recently though, current market conditions could be good for SCS for a while longer.
http://www.stockopedia.com/content/small-cap-value-report-12-aug-2015-utw-hrn-cap-trb-trcs-scs-104485/
Cheers, Roland