Stock in Focus: Lamprell

The oil price crash has created some interesting investment opportunities, but timing new buys has not been easy.
With the benefit of hindsight, the oil market crash seems to have bottomed out in January when Brent dropped to just $45 per barrel. It’s now about $62.
Investors in oil futures might have missed the big rally, but I don’t believe the same is true for equity investors.
I’m convinced that there will be some big winners (and losers) over the next 12-18 months, as we see who can really make money at lower oil prices.
 One company I personally think could do well in this environment is rig builder Lamprell. This Dubai-based firm specialises in building jackup drilling rigs, which are used in shallow water.
A turnaround play
Lamprell has had some problems over the last couple of years, culminating in a $120m rights issue one year ago. However, this influx of fresh cash enabled the firm to clear the majority of its debts and invest in upgraded facilities.
Lamprell ended 2014 with a order book of $1.2bn. This is lower than at the time of the firm’s profit warning in May 2012 ($1.6bn), but substantially higher than at the end of 2013 ($0.9bn).
This suggests to me that Lamprell’s turnaround could be gaining momentum. The Stockopedia StockRanks certainly support this view.
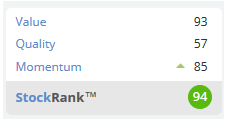
Lamprell boasts a StockRank of 94, with a ValueRank of 92 and a MomentumRank of 86.
This combination of value and momentum - the two most powerful factors that drive stock returns - is a classic recipe for outperformance, as Ben Hobson discussed last week in this article. Lamprell was also one of Stockopedia founder Ed Croft’s top picks for 2015.
Value: Is Lamprell still cheap?
At this point, investors may point to the 31% gain made by Lamprell shares this year and ask whether it’s still cheap enough to buy.
After all, Lamprell stock now trades on a forecast P/E of 14.7, according to Stockopedia. That’s higher than the sector average of 12.
Although true, this doesn’t necessarily mean that Lamprell is not good value. Traditional value metrics tend to use historical data, rather than forecasts.
Lamprell trades on just 8.5 times last year’s earnings and a price-to-sales ratio of 0.8. Earnings per share and revenue have risen by an average of 20% per year since 2009.
The firm’s price-to-book ratio of 1.3 is reassuring, especially as net cash of $272m accounted for about 52p per share at the end of 2014.
It’s not a clear-cut picture though. Lamprell has not yet restarted dividend payments, which were suspended in 2011. A payout is expected for 2015, offering a prospective yield of 1.1%.
Another concern is that operating cash flow was negative last year. This was due to project timing and the impact of restructuring, but investors will want to see positive operating cash flow in 2015.
Interestingly, Lamprell has qualified for two of Stockopedia’s value screens, the Charles Kirkpatrick Value Screen and the John Templeton Bargain Screen, in the last two months.
Both screens combine traditional value metrics with growth and momentum indicators, to highlight reasonably-priced stocks with the potential to outperform.
Both screens have outperformed the FTSE 100 by at least 10% over the last two years.
Is Quality a weakness?
Lamprell’s QualityRank of 57 suggests that this could be the firm’s weakest area.
Although Lamprell reported an impressive 10% operating margin in 2014, last year’s profit margins were described by the firm as “exceptionally high” and are expected to fall this year. Management says that this is due to a combination of project timing and market conditions.
This decline may be offset to some extent by the cost savings from Project Evolution, Lamprell’s restructuring plan. The full benefits aren’t expected until 2016, however, so 2015 could be a slightly lean year for the firm.
Looking at the breakdown of Lamprell’s QualityRank (which you can access by clicking on a company’s rank number in the StockRanks portal), the biggest problem appears to be a low Beneish M-Score.
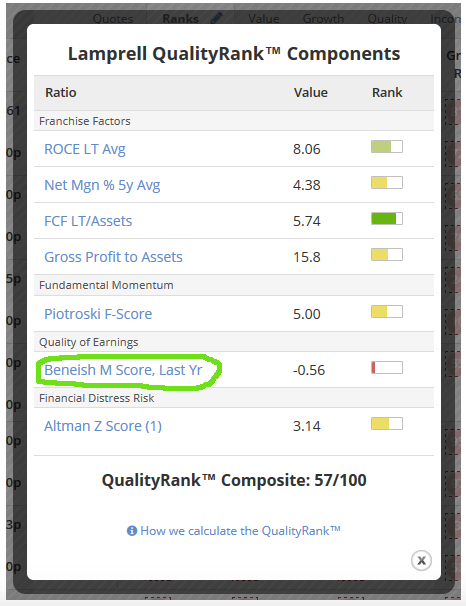
The M-Score uses eight accounting ratios to try and detect earnings manipulation. The two areas flagged up as a risk for Lamprell are the number of days’ sales in receivables and the ratio of accruals to assets.
Having taken a closer look at last year’s accounting notes, I’m inclined to think that these red flags are the result of last year’s increased work volume and the lumpy timing of Lamprell’s projects.
However, debtor days -- the average number of days taken for a firm’s invoices to be paid -- did rise from 30 to 37 days in 2014. I don’t see this as a big concern, but will watch for any further deterioration.
Ultimately, I think these metrics all represent the incomplete status of Lamprell’s turnaround.
The firm ended 2014 with a strong balance sheet and decent profits. It now needs to deliver positive cash flow and stabilised profit margins to prove its quality.
Rising momentum
The market certainly believes that the outlook for Lamprell is improving.
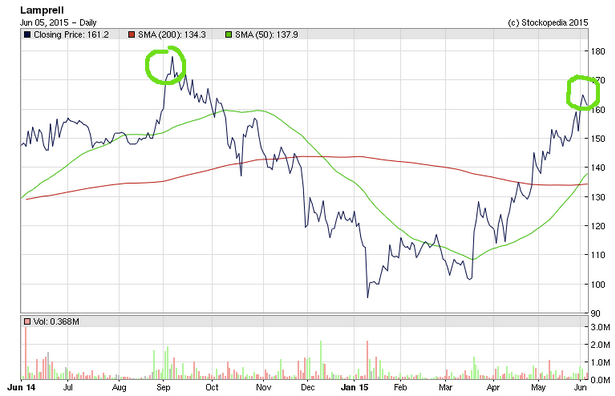
The rig-builder’s shares have risen by 31% so far this year. They are now close to the 52-week high of 178p seen on October 2014, before the oil price really started to slide.
Lamprell currently qualifies for the Josef Lakonishok Momentum Screen and the Earnings Surprise Screen. Both screens emphasise the importance of earnings surprises, when firms outperform analysts’ estimates.
Data suggest that analysts tend to react slowly to such events, allowing investors the chance to buy shares at prices which don’t reflect a company’s true potential. Lamprell’s earnings forecasts have been upgraded over the last month, potentially ending a downward trend.
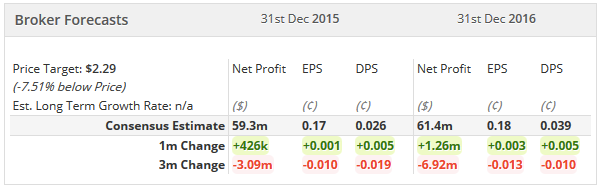
If consensus forecasts continue to rise, then the strong momentum seen recently could continue.
What are the risks?
One risk facing Lamprell is its dependency on a single large customer and a single type of drilling rig.
The firm’s largest customer is the Emirates National Drilling Company, for whom it is currently building nine jackup drilling rigs. Jackup rigs of this kind for NDC and other clients accounted for $1.1bn of the firm’s $1.2bn order book at the end of 2014.
Lamprell says it has a diversification plan in place. I’m supportive of this, but the firm has experienced cost overruns and delays with new projects in the past. Careful management will be needed.
The biggest risk facing the firm is probably the state of the oil market. No one yet knows how the big spending cuts announced by the oil majors will affect companies such as Lamprell.
The firm has said that it expects pressure on pricing and potential project delays, but that shallow water jackup drilling is likely to be “less affected”. We’ll learn more when the interim results are published later this summer.
Outlook
Operationally and financially Lamprell is more efficient than 12 months ago, and the shares seem reasonably priced on a 2-3 year view. I believe Lamprell has the potential to deliver a successful turnaround in spite of lower oil prices. As ever, these are my personal opinions, so DYOR and safe investing !
Disclosure: Roland owns shares in Lamprell.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
I am luke warm on the sector, preferring distribution (ex. Kinder Morgan Inc KMI )
So, I would be intransigent in any case.
Thanks for your article, anyhow.
purpleski,
Thanks for your comment. I'm slightly less bullish on oil than you, but I'm happy to hold too as I think that Lamprell's strong balance sheet and strong customer base in the Emirates could stand it in good stead. The fact that most of its rigs are for shallow water, hence lower cost drilling, also appeals to me.
DYOR, as always...
Cheers, Roland
Thanks for the interesting and informative analysis I have held since beginning of April and am up 20%. I bought on a number of factors not least stock ranks and that it was one of Ed Croft's naps and was looking for an oil price recovery investment. Based on nothing scientific whatsoever I suspect that the oil price will strengthen further than being predicted. This based on nothing more than a sense that historically the price tends to drop further than it should and rise further than it should but we will see.
At the moment I am happy to hold as when I buy I am looking 3+ years.