Stock in Focus: Should I add XLMedia to the portfolio?

With painful memories of Globo, Plus500 and Quindell fresh in the minds of many UK investors, I made sure that I had some wriggle room when I designed the Stock in Focus portfolio. I am allowed to reject qualifying stocks if I think that Stockopedia’s rankings don’t accurately reflect the risks involved.
This week’s stock is a possible example. XLMedia is a new qualifier for my screen, with a StockRank of 99. The firm’s fundamentals seem strong and both cash flow and generous dividends are real. Yet this is an AIM-listed Israeli tech stock that operates in the gaming sector. Recent history suggests it could be a risky buy.
I’m going to explore the arguments for and against adding XLMedia to the SIF portfolio. But first, it’s worth understanding exactly how XLMedia makes money.
How do you achieve 51% annual sales growth?
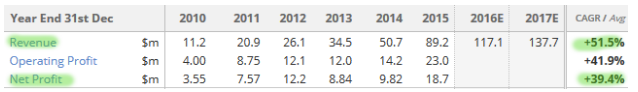
XLMedia’s revenue has grown at an average of 51.5% per year since 2010. Profits have risen by an average of 39.4% each year.
The company generates its revenue by supplying new users to online gaming sites. According to this video presentation, these include big names such as Ladbrokes, as well as smaller online casino operators.
XLMedia doesn’t get a flat fee to supply a certain number of users. Instead, the firm spends its own money generating leads for its customers. This is known as performance marketing. XLMedia attracts potential gaming site users through its own websites and with paid advertising such as Google AdWords and Facebook ads.
For each new player who signs up with a gaming operator and meets certain other criteria, XLMedia receives a share of the revenue from the player’s activity. In the online gaming sector it’s common for this performance payment to be a share of lifetime user revenue. This means that good quality users will generate revenue for XLMedia for many years after their initial signup. This can be very valuable: XLMedia said in 2014 that its average revenue-sharing rates were 35-55%.
Risks vs rewards
Performance marketing has become an important industry that’s grown up alongside ecommerce. Price comparison businesses such as Moneysupermarket.com are performance marketers, as are cashback and discount code websites.
It’s also a sector I understand well, as I’ve worked in performance marketing for a number of years. I’ve done similar things to XLMedia, but on a much smaller scale (and in a different sector). The big attraction is that this business can scale quite easily.
XLMedia claims to run more than 2,000 websites, most of which it says are informational. For example, XLMedia probably runs websites providing tips on poker strategy. From here, a proportion of users will click on tracked links to online casinos where they may sign up and become paying customers. If XLMedia’s websites rise up Google’s search results, they will generate more new users without requiring any additional investment.
Similarly, if conversion rates from XLMedia’s paid advertising are strong, the firm can increase its ad spend to drive more traffic, without having to generate new advertising concepts.
On the other hand, the downside can be brutal. I remember very well the sickening feeling I had towards the end of 2011, when changes to Google’s algorithms led to my main income-generating website losing the majority of its traffic for a period of time. Another risk is that revenue-sharing rates can be cut without notice.
XLMedia’s scale and diversity should provide some protection from this kind of risk, but only up to a point. The company doesn’t seem keen to provide examples of its websites, but my experience suggests that many will have certain recognisable characteristics. These could be targeted by Google in future algorithm updates.
This lack of visibility makes it’s hard to judge the quality and durability of XLMedia’s business. It may also be one reason why the firm’s recent strategic review failed to find a buyer.
Proven track record = value?
The key lesson I’ve taken away from my years in performance marketing is the need to constantly update and reinvent my business. XLMedia’s scale and profitable track record suggest it has been very successful at this.
As Paul Scott has pointed out more than once in his SCVR reports, although the firm’s profits are flattered by a constant emphasis on EBITDA, the cash flow and dividends are real.
XLMedia’s shares currently trade on a trailing P/E of 10.2 and a price to free cash flow ratio of 17.7. Last year’s 5 cent per share dividend was covered comfortably by free cash flow. With a trailing yield of 5.1%, XLMedia does have some appeal.
Are falling margins a quality concern?
One area which concerns me is XLMedia’s falling profit margins. Stockopedia shows that the group’s operating margins have fallen from 46.2% in 2012 to 25.7% last year.
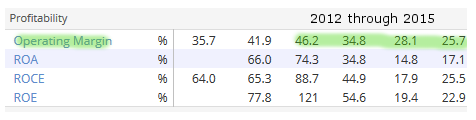
The firm has alluded to this fall in its commentary, saying that greater scale in more regulated markets will lead to higher volumes at lower margins. That’s okay, but if XLMedia’s user acquisition costs rise while the firm’s income remains the same, cash generation could weaken.
While XLMedia scores quite well on quality, the QualityRank uses 5-year average margins. These can make a company with falling profit margins appear more profitable than it really is.
Who owns XLMedia?
XLMedia’s significant shareholder list includes a number of well-known institutional investors. Noted small-cap specialist Hargreave Hale is present with a 3.9% shareholding, as are Slater Investments and Investec. Interestingly, all three have trimmed their stakes over the last year.
Chief executive Ory Weihs has a 5.16% interest, which I’d normally find reassuring. However, Mr Weihs’ interest actually forms part of a concert party including Webpals Enterprises Limited, which has a 42.4% shareholding in XLMedia.
In total, 56.4% of XLMedia’s shares are not in public hands. Private shareholders are unlikely to have any voting power. A restricted supply of shares also make it easier for the stock to be squeezed higher on low volumes.
Indeed, I think it’s worth asking why XLMedia was looking for a buyer so soon after its IPO in March 2014. Was the company floated simply to help the firm’s original backers find a way of cashing out at a higher price?
Is strong momentum a buy signal?
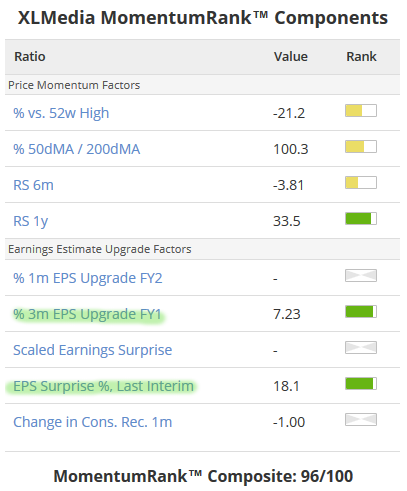
I’m going to close off this article by highlighting the recent surge higher in XLMedia’s MomentumRank. This has risen by 20 places to 96 over the last month.
The main reasons for this appears to be a recent broker upgrade and the earnings beat reported with the last results:
I’m not yet convinced that this is enough to make the stock a buy. XLMedia may continue to trade well and pay generous dividends. But the firm’s business model faces continual regulatory and technological risks. The collapse of Blinkx is a good example of how profitable internet marketing businesses can go from hero to zero with no warning.
I’m not going to add XLMedia to the SIF portfolio this week, but I’ll record an open verdict for now. I’d really welcome your views on this stock -- are you invested, would you invest and why?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
I held for quite a while but ended up selling because they basically seemed to be going nowhere.
For such decent numbers, growth etc shouldn't the share price be a bit more buoyant? Sure, maybe they pushed their IPO valuation a bit too much but it just felt like very little was going on (other than an occasional report with more impressive numbers).
Roland,
Good article - always nice to read something where the author has direct and relevant experience in the industry. It has definitely increased my understanding of this industry (which was previously nil!).
The wider group of internet based marketing / market making businesses is an area I'm looking at more widely at the moment (thinking of the likes of Moneysupermarket.Com (LON:MONY) , Zoopla Property (LON:ZPLA) , Rightmove (LON:RMV) , Just Eat (LON:JE.) , Auto Trader (LON:AUTO) here) as they do seem to have some fundamentally very attractive business characteristics - some of which you have set out above in relation to XLMedia (LON:XLM) .
The worry I'd have for XLMedia (LON:XLM) is how confident you can legitimately be that it will be able to sustain its profits, as you say, it all seems rather opaque if they won't disclose what the actual websites driving consumers to their customers are, and they are vulnerable to search rankings which is something over which they have little (direct) control. Whereas some of the businesses above can increasingly keep consumers away from Google and within their own environment (e.g. through their app).
However, the prospect of lifetime royalties over revenue generated by each user is certainly attractive! One to ponder - I'll have a read and think about whether this is something I'd be prepared to invest in.
(I do have one other concern though. Bluntly, applying a simple test I like to run over all my investments, I think it's questionable that XLMedia (LON:XLM) are performing a service that is of real value to society - I'm aware that sounds wishy washy, but tend to think that a company providing a product/service of undoubted value is more likely to be able to sustain its profits - whereas something like this seems a bit more like rent-seeking which will at some stage come under scrutiny or attack, whether from regulators, media, etc. Could be wrong though!)
LongbearRanger,
Thanks for your detailed comments. One thing I think is worth emphasising about the other internet businesses you list is that they all have successful brands. This is something that XLMedia (LON:XLM) appears to lack.
Internet search traffic is far more brand driven than it was ten years ago, so this is a very significant advantage in my view.
A second point is that although Moneysupermarket.Com (LON:MONY) and USwitch (now owned by £ZPLA) are essentially performance marketers, Rightmove (LON:RMV), £JE, Auto Trader (LON:AUTO) and Zoopla's property website are all standalone businesses, who 'own' their customers.
As with brands, I tend to believe that internet businesses that have a direct relationship with their customers are more intrinsically valuable than those which do not.
Although the scale and sophistication of XLMedia's operations does seem impressive (based on its financial results), I do agree with you that the nature of XLMedia's business leaves it open to both competition and hostile scrutiny.
Regards,
Roland
Roland,
Thanks for your reply. I agree very much with the point you make about brands and "ownership" of customers - these are key characteristics that, if present, very much increase the value of an internet business (or any business, quite frankly!).
For example, the reason Hargreaves Lansdown (LON:HL.) (which is really another internet business) can achieve operating margins of 50% despite really just being a distributor is, I think, that it's Hargreaves Lansdown (LON:HL.) that "owns" the customer relationship, as a rule, rather than the underlying providers of investment products.
I guess where I get to on XLMedia is that it could very well be an excellent investment - it seems to me that the low valuation is the premium an investor gets paid to assume the risk that the profits may evaporate (not dissimilar to how I viewed GVC Holdings (LON:GVC) last time I looked at it, though I haven't done so for a while). In some circumstances I'm happy to take that kind of risk, for example I own Lancashire Holdings (LON:LRE) which (although an insurer) is in some ways facing that same risk - but as a general rule I try to own businesses with sustainable profits and I don't think that XLMedia fits that, so I won't be buying, but as a part of a sufficiently diverse portfolio I can see that it might very well be a good investmett.
Roland,
As I already hold 3 of the shares you have added to the SIF portfolio, I am following this with some interest, particularly as I also hold XLMedia (LON:XLM). Your write-up is extremely interesting, particularly regarding the potential risks around this business. Your article confirms my view that the growth prospects look good, with solid dividends, but I will not be adding to my relatively small holding due to the risks associated with the business.
I look forward to further SIF articles given the early cross-overs with my own holdings!
James
James,
Thanks for your comments, I'm glad to hear you're finding the SIF articles useful. XLMedia (LON:XLM) does seem to be one of those stocks that could go either way.
Roland
Nice to see a well informed balanced view of this Company. I believe the strategic review was motivated by the desire of the founding VC's to cash out their remaining stock at a premium. However many private equity buyers have restrictions on involvement with gambling activity which will account for some of the lack of interest.
Thank you for the review.
A few small comments:
• Founder actually is buying (he is exercising options and not selling them), most of his shares are minority rights in the main partnership that owns 43%. I believe he is a long term buyer / holder.
• As you can see, results have been smack on multiple upgraded forecasts several times, not as volatile as you would imagine.
• This is not an Ad-tech business.
• Company has been delivering for years, also before the IPO.
• PBT numbers are strong and divis are growing, regardless of the use of EBITDA.
• Margins are actually stronger then forecasts for publishing (80% with a 72% forecasts) and media (34% on a 30% forecast), so are EBITDA margins. we can expect a general decrease in margins as a results of shift towards lower margin / higher volume products like games, apps and financials.
Hi tomstone80,
I broadly agree with all of your points, some of which I did mention in the article. You're right that this isn't really Ad Tech, it's more marketing.
On the financial front, XLMedia certainly has delivered so far. I didn't say that the founder is selling -- as you say, he's exercised some options recently -- http://www.investegate.co.uk/xlmedia-plc--xlm-/rns/director-share-dealing-and-exercise-of-options/201605181626346498Y/
My question was about the intent behind the company's decision to list on AIM and then almost immediately put itself up for sale. In my opinion, one interpretation of this is that XLMedia hoped to frank a higher value for its business by listing on AIM, thus facilitating a more profitable sale for the concert party which controls the company. But I could be wrong.
My other main point is that while XLMedia's financial performance has been very strong, a number of variables could change very quickly which might derail the firm's business model.
This might not happen and I may still decide to add XLMedia to the portfolio -- this could be a real success story. But I'm concerned about some of the risk factors.
Good luck with your position (if you're a holder).
Regards,
Roland
Thank you for the answer Roland, hope you join us at some point :)
Regards
Tom S
Thank-you,
It is useful that you have experience in the same field.
The founder's desire to sell is understandable.
He built up a business in an area you and he know is volatile. Like BLNX but unlike PLUS sudden changes can make or break the business model.
Private shareholders will not have time to vote! It might soar if he sells or crash if there is a technological glitch of the type you refer to. I do not want to be holding if the founder leaves but he appears smart and therefore merits some of my cash. My purchase is already showing a small profit.
The numbers appear genuine despite using them via EBITDA to flatter results. No fraud so worth a punt but I shall not be waiting around for my dividend!!!