Stock in Focus: Stanley Gibbons

Successfully transforming a business through a series of acquisitions is a difficult task, but this hasn't deterred Michael Hall, chief executive of stamp dealer Stanley Gibbons. His goal is to transform the group from a globally-recognised stamp dealer into a far broader fine art and collectibles business.
 In April, the firm's chairman, Martin Bralsford, told shareholders that "Following two years of substantial investment, our long anticipated online development plans are finally reaching fruition in May."
Unfortunately, this optimistic statement was issued alongside a profit warning. Full-year results for the year ending 31 March 2015 are expected to be "materially" below expectations, despite a strong first-half performance.
At the time, Stockopedia's small cap expert Paul Scott suggested that the shortfall would be likely to reduce earnings per share by at least 10%. In fact, the reality seems likely to be much worse. Let’s take a closer look.
Splashing the cash
Stanley Gibbons was founded by the 16-year son of a chemist in Plymouth. The firm rapidly grew into one of the world's leading dealers in rare stamp and by 1891 had a shop on The Strand, in London.
Things started to change in 2012. The company raised £6m in a placing to fund the development of an online trading platform and spent $1m on acquiring a US collectibles website called bidStart.com.
That was followed by the £45m acquisition of AIM-listed Noble Investments in 2013, which was funded by a £40m placing and more new shares. Noble's main attractions were noted rare coin dealer Baldwin's and fine art auctioneers Dreweatts and Bloomsbury, but the price wasn't exactly a bargain. The price tag of £45m was 16 times Noble's 2012 profits, and more than twice its net asset value of £19m.
In 2014, two more acquisitions followed. Specialist stamp dealer Murray Payne was acquired for £1m via yet another placing. Soon after, AIM-listed fine art dealer Mallett was acquired for £8.6m, paid for with new debt.
In total, Stanley Gibbons has spent about £55m to acquire a significant presence in the coin, autograph, fine art and auction markets. On top of this, the firm has spent £2.6m since 2013 developing a new website and online marketplace.
Given that Stanley Gibbons only reported sales of £51.8m in 2014, these are significant investments. But will they generate the kind of growth needed to justify shareholder's patience?
The numbers say no
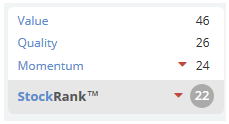
Stanley Gibbons has Stockopedia StockRank of just 22. The firm scores poorly on all counts, as you can see here.
The shares hit an all-time closing high of 378p in February 2014, but have been trending down ever since.
Interestingly, in September 2013 - just four months before the shares peaked in price - Stanley Gibbons qualified for the Beneish M-Score short-selling screen. This screen uses a set of eight accounting ratios to flag up likely cases of earnings manipulation. Heeding this warning could have generated a profit of well over 100% for investors who'd bought the shares in 2010.
Stanley Gibbons shares still qualify for the Beneish screen today, and have also since qualified for a second short-selling screen, the James Montier 'Unholy Trinity' screen. The Montier screen aims to detect overvalued firms with weak financials and poor capital allocation.
Quality
The influx of new staff and infrastructure resulting from Stanley Gibbons' acquisition binge caused sales, general and administrative (SG&A) expenses to double to £20m last year. This led to a fall in the firm's operating margin from 15% to 4.5%, despite a 45% rise in sales.
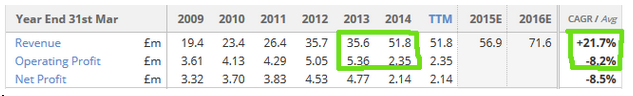
Return on capital employed (ROCE) was similarly affected, falling from 15% to just 2.6%. Stanley Gibbons now has a Piotroski F-Score of just 2, indicating a severe decline in the firm's financial strength.
I'm concerned that the firm's expansion may also have affected the strength of its defensive moat. No-one would seriously question Stanley Gibbons' position as a rare stamp dealer of global importance. However, the firm's moves into the fine art and auction markets have opened it up to significant new competition.
Cash consumption
Between January 2013 and September 2014, Stanley Gibbons' operating cash outflows were £12.2m. The firm's cash balance went from £6.8m to zero during this period.
The main reason for these operating outflows is a significant increase in the cost of inventories. In 2013/14, inventories increased by £10.3m. During the first half of the year just ended, inventories rose by a further £8.5m. This spending, plus acquisitions, lifted the value of inventories from £20.7m at the start of 2013 to £50.7m in September 2014.
Inventories are recorded at cost on the firm's balance sheet, but investors have no way of knowing whether the rise in inventory cost is due to a greater volume of purchases or to increased purchase prices.
I suspect it's a bit of both, but I'm concerned because rare stamps and coins are enjoying a China-fuelled boom at present. If Stanley Gibbons builds up large inventories at what may turn out to be the top of the market, it could eventually face substantial cash losses when the market softens.
What about value?
Stanley Gibbons trades on a revised 2015 forecast P/E of 20. This seems excessive, as does the price to sales ratio of 2.3.
Asset backing is uncertain too, in my view. The firm's book value of £85m is made up of £ 33m of intangibles resulting from recent acquisitions plus inventories of £50m.
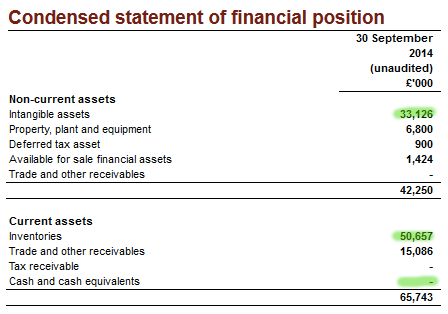
All of these assets could be subject to impairments if market conditions soften, or profit margins don't recover. It's worth remembering that stamps and other collectables have no intrinsic value and don't generate any income.
The shares currently trade at 1.4 times book value and 2.3 times tangible book value. This seems ample to me.
The only positive I can find is the yield. At 2.9%, this is above average for a small cap stock. Payouts have risen steadily for a number of years. However, I'd question how sustainable the dividend will be if cash flow doesn't turn positive in the near future.
Momentum: down
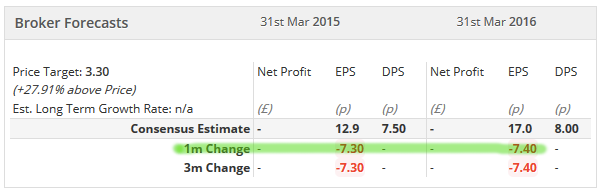
Gibbons' house broker, Peel Hunt, cut its 2015 earnings per share (eps) forecast for the firm by 36% after April's profit warning. At the same time the EPS forecast for 2016 was cut by 30%.
Stanley Gibbon’s shares had pre-empted these cuts for some time, falling by 15% over the last six months and still trading with negative momentum.
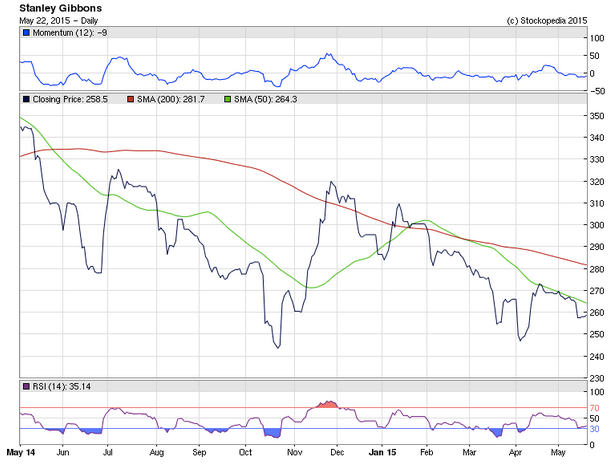
It's hard to see a near-term catalyst for the shares, which are not yet oversold and could drift lower. I suspect that the aggressive earnings downgrade by the house broker will prevent a rebound before the next financial results are published
Outlook uncertain
I'm not convinced that Stanley Gibbons' management has pulled off the difficult trick of generating value for shareholders through aggressive acquisition.
The firm's view that its extensive investments are about to start delivering is at odds with the financial evidence, in my opinion. At best, I expect the promised benefits to take longer to appear than expected. At worst, they won't appear at all.
We'll know more when the firm publishes its full-year results, probably in late June.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?