Stock Pitch - BOTB (LON:BOTB)

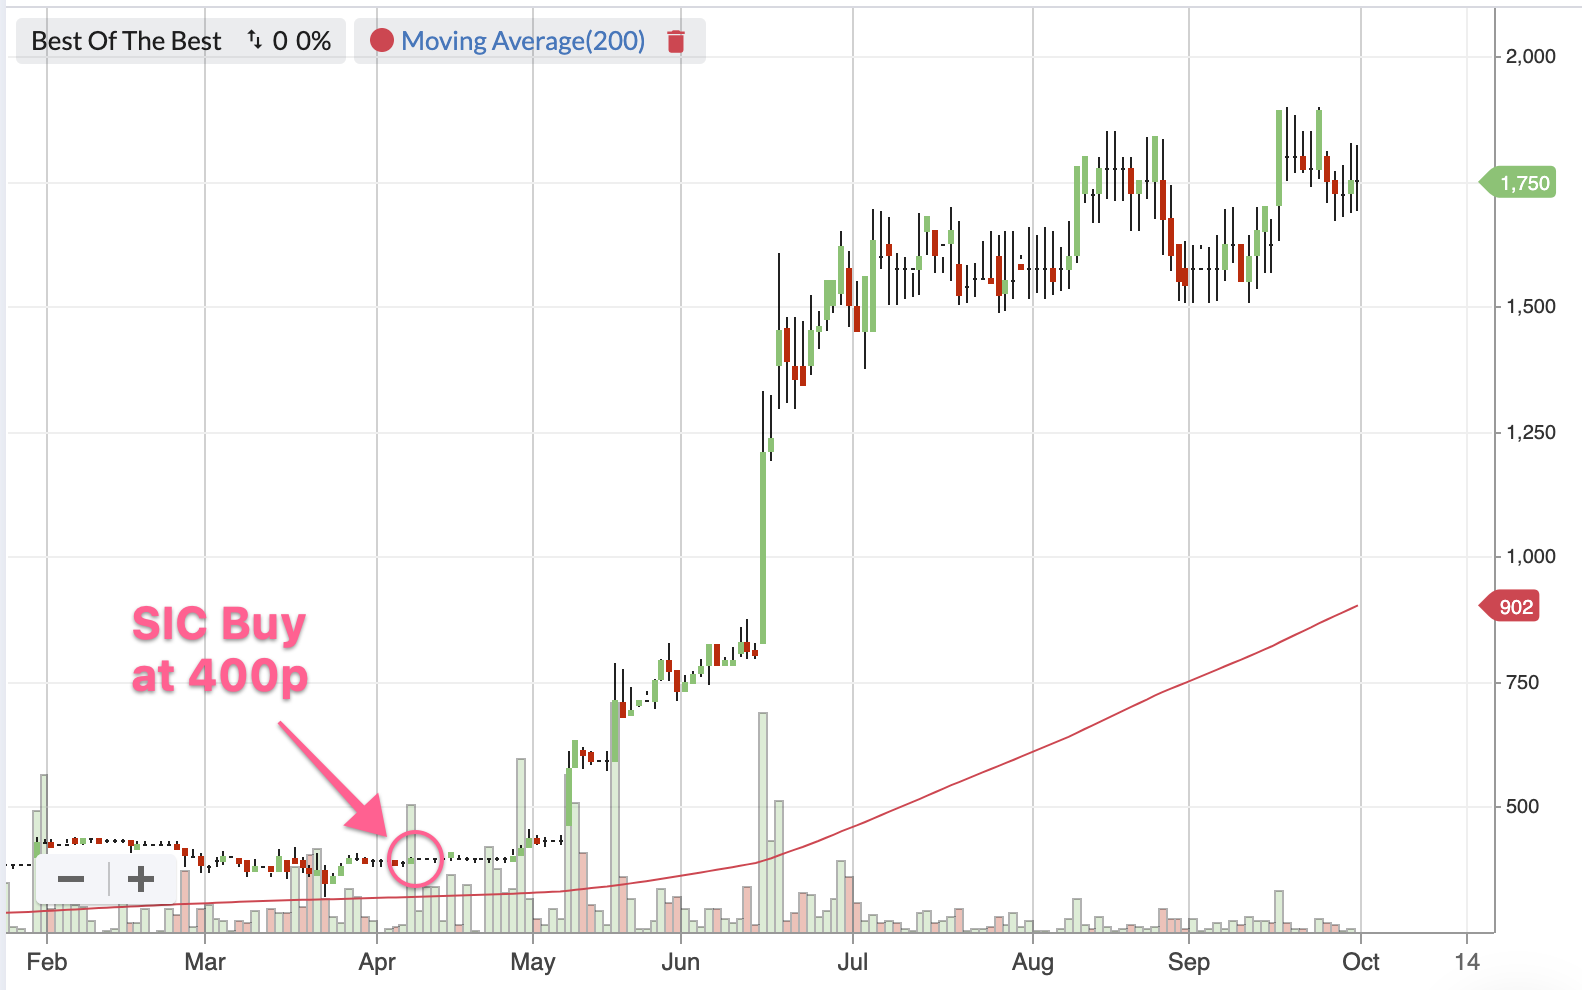
Best Of The Best (LON:BOTB) was pitched to the Stockopedia Staff Investment Club (SIC) in early April. On the 8th of April shares were purchased at 400p.
This wasn't the first stock pitched at the Stockopedia Investment Club - but it has played the biggest role in the SIC's performance to date and so is worth revisiting.
What we saw back in April was a cash generative micro cap with shareholder management, double-digit historic earnings growth, high returns on capital, a strong balance sheet, and a clear catalyst in the form of its pivot to a pure online business model.
What we didn't expect was such a rapid and material rerating. Since April, BOTB's performance has prompted useful discussions in the Club around position sizing and whether to run your winners or rebalance.
Here's why I think we should continue to hold at 1,750p.
Profile/Category/Style
What is the company's name and ticker symbol and on what exchange does it trade?
This is BOTB, formerly Best of the Best. It trades as BOTB on the Aim Market.
In which sector & industry group does the company operate?
It's in the Consumer Cyclicals sector under Hotels & Entertainment Services. Though we don't think this classification accurately captures BOTB's operations or market opportunity.
What is the share price, market cap, size group, liquidity and risk of the stock?
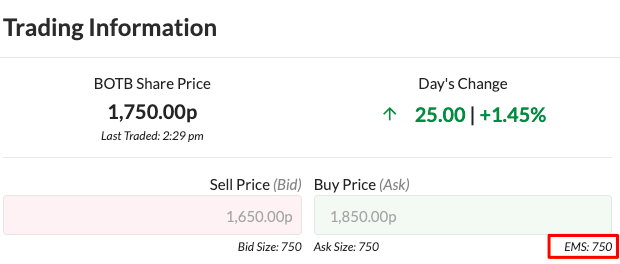
BOTB has had a fantastic run so far in 2020, with shares up nearly 400% year-to-date. Today its share price is 1,750p and its market cap is £160m, making it a small cap.
It's a Speculative stock so share price volatility should be expected.
Liquidity might be an issue for some. The exchange market size (EMS) is 750, meaning you can invest just over £13,000 (750 * £17.50).
What is the opportunity style/type/classification?
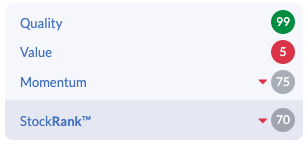
Quantitative: This is a cut-and-dry High Flyer. It has a high Quality Rank and high Momentum Rank with low Value Rank.
A period of share price consolidation is dragging the Momentum Rank and StockRank down, meaning BOTB no longer qualifies for the Club's watchlist - but it did at the date of the original pitch and purchase, back in April.
Qualitative: Peter Lynch framework
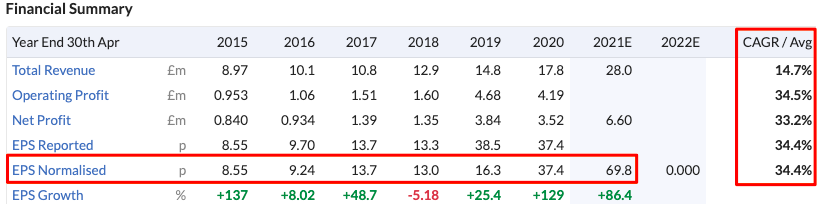
BOTB qualifies as a Fast Grower, with earnings growth comfortably in excess of 20% for the past five years (5y EPS CAGR: 34.4%; 3y EPS CAGR: 39.7%).
Business & Model
What does the company actually do, and what's its history?
Founded in 1999 by car enthusiast and current CEO William Hindmarch (who remains BOTB's largest shareholder with a more than 50% stake), BOTB runs car competitions.
Originally these were hosted in physical locations like airports and shopping malls. Importantly, BOTB has been evolving away from this model into a pure online play. This has been a transformational strategic pivot enabling the group to address a much larger market and generate higher returns on capital.
Competition tickets range anywhere from 15p to £8 and BOTB has had recent success in bringing in a new mid-week competition. Increasing price points and competitions continues to be a potential growth lever.
What is the company's business model? How does it make money?
BOTB operates three online, skill-based competitions in which participants stand to win a free car. These are the 'Dream Car', 'Lifestyle', and 'Midweek Car' competitions.
'Dream Car' is the principal competition.
'Lifestyle' features luxury watches, motorbikes, holidays, other gadgets/technology and cash prizes. With entry prices starting at just 15p, this has significantly broadened BOTB's addressable market.
The third weekly competition, 'Midweek Car' focuses on slightly cheaper entry points of £1-2 tickets.
Market & Competition
What is the state of the company's market & competition?
Finding data on BOTB's market and competition is slightly tricky. The market for lottery-style competitions is probably large, but poorly defined and subject to regulatory risk.
TechNavio reports that the global lottery market could grow at a compound annual growth rate (CAGR) of 10% - some $220bn - during 2020-2024.
Meanwhile, LaFleur's estimates the worldwide lottery market to be worth $310bn.
What is the company's strategy & competitive advantage?
Strategy - BOTB originally leased 26 sites in airports and shopping centres to market its competitions to passersby. Costs proved to be excessive and management discovered that online presented both a bigger addressable market and more cost-effective marketing.
Today, BOTB's strategy is to expand its competitions and products in order to target the much larger online addressable market using more efficient digital marketing channels.
Competitive advantage - perhaps not strictly a competitive advantage, but BOTB has great operational momentum. Earnings are growing fast and it is generating large amounts of cash, which can then be deployed into high-return digital marketing activities.
Others can set up rival services but it will take a while to build up the kind of customer database that BOTB has.
How does the company derive its competitive advantage and is it reflected in its financials?
BOTB has developed a highly profitable and cash-generative online luxury car competition business with very favourable returns on invested capital.
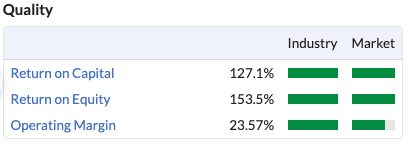
This has enabled strong earnings growth over time.
What trends is the company currently benefiting from that could provide a tailwind?
The 2020 lockdown environment actually benefits an online competitions business like BOTB, with millions of people stuck at home instead of going out.
This means they are saving disposable income and spending more time than ever online on their laptops and smartphones - both are active areas of investment for BOTB.
Recent History & News
What is the company's track record of growth & profitability?
BOTB has a 5y record of steady revenue growth. The increasing operational gearing of its online business model is evident in the forecast doubling in operating profit.
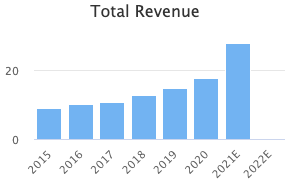
The group has repeatedly surprised the market with earnings beats and brokers have revised EPS forecasts multiple times.
Given this track record, there is always potential for BOTB to beat current EPS forecasts of 69.8p.
What's been happening in recent trading statements etc?
In fact, the group's most recent trading statement suggests this might happen again.
Per BOTB's recent AGM Trading Statement (16th September 2020):
Trading for the year to date has been stronger than expected at the time of the Company's final results (as announced on 15 June 2020). The momentum that built through the previous financial year has been maintained, resulting in a strong performance for the first four months of the new financial year and is expected to continue. This leads the Board now to expect both revenue and profits for the full year ended 30 April 2021 to be ahead of previous management expectations.
And yet brokers have not updated forecasts since July.
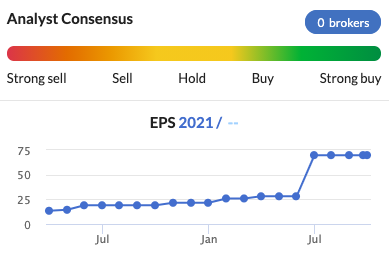
Assuming previous management expectations were similar to the July broker forecasts of 69.8p, this suggests BOTB is on course for 70p+ of earnings in FY21.
BOTB has put itself up for sale and is in talks with a number of interested parties 'from a number of sector verticals'. Discussions were quieter over summer but have resumed after the break.
Catalysts & Risks
Are there any catalysts could drive a rerating in the short or medium term?
BOTB has a history of beating forecasts.
Analysts have consistently revised forecasts upwards. It is the Anchoring and Adjustment bias in action, as well as the related Conservatism bias.
Now BOTB is fully online, it can deploy increasing levels of cash into high-return digital marketing initiatives. The returns on capital are triple-digit.
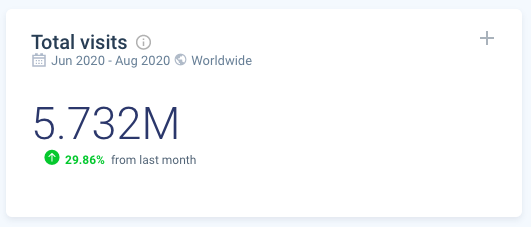
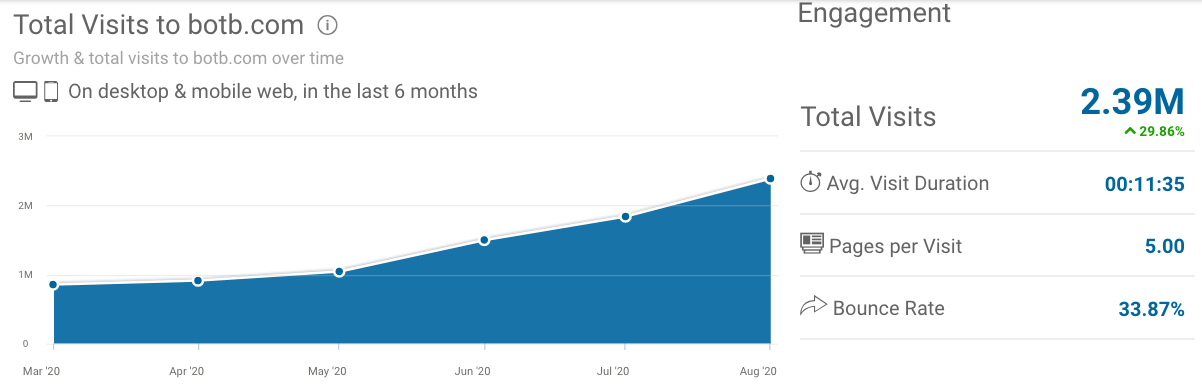
People have spent more time inside and online this year due to lockdowns. SimilarWeb shows strong traffic growth to BOTB's website - a positive leading indicator.
New competitions and price points could also increase revenue and addressable market.
Per BOTB's recent AGM update:
As previously announced, the Company launched a new additional 'Midweek' car competition in May, alongside its existing Dream Car and Lifestyle competitions. This, in combination with sustained investment in marketing and customer acquisition has delivered increased customer activity and a broader customer base.
What are the biggest risks for the business?
The biggest risks are:
Regulatory risk - BOTB's competitions are classified as skill-based. If its competitions are reclassified as gambling, this could increase regulation and impact profit.
Acquisition risk - BOTB has effectively put itself up for sale. If it fails to generate an acceptable bid, shareholders might be disappointed and the share price could fall.
Competition risk - Large, well-funded operators could set up rival services.
Ownership, Management & Financial Strength
What is the ownership structure of the company, and do management or founders have significant stakes?
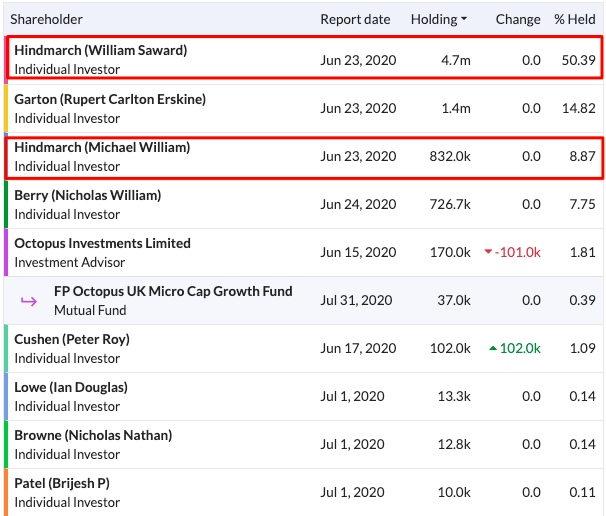
Dominated by individual investors, with CEO and founder William Hindmarch owning more than 50% of the company.
Has it a history of diluting shareholders, or (better) buying back shares?
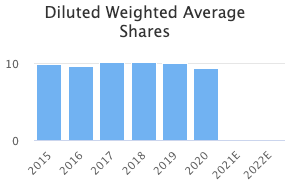
BOTB's share count has been reducing - this suggests the company has been buying back shares.
There are only a few main ways profitable, cash generative companies can allocate capital: internal investment, mergers and acquisitions, dividends to shareholders, and buying back shares.
Efficient capital allocation is key to generating high returns on capital and long term profitable growth.
A company that buys back shares generally signals strong financial health and cash generation - as it has the capital to buy its own stock - and also suggests that management thinks its shares are good value.
BOTB generates enough cash to pay dividends, opportunistically buy back stock, and invest in growth opportunities.

What is the company's financial status & balance sheet strength?
BOTB has an increasing net cash balance. This cash is being generated organically, rather than being raised by shareholders.
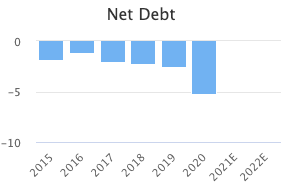
This is a good sign as it shows BOTB is generating enough cash from operations to pay dividends, invest in growth opportunities, and strengthen its balance sheet.
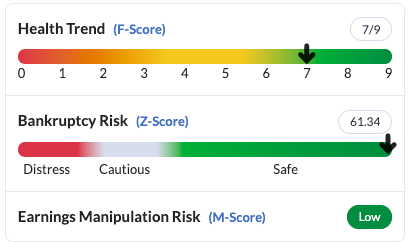
BOTB also scores well on the F and Z-scores, which assess financial health:
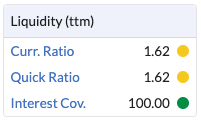
The liquidity ratios are also pretty robust.
BOTB has no debt, hence the 100% interest cover. Acceptable current and quick ratios vary between industries and business models - but generally, anything above 1.5x is solid.
Valuation
How is the company currently valued both absolutely and relative to its sector and the market as a whole?
BOTB doesn't have many comparable peers so relative valuation is tricky.
Look at the forecast EPS of 69.8p. This could well prove to be conservative as BOTB has instantly given a 'surpassing expectations' update in Q1 of FY21 but forecasts have not changed.
Given the share price of 1,750p, that's a TTM PE ratio of 46.8x. Divide the TTM PE ratio by the forecast EPS growth rate of 86.4% and you get a PEG of 0.52.
The forecast PE ratio is 1,750/69.8 = 25x. There are no forecasts for 2022, but assuming 5y normalised EPS CAGR of 34%, then the forecast PEG would be just: (1,750/69.8)/34 = 0.74. Anything less than one is seen as good.
What's more, I think now that BOTB has a good chance of growing at a faster pace than that 5y CAGR now it is fully online.
The risk in my view is that regulation or competition creeps in.
Sentiment
What would the person selling to us be thinking and who are they?
Sellers might include long term holders looking to take profits.
Others might become uneasy over possible regulatory risk, or believe that a well-funded entity might set up a competing operation.
Some may begin to doubt the sale process and take no news here as a cue to dump shares.
What is private investor sentiment at the moment?
Sentiment is positive, but investors are pausing for breath. Volumes were much higher in the first half of 2020.
Now it looks as though holders are in 'wait and see' mode given the ongoing self-declared sales process.
We could see profit taking on lack of news flow in the short term given the 2020 share price strength.
Disclosure: I hold shares in BOTB
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
I sold all my holdings at the start of this week. I also bought at 400, so a very nice profit to take. My logic is that this is a fantastic increase and we're about to see the start of a round of redundancies, US election theatrics, some Brexit dysfunction and that for the past few years Q4 always dips - and hence I'd like the cash on hand to go after some new bargains
https://www.ebaumsworld.com/jo...
I am Not convinced. More important the writer does not seem convinced either, giving more reasons to sell than buy. Anyone who bought on line business shares in April has done well. The question is where will they go from here?
You owe it to yourselves to develop a checklist 'Is this stock a Sell?' instead of using your Buy template as you seem to have done.
Here is one of mine as an example:
Hi Aflash
I disagree with a lot of what you noted, simply because you've stated everything possible that anyone might think of when looking at a stock + a few things just baffled me (why should I follow your guru?)
I have 2 follow-up questions:
It's a big holding for me, so if there is truly anything negative that I am missing - again, with an emphasis on the numbers - it would be great to understand more.
For reference, I track a bunch of metrics, including:
As with everything, there's always a risk eg sales might collapse next year, so I understand why it might be a sell for some, but right now, with the information we have, everything seems to be going in the right direction.
Cheers
A
abtan,
To start with your investment which is your concern, it is probable that you have a checklist of your own when pondering whether to Buy, Sell or Hold.
To continue with my checklist, it is an example as stated. A set of rules that I force myself to review when exhilaration or despair threaten to interfere with my thought process.
Everyone has their own method, adopted and adapted from their own sources and maybe Gurus. You have yours and your own investments. In no way do I want to influence them.
This new idea of a 'Stock Pitch' from a website that offers statistics is a step towards 'tips' and therefore questionable.
On BOTB (best of the best) I may or may not have an opinion. The only opinion I wish to express is on the methodology of the article as written.
A few observations from my own analysis (as I hold):
A lot of the prizes this year have been discretionary (eg an extra £50k cash prize included for free with every ticket),
ie the company is clearly growing revenues fast enough to justify a significant voluntary increase in costs.
In H1 FY21 2 out of 21 Dream Car winners were international winners.
There are similar trends with the runners up that are published each week.
It's highly likely therefore that all the growth this year is coming from domestic ticket sales.
Why is this good?
To me it implies that there remains much scope for expansion into international markets.
Note that only 16% of revenue was derived from international sources last year.
And as mentioned in 3. above, the international market seems relatively untapped - plenty of room for more players.
Fingers crossed.
A
Best Of The Best (LON:BOTB) - I also bought and for once made good money from spotting that the pivot to online was succeeding. However that was from 250p to 630p/share. I sold because even at that valuation, I thought it vulnerable to attack by a bigger, better funded company.
I personally looked into setting up something similar andthe technology required looked relatively straightforward to replicate. The only moat (which effectively blocked me and the several very small competitors) is marketing investment to drive awareness/trial. The airport selling provided BOTB with that initial base they are now exploiting. But if one of the big gambling companies set their hat it with their already owned massive databases and basic internet and back office infrastructure, how hard would it be for them to take over in 2-3 years?
At 1750p/share, the current capitalisation is shown on stockopedia at £164Mn. This seems a lot to pay for the 'convenience' of a running start.
Just a quick observation: Altman Z scores over 55 are one of the "watch out" signals I noted when I was looking to see if you could have too much of a good thing.
Hi Nick,
I think I recall your post from a while back - it's an interesting statistical observation and worth bringing up.
Have just taken a quick look at Best Of The Best (LON:BOTB) 's Z-Score for anyone interested.
The first pass looks to be as a result of an increasing cash balance from the group's organic cash generation, from 66% of total assets in FY19 to 77% in FY20.
Check 2 - retained earnings as a % of total assets has also increased
Check 3 - EBIT as a % of total assets is up, due probably to more profitable top line growth from increasing online sales
Check 4 - market value to book value of total liabilities is strong as BOTB has not had any debt for at least the past five years, although the group has reported an increase in trade payables from £1.8m to £3m
I've looked at some historic StockReports and the Z-Score was lower 1 (19.9) and 2 (16.3) years ago. Is it too much of a good thing now? There are clearly some diverse opinions on this one which is good to see - DYOR as always
If the regulatory risk does happen this will be a blood bath as everyone tries to sell in a very illiquid stock.
Something similar could happen if one of the big gambling companies started a similar‘competition’, which could easily happen as there is nothing here that cannot be copied.
So, I feel that it is too much of a gamble. I know Paul and many others have done well from it but it could easily have been very different.
Masterclass. Not being an accountant brilliant to help understand the stocko algos.
Hold thanks to Paul 'head up' but getting bored - so a so called 'weak hand', but I prefer 'seeking other opportunities'. On basis of this will hold my impatience and maybe dip in if can get rid of my miners.
I'm surprised it isn't already categorized as gambling.
I had the misfortune to sell my 3,500 shares in Best Of The Best (LON:BOTB) on 25th February thus missing out on a huge re rating a few weeks later.
I made a 32% gain on the share after reading Paul Scotts comments quite some time ago.
A great example of time in the market not trying to time the market!
Its worth noting that although the dividend % is small, they tend to pay out larger, more generous special dividends. It will be interesting to see if there is a further re-rating over the next 6 months :-)
I wouldnt touch this stock. I used to work for this company in sales. All I can say is alot of lying to customers and sales staff on commission only saying and doing what ever they can to earn a living because if they're not making money for the company they are thrown out very easily. Management know what happens, numbers look great but I'd stay well away
Phones4U were similarly good with bonus but you had to perform.
Hi Khalis2k
Sales staff? Commissions?
Can you elaborate please?
I thought the only "commissions" related to the referral programme.
And Best Of The Best (LON:BOTB) has sales staff? Marketing staff I can understand, but what are the sales staff doing?
Cheers
We could do with more info on employees' roles but here is a helicopter view of numbers......admin 17!