Stock Pitch - Ferrexpo (LON:FXPO)
Ferrexpo was pitched to the Stockopedia Investment Club (SIC), for the second time, on 2nd February 2021.
One of the most consistent high-ranking shares in the market, Ferrexpo has always been on the SIC’s radar of potential Stock Pitches. In August last year, after a recovery in the iron ore market, Ferrexpo was finally pitched to the SIC.
At the time, some looming corporate governance issues led the SIC to opt against purchasing shares. The shares, however, soon went on to almost double over the subsequent 6 month period!
After a recent retracement in the share price, despite the continued strong fundamental backdrop for iron ore prices, buoyed by the ever-growing steel demand from China, Ferrexpo was once again pitched to the club.
As a speculative, mid-cap, super stock, Ferrexpo possesses some intriguing attributes, especially given its unique positioning as a premium iron ore pellet producer in Europe. With iron ore prices close to their highest point since 2011, does Ferrexpo warrant a position in the SIC portfolio this time around?
Summary
Bull Points - Iron ore prices close to their highest point in almost a decade, transformational free cash flow generation for the foreseeable future, production expansion on-going with higher grade 67% Fe pellets, generous capital returns structure, improving balance sheet which might be used to propel future growth opportunities.
Bear Points - History of directorate issues, reliance on iron ore prices, single asset/region risk.
Profile
Ferrexpo (LON:FXPO) is a FTSE 250 listed company, operating in the Metals & Mining industry. The company is one of the largest exporters of premium iron ore pellets in the world, which it produces from its mining activities in Ukraine.
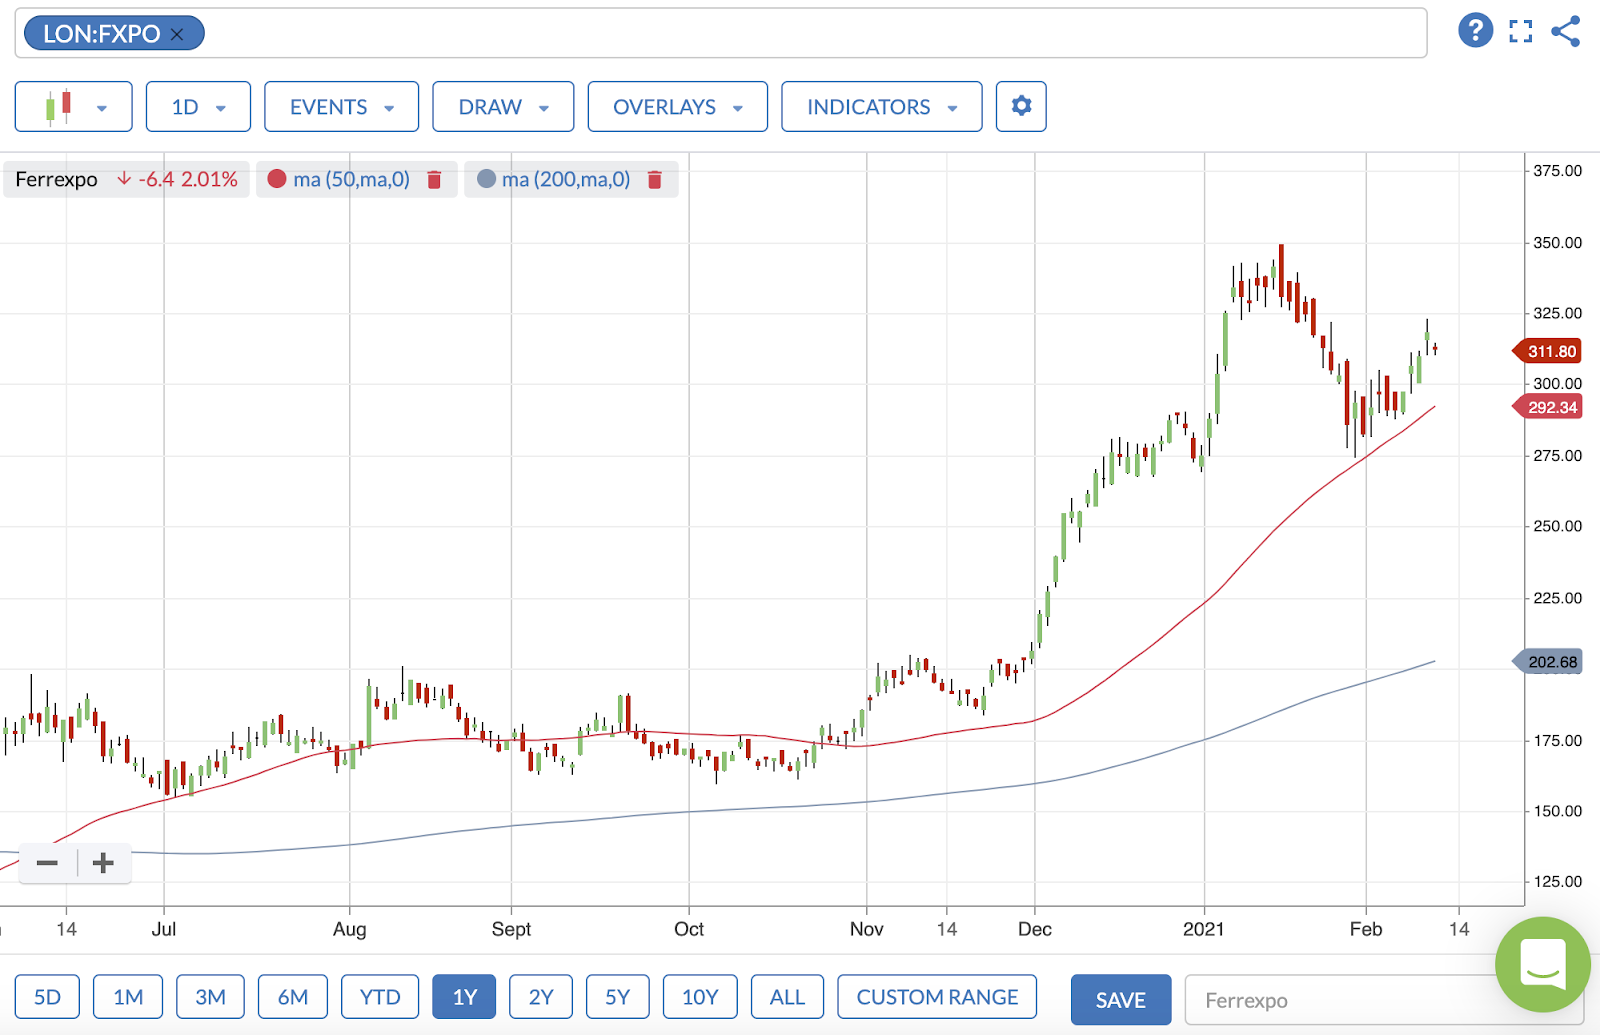
At the current share price of 312p, Ferrexpo’s market capitalisation is worth just over £1.83 billion. After a fairly volatile 2020, Ferrexpo shares ended the year in a position of strength, largely mirroring the performance of iron ore prices.
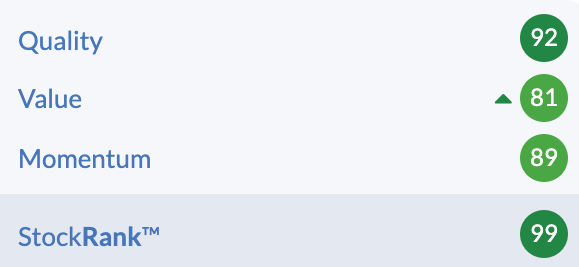
The Speculative, Mid Cap is also currently classified as a Super Stock, due to its all-round impressive value, quality and momentum characteristics. Evidence of this can be seen by the 99 StockRank rating of the company. Both the Value & Momentum Ranks remain above 80, whilst the Quality Rank has reached 92.
A quick glance at some of the key ratios highlights the health of the company’s financials. The 12m forecast P/E is 4, making it one of the lowest in the entire market. Its forward dividend yield sits at 7.37% at the time of writing.
Ferrexpo’s exposure to different factors means that it currently qualifies for 5 different Guru Screens, across Value, Quality, Momentum & Income investing.
Business & Model
What is the company history & what does it do?
Ferrexpo has been producing iron ore pellets from its mining operations in Ukraine for over 40 years. Located in the Poltava region of Ukraine, its asset base contains the largest iron ore deposits in Europe with approximately 1.7 billion tonnes of resources. The current life of its mines is expected to last another 55 years based on current rates of production & reserves.
The company currently operates 2 open-pit mines, with an associated processing facility. Ferrexpo’s integrated logistics capabilities, combined with Ukraine’s proximity to major steel markets allow it to competitively rail, barge and ship products to premium steel mills around the world.
The company IPO’d on the LSE in June 2007, and is headquartered in Switzerland.
What are the key business segments and revenue breakdown between them?
Ferrexpo generates its revenues by producing and exporting high-quality iron ore pellets to premium steel mills around the world who produce sophisticated steel products. These high-quality pellets contain either 65% or 67% iron, which are the highest grades in the global pellet industry.
Ferrexpo only started producing 67% Fe pellets in 2020. However, 99% of Ferrexpo’s 2020 iron ore pellet production were these premium (65% Fe & 67% Fe) pellets.
The company’s products represent an attractive alternative to Brazilian and Canadian suppliers due to the closer proximity for a continuous small-parcel delivery chain. A lot of its key customers are based in Central & Western Europe, in addition to the East Asian markets.

Source: Ferrexpo.com
Market & Competition
What is the state & size of the company's market and who are its competitors?
The global iron ore mining industry is estimated to be worth over $215 billion a year and has been growing by 9.5% on average over the past 5 years (according to IBISWorld). Iron ore pellets represent a smaller subset of this, but the industry was still valued at $47.63 billion in 2019. Furthermore, the global iron ore pellet industry is expected to grow by a compound annual growth rate of 3.7% over the period 2020-2027 (according to Grand View Research).

Source: www.grandviewresearch.com
Ferrexpo is currently the 3rd largest exporter of pellets to the global steel industry. In 2020, the company produced a total of 11.2 million tonnes of pellets with higher performance pellets (FPP+) representing 99% of total pellet production. Total market share of the iron ore pellet industry stood at 8% in 2019.
Direct competitors in terms of high-grade pellet production include Vale & LKAB, which are the two largest global producers respectively. Some of the larger iron ore producers include Rio Tinto, BHP, Anglo American & Fortescue Metals. There are a few other smaller players in Australia, but Ferrexpo is unique in its mid-cap status and high grade pellet offering.
What is the company's strategy?
The company is targeting near term production expansion to produce 12 million tonnes of high grade pellets in 2021. From 2007-2019, Ferrexpo invested over $2.5 billion in developing and optimising its operations. These measures have added significant additional capacity to process iron ore pellets at higher grades & lower costs. Further pelletiser upgrade work will be undertaken 1H 2021, which is estimated to provide 0.5-1.0Mt additional capacity in the future.

Source: Ferrexpo
Over the next 10 years, $2 billion has been earmarked for further capital expenditures. The aim is to double current production rates by the end of the decade. The heavy capital costs of entering this market represent a significant barrier to entry.
How does it derive its competitive advantage (if any)?
The company's key competitive advantage lies in its premium pellet production, which are the highest grades in the global pellet industry. Last year, Ferrexpo started producing its first 67% Fe pellets, which should contribute significantly to the profitability metrics for the company.
Whilst the company positions itself for growth, Ferrexpo also has a good record of cost control. In 2015, it reduced its C1 costs of production by 30% ensuring that it is one of the lowest cost pellet producers in the world.

Ferrexpo’s premium pellet offering, combined with its tight control over costs has enabled the company to achieve some of the highest operating margins in the industry. Indeed, its EBITDA margin per tonne is in line with, or better than the Big 4 iron ore producers (Rio, Vale, BHP, Fortescue).
Is the competitive advantage durable and is there any evidence of one in the financials?
Evidence of the company's competitive advantage can be seen quite clearly by the quality metrics on the StockReport. The 5 year averages for Return on Capital Employed and Operating Margins are both over 30%, whilst the 5 year average Return on Equity is over a staggering 50%. These statistics are amongst the best in the industry, and the market as a whole.

Financials & Ownership
Whilst revenues have grown slowly, net profits have grown by a CAGR of over 17% over the past 6 years. As iron ore prices continue to improve and production expands towards producing even higher grade 67% Fe pellets, profits and revenues could be set to grow substantially further.

The business has demonstrated it can still generate consistently high levels of profits throughout the commodity cycle, with no losses posted in the past 10 years, even when iron ore prices were less than 3 times the levels they are today.
What is the state of the balance sheet?
The balance sheet is in the best shape it’s been in over the last 10 years, with Ferrexpo holding a net cash position of approximately $4M at the year end. This is compared to a net debt position of $282 million at the end of 2019.
Is there evidence of historic share dilution or buy backs?
There have been no share dilution or buy-backs in recent years, although buy-backs are more likely to be on the cards given the rapidly improving cash profile of the company.
What is the ownership structure of the company and do management have stakes?
Kostyantyn Zhevago, the former CEO, still holds the largest holding in the company, which has created issues in the past. This will be discussed later in the ‘Recent Trading & News’ section.

Directors have been re-investing their dividends to acquire additional shares over the past year.
Valuation
How does the relative valuation compare versus industry and sector?
The valuation is perhaps one of the most enticing characteristics of Ferrexpo. The 12m forecast price to earnings ratio sits at just 4, whilst earnings per share are expected to grow at over 20%. This gives a remarkably low PEG ratio of 0.2, highlighting just how cheap the company is when growth is taken into account.
The company is in the top quartile of its industry for the majority of the valuation metrics analysed. Ferrexpo offers good all-round value, whether it be what the company owns, earns or what it pays out.

It is also worth highlighting the company’s special dividend payouts in recent years that may sometimes go unnoticed. The generous dividend policy may improve even further should the company continue to generate current levels of free cash flow.

Trends & Catalysts
Are there any significant macro trends that the business is benefiting from?
China's insatiable demand for steel has been driving iron ore prices to their highest point since 2011. Although iron ore has dropped back from the levels seen last December, the commodity remains significantly higher than its 2020 levels.
Whilst China's demand for additional iron ore to fuel its steel manufacturing is expected to subside in 2021, Europe and the rest of the World are expected to account for a worldwide 4.1% increase in steel demand (according to worldsteel association).
Are there any catalysts that could drive a rerating in the medium term?
Whilst iron ore prices will continue to hold a great influence over the company's share price, the company's preliminary full year results on 17th March 2021, could lead to a rerating.
Longer-term the company plans to increase its pellet production towards 20 million tonnes per year. Further progress in production expansion could act as a further catalyst.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
Market Risk - Iron ore prices are highly reliant on steel demand. Should a major economy such as China suffer any further setbacks, this could cause a major fallout across commodity prices, but especially base metals.
Operational Risk - Although there have historically not been any issues at the mines that Ferrexpo operates, there can always be unforeseen circumstances and issues.
Management Risk - There are still on-going issues surrounding dealings of former CEO and key shareholder of Ferrexpo, Kostyantin Zhevago, although these centre around issues with his former company and not Ferrexpo. James North has been appointed as its acting chief executive officer, which seems to have cleared up most of these problems.
Political Risk - The region has been volatile in the past. Should conflict break out as it did in 2014, this could severely impact operations, which are close to the Russian border.
Recent Trading & News
Trading Update and Production Report for Q4 2020
- Total iron ore pellet production rises 22% quarter on quarter to 3.1MT in 4Q 2020, following the successful ramp-up of the Group’s concentrator expansion project.
- Total full-year production of iron ore pellets of 11.2MT in 2020, representing an increase of 7% on 2019.
- Production of high quality 65% Fe and 67% Fe pellets represented 99% of total pellet production in 2020 (2019: 96%).
- Total full year sales volume of 12.1MT in 2020, up 18% on 2019.
- COVID-19 update: Ferrexpo’s operations and logistics continued to operate with minimal impact during 4Q 2020.
- Group net cash position as at year end of approximately US$4M, following strong financial and operational performance in 2020. (Net debt position as of 31 December 2019: US$282M). The Group’s cash balance as of 31 December 2020 was approximately US$270M (31 December 2019: US$131M).
Kyiv Court Cancels Ferrexpo AG Share Restriction
This was an important news announcement relating to the restrictions that the Kyiv district court placed on 50.3% of the shares in Ferrexpo Poltava Mining (a subsidiary held by Ferrexpo). The restrictions on these shares were as a result of ongoing investigations into former CEO, Kostyantin Zhevago, and one of the businesses he owned up until 2015.
Whilst the restrictions didn’t affect mining operations, it did mean that the shares in the company could not be transferred. On 30th November, Ferrexpo’s appeal against these restrictions was successful and the restrictions were lifted.
Sentiment
What do the brokers currently think and are they upgrading estimates?
Whilst some brokers remain cautious, they have been steadily upping their EPS estimates since July.

What is private investor sentiment at the moment?
Whilst Ferrexpo isn’t on the radar of most private investors, the rhetoric on social media & bulletin boards is very positive. The recurring theme seems to centre around the company’s potential for substantial free cash flow generation over the next few years & the dividend policy.
What would the person selling to us be thinking and who are they?
After an impressive run, which saw the shares more than double in just over half a year, there has been some profit taking. This has caused the share price to retreat from its early January highs.
Sellers are likely to include those who are pessimistic about a global recovery. Steel demand is expected to rebound strongly in Europe and the Americas this year, which could propel iron ore prices higher. However, should the economic recovery of these regions prove to be relatively muted, this could have negative consequences for Ferrexpo.
Conclusion
Having missed out on a potential 100% gain the first time around, the SIC voted in favour of purchasing shares in Ferrexpo at the second attempt. Shares were acquired on 4th February 2021, at a price of £2.92.

Ferrexpo has some redeeming all-round qualities, but having bought quite near the top, has the SIC made the right decision this time around?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Great piece and tells a very positive story. One of the things which is not clear to me is the scale of capacity growth in iron ore production and how that compares to the 3.7% CAGR for iron ore demand. Understanding this would help to evaluate the risk of a supply glut in the coming years. From the article I have linked to below, it seems that capacity growth is likely to be slower than demand growth due in part to consolidation. If that is the case I would be bullish iron ore and Ferrexpo over the next decade or so. The point, well made in the article, is that there is demand risk, as much of the growth will be Chinese. But I currently hold and might consider adding more if I can verify that the iron ore supply-demand balance is likely to tighten over the next decade.
https://m.miningweekly.com/art...
Hi Ike O,
Thank you for your comment!
Due to the capital intensity requirements of Iron Ore development projects, and a decade of underinvestment, the supply-side dynamics are set to remain quite favourable for iron ore for the foreseeable future.
Mining disruptions in Brazil over the past year, along with storms affecting the world's largest iron ore export hub of Port Hedland, Western Australia, have also helped to alleviate any shorter-term supply concerns.
Kind regards,
Keelan
Well written piece.However you have to remember demand for steel has to be bouyant for Ferrexpo to prosper.There has been a glut in steel manufacturing by China in the last couple of years.The price of steel has dropped.Unlike Gold steel has other uses.If you compare gold price today does not mean that there is a huge demand for gold and everybody wants to wear gold jewellery.The only reason why it went up was to hedge against inflation. At the moment we have deflation because of lock down.However the Bank of England is expecting growth to be upto 5% and inflation will follow as a result of liquidity in the markets.
Try and remember the four P s (Product,Price,Place and promotion).You wrote Europe is the main market for iron pellets.High quality stuff ,where can it be used Aero space etc .The industry is in difficulty.Construction, steel frame for building systems projects on hold.etc etc
Most important is to look at the market share,49 percent iron pellets is exported to Central Europe.What is Ferrexpo s market share in different regions.
Stock rank is not a reliable judge for Ferrexpo s performance.If you look at all the companies in London stock exchange ,they have all gone up as a result of QE and not organic growth.
Coincidentally Ferrexpo came up in my stock screen yesterday (currently the only one!) so will def look closer. Great write up.
Good write up Keelan, I have held this share, Ferrexpo , for years and it has been one of my speculative losers. But because it always seemed cheap, I have held on to them. When I joined Stockopedia two years ago, Stocko ratings were good, so thankfully I decided not to cut my losses. Your write up makes me want to carry on holding. They still look cheap, but after I have held them for such a long time, I ask myself (wearily), will that really change? Hopefully so.
I first bought Ferrexpo (LON:FXPO) in 2015 at 64p. Over the years at has been my most successful share and I know it well.
Not very long after my first buy it lost $175m when its Bank in Ukraine went bust. At one point the SP fell below 20p.
In 2015 it had a fair bit of debt and the PE has always been low single figures. In my opinion it is very well managed. The Management think long term and cap ex has been high but if in the next few years they increase production to 20 million metric tonnes from 12m in 2020 it will be a cash cow.
Great report Keelan but as muckshifter says a 35% Swiss Withholding Tax is very irritating.
I think I remember Chris Dillow, from the IC. Suggested watching the money supply (M0) to identify future demand for commodities. Notably in China
One more point that I don't think you mentioned was the irritating Swiss tax on dividends. The dividends are excellent but they are taxed at 35%, with no easy way to reclaim it.
Hi muckshifter,
Thank you for highlighting this important point! It's always important to consider tax implications depending on where you live & invest.
Kind regards,
Keelan
Very pleased at this write-up, especially as it's reinforced much of my own personal research I undertook before purchasing FXPO in May 2020, although Keelan's research is certainly a lot sharper.
The R&D into the new higher grade pellet at 67% is big factor in the success of this company, but as production ramps up with the higher grade pellet it will be interesting to see how the steel market reacts.
I've been topping up on this one, as and when there are some dips.
Kostiantyn Zhevago owns 50.3% through Fevamotinico S.a.r.l. - not sure where your 7.64% comes from.
https://www.ferrexpo.com/investor-relations/shareholder-services/shareholder-analysis
Phil
(I hold)
Hi Edward,
Thank you for having flagged this issue. I have been in touch with our data providers to check and update the shareholder register. The changes have now been made, I have attached a link to the page below.
https://www.stockopedia.com/sh...
Kind regards,
Keelan
Helpful, how I swish that I had stayed in. I sold out at £1.80 last year after months of volatility. Gey ho!, win some. lose some, hopefully fewer!
Great write up on Ferrexpo FXPO, confirming my own thoughts on this excellent and slightly under the radar company. I topped up on the 4th Feb 2021 after seeing Credit Suisse being bullish on Iron Ore prices over the next 3 years. With 2020 average iron ore prices being around 20% greater than 2019 average prices, plus FXPO's 7% increase in output despite Covid in 2020, the YE results on 16th March, should reward all current holders.
Hi DAZZA64,
Thank you for sharing your thoughts.
The Credit Suisse forecast is indeed very bullish and points to renewed optimism for iron ore producers. Vale's weaker Q4 iron ore production also seems to have provided further support for iron ore prices recently.
Kind regards,
Keelan
One comment on allocation and diversification, is this not considered by the club?
You seem to have 3 commodity shares now, 2 of which are South Africa platinum producers.
I bought some on the same date and at the same price.
Hi Herbie,
We do discuss diversification at the Club but our current thinking (as an investment club) is that tactically shifting towards a slightly larger exposure to commodities is justified in the current environment. This is a higher risk strategy, but the club itself probably has an above-average risk tolerance.
Importantly though, this decision must be put in context: the SIC PF's largest holding right now is cash. It's currently more than 25% cash in fact. Also position sizing - the average position size in the Folio is probably something like 5-6% at present, although SLP's strong run means it is now notably more than that.
With three metals producers ( Ferrexpo (LON:FXPO) , Tharisa (LON:THS) , and Sylvania Platinum (LON:SLP) ), our exposure to basic commodities is weighing more and more on our decision-making process. But we also have no exposure to oil & gas, gold, silver, or copper, to name a few. So I wouldn't rule out further commodity-related pitches. Whether or not the Club votes to buy based on them is another matter of course!
Hi Jack, have you had a look at Bushveld Minerals (LON:BMN) for Vanadium exposure and Atalaya Mining (LON:ATYM) for Copper?
Hi joshwood976,
We'll be taking a closer look at Atalaya Mining (LON:ATYM) in the coming weeks. Bushveld Minerals (LON:BMN) may also be added to our watchlist at some point in the future.
Kind regards,
Keelan